GSTR-1 - 11-Oct-2026
GSTR-3B - 20-Oct-2026

Registration Services

Choosing a legal structure is an important decision when starting a business. A sole proprietor may begin with a small consultancy, a partnership may start with two founders, or a startup may register as a Limited Liability Partnership (LLP) because it suits the initial business model.

But a business does not remain the same forever.

A small enterprise may start hiring employees, take on larger clients, seek outside investment or expand into new locations. The founders may then discover that their existing structure no longer suits their plans. A private limited company may also decide that an LLP better fits its ownership and operating model, subject to the applicable legal and tax conditions.

This leads to a common question: Can you change your business structure after registration, or must you start again?

The answer depends on the legal form you currently have, the form you want to adopt and the route permitted by law. It is not safe to assume that every business can simply “convert” by filing one form with the Ministry of Corporate Affairs (MCA).

This guide explains the main routes available in India, the checks to complete before conversion, and the registrations and records that may need attention afterwards.

What does changing a business structure mean?

Changing a business structure means moving from one legal form of business to another. Examples include:

  • A sole proprietorship moving its business into a private limited company.
  • A partnership firm converting into an LLP.
  • An LLP registering as a company under the applicable legal route.
  • A One Person Company (OPC) becoming a private limited company.
  • A private limited company converting into an LLP, where eligible.
  • A private limited company converting into a public company.

These changes are different from changing a company’s name, registered office, directors, shareholders or business activities. Those actions may require their own approvals and filings, but they do not necessarily change the legal form of the entity.

For example, a private limited company can update its permitted business activities where legally appropriate without becoming an LLP. Likewise, changing a proprietorship’s trade name does not create a separate incorporated entity.

The first step is therefore to identify the change you actually need.

Why might a business want to change its structure?

There is no single reason for restructuring. Common triggers include the following.

Bringing in investors

A startup may want to issue shares, create an employee stock option plan or prepare for an equity investment. A private limited company is often considered for these goals, although the correct structure depends on the investor, business model and applicable rules.

Managing liability

A proprietor and the business are not separate legal persons in the same way as a company. An LLP or company may offer a separate legal identity and limited liability, subject to statutory exceptions and the facts of the case.

Reducing or changing compliance responsibilities

A founder may find that a company’s governance and filing obligations no longer match the scale or operating needs of the business. An LLP may be worth evaluating, but it is not automatically cheaper or simpler in every situation. Conversion itself may involve professional fees, filings, tax analysis and changes to registrations.

Adding co-founders or changing ownership

A sole proprietor may wish to formalise ownership with another founder. A partnership may want to introduce more structured governance, while an established company may consider a different ownership or capital arrangement.

Preparing for expansion

Larger customers, lenders, tenders, licences or business partners may have preferences or eligibility requirements relating to the supplier’s legal form. Confirm the actual requirement rather than restructuring based on assumptions.

Practical point: Changing a structure should solve a defined business problem. Do not convert only because another structure is popular or because someone claims it guarantees lower tax or fewer compliance obligations.

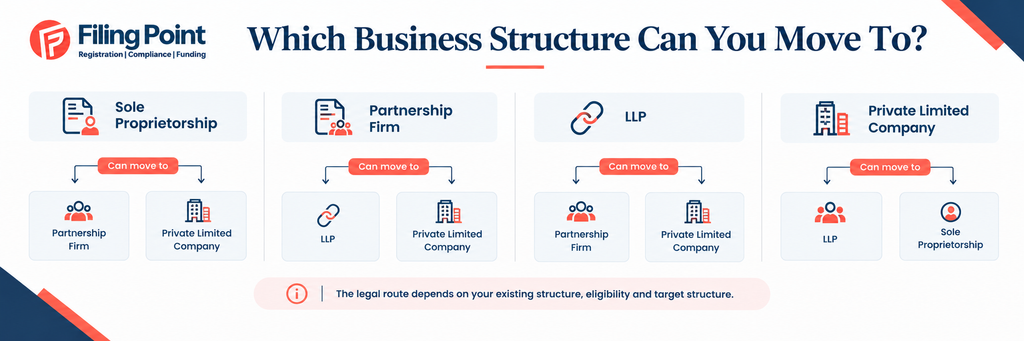
Which business structures can be changed?

The table below is a starting guide, not a determination that every business is eligible.

Existing structurePossible target structureGeneral route
Sole proprietorshipPrivate limited companyUsually incorporate a new company and transfer the business
Sole proprietorshipLLPUsually form an LLP and transfer the business
Partnership firmLLPStatutory conversion route may be available if conditions are met
Partnership firmCompanyRegistration under the applicable Companies Act route may be available
LLPPrivate limited companyRegistration under the Companies Act route may be available, subject to requirements
OPCPrivate limited companyCompany conversion process under applicable company law
Private limited companyPublic limited companyCompany-class conversion under the Companies Act
Private limited companyLLPStatutory conversion route may be available if the conditions are met
Private limited companyOPCPossible only if current legal requirements and eligibility conditions are satisfied

The legal route, approvals, forms and consequences differ. Confirm the latest MCA requirements before starting the transaction.
Business Structure Conversion

Conversion is not always the same as creating a new business

This is one of the most important distinctions in business restructuring.

When a statutory conversion route exists

Certain types of firms and entities can register or convert into another form under a specific legal provision. For example, the Companies Act, 2013 provides for conversion of companies already registered under the Act into another class of company, subject to the applicable requirements. Section 366 and the Companies (Authorised to Register) Rules, 2014 provide a route for specified entities, including LLPs and partnership firms, to register as companies. The LLP Act also provides conversion routes for specified entities.

The correct route depends on the existing entity and target structure. Relevant provisions include Section 18 and Section 366 of the Companies Act, 2013, and the applicable schedules of the Limited Liability Partnership Act, 2008.  

When a new entity must be formed

A sole proprietorship is not a company registered under the Companies Act. It generally cannot be transformed into a private limited company by simply changing its registration type. Instead, the proprietor incorporates a company and transfers the business or relevant assets, contracts and operations to it under an appropriately structured transaction.

That transfer needs careful planning. It may involve agreements, consent from counterparties, asset-transfer documentation, employee arrangements, tax analysis and fresh or amended registrations.

Why the distinction matters

The two approaches can have different effects on:

  • The identity of the legal entity.
  • Existing debts and obligations.
  • Ownership of assets and intellectual property.
  • Customer and supplier contracts.
  • Bank accounts and borrowing arrangements.
  • Tax treatment and potential tax costs.
  • Licences, permits and registrations.
  • Business continuity and documentary evidence.

Do not assume that every licence, tax registration, contract or bank account automatically continues unchanged. Check each one separately.

How to choose the right conversion route

Before selecting forms or preparing documents, answer these questions.

Check the actual registration documents. A business using a trade name may still be a proprietorship. An LLP has an LLP identification number (LLPIN), while a company has a Corporate Identity Number (CIN). A partnership firm may have a partnership deed and, where applicable, registration with the relevant state authority.

Do not base the decision solely on the business name, GST certificate or Udyam registration.

Step 2: Define the target structure

Decide whether the goal is to become a private limited company, LLP, public company or another permitted form. The reason matters. A funding requirement, liability concern and desire to reduce administrative work may lead to different conclusions.

Step 3: Check statutory eligibility

Review the conditions applying to the specific conversion. Depending on the route, these may concern ownership, consent of partners or shareholders, creditors, security interests, company filings, capital, constitutional documents or other statutory conditions.

For example, an LLP-to-company registration route under Section 366 is not the same as a private-company-to-LLP conversion under the LLP Act. Do not use a generic “conversion checklist” for both.

Step 4: Review pending compliance

Before proceeding, check whether returns, financial statements, annual filings, tax returns, statutory registers or other obligations are outstanding. A conversion plan should include a method for addressing defaults and determining which obligations remain due.

The exact requirements depend on the entity and transaction. Review the MCA record and relevant tax records instead of assuming that conversion automatically resolves past non-compliance.

Step 5: Review tax implications before transferring assets

Identify the business assets, stock, receivables, liabilities, goodwill, intellectual property and capital balances. Ask a tax professional to assess the proposed transfer and the applicable conditions.

Some transactions may qualify for specific tax treatment if statutory conditions are met. That treatment should never be assumed merely because the parties call the transaction a “conversion”. The Income Tax Department’s guidance on Section 47 describes conditions for certain forms of business succession and company-to-LLP conversion. https://www.incometaxindia.gov.in/w/capital-gain

Step 6: Map contracts and registrations

Prepare a list of every registration, licence, contract, bank facility and online account linked to the existing entity. Identify whether it must be transferred, amended, surrendered or obtained afresh.

Step 7: Prepare a written implementation plan

Set out the approvals, filings, transaction documents, responsible people and dependencies. A conversion should not be treated as complete merely because a new certificate has been issued.
GST Registration Chennai

What happens to GST, PAN, bank accounts and other registrations?

This is a major area of risk because business owners sometimes focus on the MCA filing and overlook operational continuity.

PAN and income-tax records

A new legal entity may require its own PAN and tax registrations. Whether a PAN changes or a new one is required depends on the legal route and whether the same legal person continues. A proprietorship-to-company transfer, for example, should not be treated as though the proprietor and company were the same taxpayer.

Review income-tax filings, tax credits, advance tax, TDS/TCS obligations, books of account and any tax attributes before the transition.

GST registration

GST treatment depends on the legal structure, the transaction and applicable GST rules. A transfer of a business as a going concern, a transfer of assets, or a change in the person carrying on the business can have different implications. The old registration should not simply be reused for a different legal person without checking the applicable requirements.

Plan for outstanding returns, input tax credit, stock, invoices, customer advances, tax liabilities and the effective date of the transition. Confirm whether a new registration, amendment, transfer of eligible credit or cancellation process applies in the specific case.

 Bank accounts and loans

Banks may require updated incorporation documents, KYC, board or partner resolutions, fresh mandates and changes to account ownership. Existing loans, guarantees, security interests and working-capital facilities may require lender consent or revised documentation.

Never assume that a bank account or loan automatically moves to the new structure.
UDYAM Registration

Udyam/MSME registration

Review the Udyam registration details after restructuring. The correct action depends on the nature of the change and the portal’s current requirements. Do not assume that the old registration automatically reflects a new legal entity or ownership structure.

Licences, contracts and intellectual property

Review trade licences, professional or sector-specific approvals, lease agreements, vendor contracts, customer contracts, trademarks, domain names, software licences and insurance policies. Some may need amendments, assignments, new applications or counterparty consent.

The list should be prepared before the effective date, not after the business has already moved.

Can you change a company’s business activities without changing its structure?

Yes, changing business activities is different from changing the legal structure.

A private limited company may be able to expand into a new line of business without becoming an LLP or another type of entity. However, the proposed activity must be permitted by the company’s constitutional documents and comply with applicable law. The company may need to alter its memorandum, pass the required resolutions or obtain sector-specific approvals, depending on the circumstances.

For instance, a company incorporated for software services may want to add product sales. The founders should review the objects and applicable regulatory requirements rather than assume that a full legal-structure conversion is needed.

FilingPoint lists a separate Business Nature Change service in its service menu. Use the correct process for the change you actually need. 

Tax implications: what should founders review?

Tax consequences depend on the route, assets transferred, consideration, ownership and statutory conditions. There is no universal “tax-free conversion” rule covering every structure change.

Before proceeding, review:

  • Whether assets are transferred to a new entity or vest under a statutory conversion.
  • Whether the transaction involves a sale, slump sale, contribution or another transfer mechanism.
  • Whether the relevant conditions for any claimed tax relief are satisfied.
  • The treatment of inventory, receivables, fixed assets, goodwill and intellectual property.
  • GST consequences of the business or asset transfer.
  • Existing tax liabilities, tax credits and pending assessments.
  • Whether accumulated losses or other tax attributes can continue to be used.
  • Stamp duty and state-specific costs, where applicable.

The Income Tax Department’s published material on Section 47 identifies conditions relevant to certain successions of proprietary concerns and firms, as well as certain conversions of unlisted companies into LLPs. The conditions are specific and may include requirements relating to assets, liabilities, ownership, consideration, turnover or continuing ownership. 

Do not make a tax decision from a blog checklist alone. Ask a qualified tax professional to assess the exact transaction and applicable law as of the proposed effective date.

Documents to prepare before restructuring

The final document list will depend on the legal route, but the initial review often includes:

  • Certificate of incorporation, partnership deed or existing registration records.
  • Memorandum and Articles of Association, LLP agreement or other constitutional documents.
  • PAN, GST registration and Udyam details.
  • Latest financial statements and relevant tax returns.
  • List of assets, liabilities, receivables and stock.
  • Details of loans, charges, guarantees and security interests.
  • Partner or shareholder details and ownership percentages.
  • Board, shareholder or partner approvals, as applicable.
  • Major customer, supplier, employment and lease agreements.
  • Intellectual-property records and licences.
  • Details of pending litigation, notices, assessments or statutory defaults.
  • Proposed transfer or conversion documents and a transition plan.

These are review categories, not a universal mandatory list. Use the applicable MCA form instructions and professional advice to confirm what must be filed.

Common mistakes to avoid

Assuming all structures can be converted directly

They cannot. A sole proprietorship, partnership firm, LLP and company have different legal characteristics. First confirm whether a statutory route exists.

Treating incorporation as the end of the process

A new certificate does not resolve every contract, tax registration, bank mandate or licence. The transition must be managed across the business.

Ignoring tax until after the transfer

A transaction that appears simple from a registration perspective may have significant tax or stamp-duty consequences. Assess these before signing documents or transferring assets.

Overlooking creditor and lender rights

Loans, charges, guarantees and contractual restrictions can affect the available route. Obtain appropriate advice and consent where required.

Forgetting pending compliance

Outstanding filings and defaults may affect eligibility, timing or risk. Identify them early.

Assuming GST or Udyam details automatically update

Confirm the applicable steps for each registration. Keep the effective date, invoices, records and entity details consistent.

Choosing a structure only to reduce compliance

An LLP may be suitable for one business and unsuitable for another. Consider funding, ownership, liability, tax, contracts and long-term plans together.

Example: a growing consultancy considers incorporation

Suppose two founders operate a consultancy as a partnership. They begin working with larger corporate clients and plan to introduce an investor. They are considering a private limited company.

The right first step is not to submit a conversion form immediately. They should confirm how the partnership is registered, whether the proposed company route is available, what happens to the existing partnership’s assets and contracts, and whether all partners agree to the proposed arrangement.

They should also review the tax treatment of transferring the business, decide how ownership will be reflected in the new company, and identify which customer contracts, bank facilities, registrations and licences require action.

If the partnership cannot or should not use the intended statutory route, a new company and a documented business transfer may be considered. The precise approach must be selected after legal and tax review.

This example illustrates the central principle: the business goal determines the target structure, but the existing entity and applicable law determine the route.

A practical checklist before changing your business structure

Before proceeding, make sure you can answer the following:

  • What is the existing legal structure?
  • What target structure do we need, and why?
  • Is a statutory conversion route available?
  • What eligibility conditions and approvals apply?
  • Are statutory and tax filings up to date?
  • Have we reviewed assets, liabilities, contracts and creditor rights?
  • Have we obtained a tax assessment of the proposed transaction?
  • What will happen to PAN, GST, TDS, Udyam and other registrations?
  • Have we checked bank accounts, loans, licences and intellectual property?
  • Who will manage the transition and verify completion?

Frequently asked questions

1. Can I change my business structure after registration in India?

Often, yes. The available route depends on the existing structure and the target structure. Some changes have a statutory conversion route; others require forming a new entity and transferring the business.

2. Can a sole proprietorship be converted into a private limited company?

A proprietorship generally does not become a company through a direct change of registration type. The usual approach is to incorporate a new company and transfer the business through an appropriately documented arrangement.

3. Can an LLP become a private limited company?

A route may be available under Section 366 of the Companies Act, 2013 and the applicable rules. Eligibility, documents and the current MCA process should be verified before filing.

4. Can a private limited company become an LLP?

A statutory route exists under the LLP Act, subject to applicable eligibility and procedural requirements. Tax treatment must be assessed separately; not every transaction automatically qualifies for tax relief.

5. Can a partnership firm become an LLP?

A partnership firm may be eligible for conversion under the LLP Act if the prescribed conditions are met. The partners should verify the statutory requirements and the current filing process.

6. Will the business keep the same PAN after conversion?

Do not assume that it will. The answer depends on whether the legal person continues or a new entity is formed. Review the tax and registration consequences for the specific route.

7. What happens to GST registration when the structure changes?

The GST action depends on the transaction and the legal identity of the business after the change. Review registration, returns, tax liabilities, eligible credit and invoices before implementation.

8. Does conversion automatically transfer contracts and licences?

Not necessarily. Check each contract, licence and approval. Assignment, amendment, consent or a fresh application may be required.

9. Is changing business structure always tax-free?

No. Any relief depends on the specific legal provision and whether all applicable conditions are met. Obtain a transaction-specific tax assessment.

10. Should I change my business structure just to reduce compliance?

Not without comparing the full implications. Consider liability, ownership, fundraising, tax, contracts, administrative costs and the future direction of the business.

Conclusion

Changing your business structure after registration can be a sensible step when your business goals evolve. But it is not a one-size-fits-all process. A direct statutory conversion, registration as a company, or a new entity with a business transfer may be appropriate in different circumstances.

The safest approach is to identify your current legal structure, confirm the available legal route, assess tax and contractual implications, and prepare a coordinated plan for statutory filings and operational registrations.

Need help with company registration or compliance? FilingPoint can help you understand the applicable process for your business.

  • Phone: +91 72999 72500
  • Email: info@filingpoint.com
A business may obtain GST registration, start issuing invoices and build its customer base, only to discover that its registration has been suspended or cancelled by the tax department.

This can be worrying, especially when customers expect GST invoices, payments are pending, or the business needs to continue trading.

The first thing to understand is that GST registration cancellation is not the same as rejection of a new GST registration application. Rejection occurs when an application for registration is not approved. Cancellation affects a registration that already exists.

The solution is not always to submit another registration application. Depending on the reason, you may need to respond to a notice, correct a compliance issue, apply for revocation, or consider another legally appropriate route.

This guide explains how to assess a cancelled GST registration in India, what to check before taking action, and how to avoid repeating the same problem.

What does GST registration cancellation mean?

GST registration cancellation means that the existing registration has been cancelled under the applicable GST provisions. Cancellation may occur following an application by the taxpayer or action initiated by the proper officer.

The reasons and procedures differ according to the circumstances. For example, a business may apply for cancellation because it has discontinued operations or is no longer liable to be registered. The department may initiate cancellation proceedings where it believes a legal or compliance condition has been breached.

Section 29 of the Central Goods and Services Tax Act, 2017, addresses cancellation of registration. It also makes clear that cancellation does not automatically remove tax liabilities or other obligations relating to the period before cancellation. The applicable provisions and state GST law should be checked for the particular case.

Important: Do not assume that a cancelled GSTIN has erased past tax liabilities, pending returns or earlier non-compliance.

Why might the GST department cancel a registration?

The exact reason should be stated or explained in the relevant notice or order. Common issues that can lead to cancellation proceedings include:

  • Failure to file required GST returns for the applicable period.
  • The business not operating from its declared place of business.
  • Registration obtained through fraud, wilful misstatement or suppression of facts.
  • Certain invoicing or input tax credit violations.
  • Other breaches covered by the applicable GST Act and Rules.

These are examples, not a complete list of every possible ground. The legal basis and facts in the department’s order matter.

Why the reason matters

Two businesses may both see “cancelled” in their GST portal status but require different next steps.

A taxpayer whose registration was cancelled because returns were not filed may need to address outstanding returns and liabilities. A taxpayer whose case concerns the declared business premises may need to examine the premises records, actual business operations and the department’s findings.

The correct response should address the actual reason rather than simply submitting a generic explanation.

Suspension vs cancellation: check the exact status

Suspension and cancellation are not interchangeable terms.

A GST registration may be suspended while cancellation proceedings are pending or in circumstances provided by the rules. Cancellation is a formal outcome that changes the registration status.

Before taking action, check:

  • The status shown on the GST portal.
  • Whether a notice has been issued.
  • Whether a cancellation order has been passed.
  • The date the order was served.
  • The effective date of cancellation, if applicable.
  • Whether any reply or application is pending.

Do not rely only on an email notification, an old screenshot or what a third party has told you. Review the actual portal record and order.

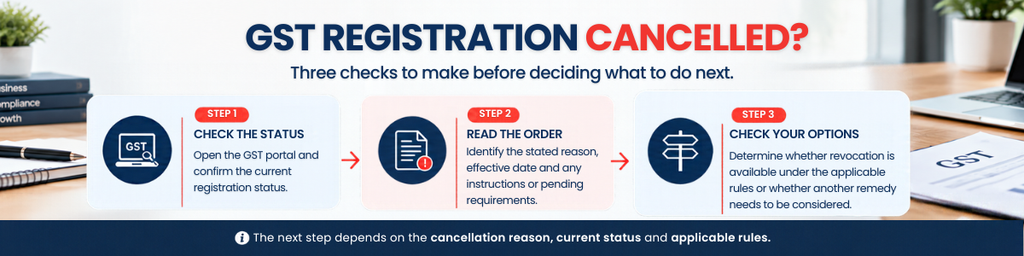
What should you do immediately after receiving a cancellation order?

Use this sequence to organise the case before filing anything.

Step 1: Download the notice and order

Keep copies of the show-cause notice, your reply, the cancellation order and related correspondence. Record the dates on which the documents were issued and served.

Read the reasons carefully. Note the rule or provision cited, the facts alleged and whether the order discusses unanswered notices, missing returns, address verification or another issue.

Step 3: Check your return-filing position

Review the returns due before cancellation, including any periods for which the portal shows outstanding filings. Compare portal information with your accounting records.

Step 4: Review tax and other dues

Check whether tax, interest, late fees or penalties are outstanding. Do not assume that filing a missing return alone resolves every liability.

Step 5: Check whether revocation is available

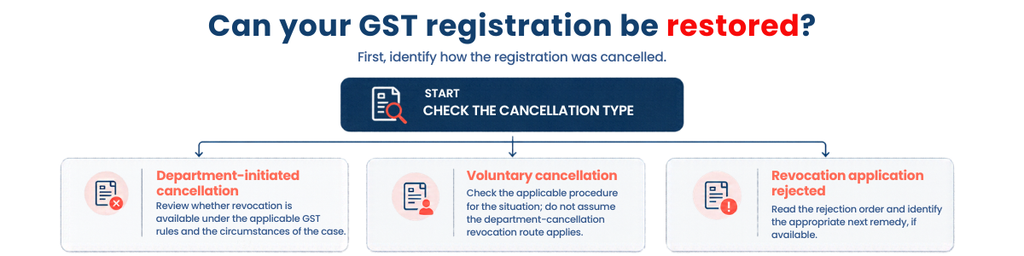
Revocation is generally relevant when the proper officer has cancelled registration on their own motion. It is not the same as requesting cancellation voluntarily.

If your case does not qualify for revocation, the next step may be different. Verify the legal route before submitting a form.

Step 6: Prepare an evidence-based response

Collect documents that directly address the reason for cancellation. For example, a premises-related case may need relevant address and business-operation evidence. A return-default case needs a return and payment review.

Step 7: Track the next deadline

Record the relevant date and any deadline in the notice, order or applicable rule. If the time limit is close or has passed, obtain advice promptly rather than waiting for another reminder.

What is revocation of GST registration cancellation?

Revocation means reversing a cancellation made by the proper officer, subject to the applicable law and procedure.

Section 30 of the CGST Act and Rule 23 of the CGST Rules deal with revocation of cancellation. The process is not available in every situation: the cancellation must be of the kind for which revocation is permitted.

A taxpayer who voluntarily applied to cancel their GST registration should not assume that the same revocation procedure automatically applies. First establish how the cancellation occurred and what order was passed.

Is revocation automatic?

No. An application must meet the applicable conditions and be considered by the proper officer. Filing an application does not itself prove that the registration has been restored.

The taxpayer should monitor the application and any notice or clarification request issued during the process.

What is Form GST REG-21 used for?

Form GST REG-21 is used for an application to revoke cancellation of GST registration where the applicable rules permit it.

Before filing, verify that:

  • The cancellation was initiated by the proper officer.
  • The case qualifies for revocation.
  • Any required returns have been filed.
  • Tax and related amounts required under the rules have been paid.
  • The explanation and supporting evidence address the cancellation grounds.
  • The application is within the applicable time limit, or a permitted extension route is available.

The current rule text and the portal’s live workflow should be checked before submission because procedures and time limits may change.

GST Registration Chennai

What if GST registration was cancelled because returns were not filed?

Non-filing requires careful attention because an application for revocation may not be considered until the relevant return defaults and associated dues have been addressed as required by the rules.

Start by preparing a period-wise list of returns that remain pending. Check the return type, tax period, filing status and any tax, interest, penalty or late fee applicable to the case.

Then reconcile the return information with sales, purchase, bank and accounting records. Filing returns without checking the underlying data can create additional inconsistencies.

A practical checklist

  • Identify all pending returns and periods.
  • Reconcile outward supplies and tax reported.
  • Check eligible input tax credit against supporting records and applicable conditions.
  • Calculate outstanding liabilities using current information.
  • File the returns required for the case.
  • Pay the amounts legally due.
  • Keep acknowledgements and payment records.
  • Review the cancellation order and the current revocation requirements before applying.

Do not assume that clearing one return will automatically restore registration. Follow the required procedure and wait for the relevant order or status update.

What if the deadline for revocation has passed?

Do not assume that the only option is to apply for a new GST registration.

The applicable time limit and any permitted extension must be checked against the current version of Rule 23, relevant notifications and the dates in your case. The current rule text provides for an initial period and a possible extension in qualifying circumstances, subject to the conditions and authority specified in the rule.

This is an area where old online articles can be misleading: earlier versions of the rules used different time limits.

If the deadline appears to have passed:

  1. Confirm the date on which the cancellation order was served.
  2. Check the rule and amendments applicable to your case.
  3. Determine whether a permitted extension or other remedy remains available.
  4. Prepare evidence explaining the delay, where relevant.
  5. Obtain professional advice if the registration is essential to ongoing operations.

Never rely on a generic statement such as “you always have 30 days” or “you can apply at any time.” The applicable law and case facts control.

What if the revocation application is rejected?

A rejected revocation application should be reviewed carefully before taking another step.

Read the rejection order and identify whether the issue relates to eligibility, outstanding returns, payment, missing evidence, an unanswered notice or the time limit.

Do not repeatedly submit the same application without addressing the reason for rejection.

Depending on the facts and applicable law, the next step may involve responding to a notice, reviewing whether an appeal or other remedy is available, or correcting a procedural issue where permitted. The right route depends on the order and the statutory framework.

Keep copies of the application, acknowledgement, notices, replies and rejection order. These documents are important for understanding the decision and assessing available options.

Can Your GST Registration be Restored

Can you continue business after GST registration is cancelled?

A business should not assume it can continue treating itself as a registered taxpayer after cancellation.

The consequences depend on the effective date, the nature of supplies, the applicable provisions and whether a later order restores the registration. A cancelled registration can affect invoicing, tax collection, input tax credit and dealings with customers.

At the same time, cancellation does not necessarily mean that every business activity must cease permanently. The business should obtain advice on what activities may lawfully continue, what tax obligations remain and whether registration is required for future supplies.

Do not issue invoices that represent the business as currently GST-registered if that status is no longer valid. Check the law and the actual registration status before making tax representations to customers.

What happens to earlier tax liabilities and records?

Cancellation does not automatically wipe out obligations relating to earlier periods. Section 29(3) addresses the continuation of liability for tax and other dues and obligations for the period before cancellation.

A business should retain its invoices, books, return records, payment receipts, bank records, purchase documents and correspondence with the department.

If registration is restored, reconcile the period covered by the cancellation and the restoration order. Check which returns or other actions remain necessary and confirm how the portal reflects the status.

A business should not assume that restoration alone fixes every historical issue.

Common mistakes to avoid

Mistake 1: Confusing cancellation with application rejection

They are different procedures. A business that already had a GSTIN should begin with its cancellation order and status.

Mistake 2: Filing without checking the order

The response should address the actual cancellation grounds.

Mistake 3: Ignoring pending returns

Where return defaults are involved, required returns and dues can be central to the revocation process.

Mistake 4: Relying on outdated time limits

Check the current rule and applicable amendments, not an old blog post.

Mistake 5: Assuming revocation is available after every cancellation

The route depends on how cancellation occurred and the applicable provisions.

Mistake 6: Ignoring earlier tax obligations

Cancellation does not erase every liability relating to the pre-cancellation period.

Mistake 7: Treating a submitted application as approval

Track the application and obtain confirmation of the actual outcome.

A practical decision guide

Your situationWhat to review first
You received a cancellation notice but no final orderNotice, reply deadline and evidence
Your GST registration is suspendedPortal status and pending proceedings
The officer has cancelled registrationOrder, effective date and revocation eligibility
Cancellation relates to missing returnsPending returns, tax and related dues
You applied for cancellation voluntarilyCorrect route for your circumstances; do not assume REG-21 applies
Your revocation application was rejectedRejection order and any available remedy
The revocation deadline may have passedCurrent Rule 23 and possible extension provisions
Registration has been restoredOrder, portal status, returns and remaining obligations

This is a starting guide, not a substitute for reviewing the actual order.

How to reduce the risk of future cancellation

A business can reduce avoidable compliance problems by establishing a reliable routine.

  • Maintain a calendar for applicable GST return due dates.
  • Reconcile books and GST returns regularly.
  • Keep the declared principal place of business and supporting records accurate.
  • Respond promptly to notices and verification requests.
  • Monitor GST portal messages and application status.
  • Retain acknowledgements, invoices and payment records.
  • Review changes in the business, ownership, premises or registration details.
  • Seek help when a notice is unclear or a deadline is approaching.

The objective is not just to restore a GSTIN after cancellation. It is to address the underlying issue so the business can manage its tax obligations more consistently.

Frequently asked questions

1. Can I restore a GST registration cancelled by the department?

Possibly. Revocation may be available when the proper officer cancelled the registration on their own motion and the taxpayer satisfies the applicable conditions. Check the cancellation order and current rules.

2. Which form is used to apply for revocation?

Form GST REG-21 is used for an application for revocation of cancellation where the applicable rules permit it.

3. Can I apply for revocation if I have not filed GST returns?

If cancellation occurred because of return non-filing, the relevant returns and amounts due generally need to be addressed as required by the rules before an application can be filed.

4. Is a cancelled GST registration the same as a rejected GST application?

No. Rejection concerns an application for new registration. Cancellation affects an existing registration.

5. Can I apply for revocation after the deadline?

Possibly, depending on the current rules, any permitted extension and the circumstances. Check the current law and the order’s service date promptly.

6. What if the officer rejects my revocation application?

Review the rejection order and identify the reason. Depending on the facts, an appropriate response or other remedy may be available under the applicable law.

7. Does GST cancellation remove earlier tax liabilities?

No. Cancellation does not automatically remove liabilities or obligations relating to the pre-cancellation period.

8. Should I apply for a new GST registration instead?

Do not assume that a fresh application is the right solution. First determine whether revocation or another route is available and whether a new application would be legally appropriate.

Conclusion

A cancelled GST registration needs a prompt, evidence-based response. Start with the cancellation order, confirm the portal status, identify the reason, review pending returns and liabilities, and determine whether revocation is available.

The correct route depends on the way the registration was cancelled, the applicable deadlines and the taxpayer’s compliance position. Avoid relying on outdated online guidance or submitting forms without understanding the order.

Need help understanding your GST registration status or compliance requirements? Filing Point can help you review the issue and identify the appropriate next steps.

📞 +91 72999 72500
📧 enquiry@filingpoint.com

Tiruppur is one of Tamil Nadu’s most important textile and knitwear business clusters. For an entrepreneur, however, starting a textile business involves much more than setting up a production unit or finding buyers.

Depending on the nature and scale of the business, you may need to choose an appropriate business structure, complete tax registrations, obtain Udyam registration, protect your brand through trademark registration, and consider additional approvals for manufacturing, processing, employment, environmental compliance or exports.

The right registration strategy depends on what you manufacture or sell, how you operate, your business structure, turnover, location, workforce, whether you export, and the processes carried out at your premises.

This guide explains the major registrations and compliance considerations for entrepreneurs planning to start a textile, garment, apparel, clothing, knitting, processing or textile-related business in Tiruppur.

Quick Answer: A textile business in Tiruppur may require a combination of business/entity registration, GST registration where applicable, Udyam/MSME registration, trademark protection and, for exporters, an Importer Exporter Code (IEC). Manufacturing and textile-processing units may also need additional approvals depending on their activities, premises, machinery, workforce and environmental impact. There is no single registration that covers every textile business.

Why Tiruppur Is an Important Location for Textile Businesses

Tiruppur has a deep textile ecosystem covering knitting, garment manufacturing, processing and apparel-related activities.

The Tamil Nadu government’s textile information identifies Tiruppur as a major knitting and garmenting cluster and highlights its importance to India’s knitwear sector. The state also has a significant network of textile-processing infrastructure, including Common Effluent Treatment Plants in Tiruppur.

The business ecosystem can support different types of entrepreneurs, including:

  • Garment manufacturers
  • Knitwear manufacturers
  • Textile traders
  • Apparel wholesalers
  • Clothing brands
  • Fashion startups
  • Private-label manufacturers
  • Exporters
  • Textile job-work units
  • Knitting units
  • Dyeing and processing units
  • Printing and embroidery businesses
  • Textile accessory suppliers
  • D2C clothing brands
  • Online apparel businesses

The important point is that these businesses do not necessarily have the same registration requirements.

For example, a clothing brand selling finished garments may have a very different compliance profile from a dyeing or processing unit.

What Registrations Does a Textile Business in Tiruppur Need?

There is no universal registration checklist for every textile business.

Your requirements should be mapped according to your business model.

A typical textile entrepreneur may need to consider:

Registration / RequirementWhy It Matters
Business structure/entity registrationEstablishes the legal form of the business
PANRequired for tax and financial identification
GST registrationApplicable based on GST law and business circumstances
Udyam/MSME registrationEstablishes MSME classification where eligible
Trademark registrationProtects the business/brand identity
IECImportant for businesses undertaking import/export activities
Local/business-related approvalsMay apply depending on premises and activity
Factory/manufacturing approvalsMay apply depending on the nature and scale of manufacturing
Pollution/environmental approvalsParticularly relevant to textile processing activities
Labour-related registrations/complianceDepends on workforce and applicable laws
Industry-specific certificationsMay be relevant to particular products, buyers or markets

The exact combination should be determined before the business starts operations, rather than treating every registration as interchangeable.

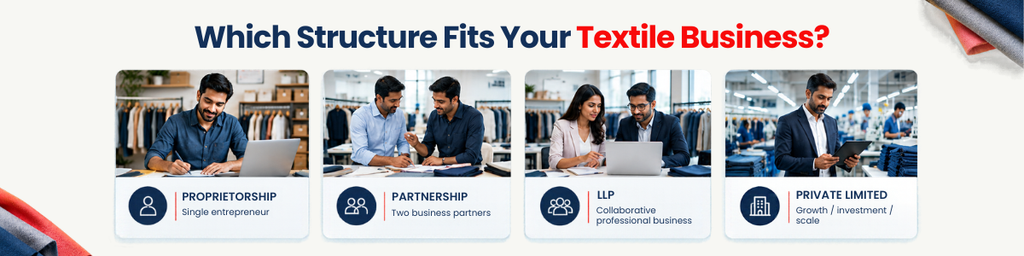
1. Choose the Right Business Structure

One of the first decisions is determining how the textile business will be legally structured.

Common options include:

Sole Proprietorship

A proprietorship can be suitable for a small business operated by one individual, particularly where the entrepreneur wants a relatively simple structure.

It can work for certain:

  • Small textile traders
  • Boutique businesses
  • Small clothing sellers
  • Independent apparel businesses
  • Home-based businesses

However, the owner and business are not separate legal persons in the same way as a company.

Partnership Firm

A partnership may be considered when two or more individuals want to operate a business together under a partnership arrangement.

It can be relevant for:

  • Family-owned textile businesses
  • Small garment trading businesses
  • Manufacturing businesses with multiple partners
  • Traditional textile enterprises

A properly drafted partnership agreement should clearly establish responsibilities, capital contributions, profit-sharing arrangements and other important terms.

Limited Liability Partnership

An LLP can be considered when entrepreneurs want a separate legal structure combined with limited liability characteristics and a partnership-style management model.

It may be relevant for:

  • Textile trading businesses
  • Apparel sourcing businesses
  • Textile consulting businesses
  • Businesses with multiple founders
  • Certain growing manufacturing or export ventures

Private Limited Company

A Private Limited Company may be appropriate where the founders expect a more structured corporate setup and future growth.

It can be particularly relevant to:

  • Growing garment manufacturers
  • Apparel brands
  • Textile exporters
  • D2C clothing companies
  • Businesses seeking external investment
  • Businesses planning to build a larger corporate operation

FilingPoint already has a dedicated article on Pvt Ltd Company Registration in Tiruppur. Therefore, this article should not duplicate the incorporation process; instead, it places Pvt Ltd registration within the broader textile-business compliance framework.

How Should You Choose?

Consider:

  • Number of owners
  • Capital requirements
  • Expected growth
  • Liability considerations
  • Funding plans
  • Export plans
  • Management structure
  • Compliance capacity
  • Long-term ownership plans

There is no universally “best” structure for every textile entrepreneur.

2. GST Registration for a Textile Business

GST is an important consideration for textile manufacturers, traders, wholesalers and clothing businesses.

GST registration requirements depend on factors such as turnover, nature of supply and circumstances that can trigger registration.

For example, GST law contains threshold exemptions and compulsory-registration provisions, so entrepreneurs should not rely on a simple turnover number without checking the current rules applicable to their particular business.

CBIC’s GST material explains the registration framework and also notes that certain circumstances can affect the availability of threshold exemption.

Why GST Matters to Textile Businesses

A registered textile business may need GST compliance for:

  • Tax invoices
  • Input tax credit
  • B2B transactions
  • Interstate supplies
  • Certain e-commerce transactions
  • Export-related transactions
  • GST returns
  • Business-to-business procurement

A textile manufacturer should also correctly identify the applicable HSN classification for the goods being supplied. The GST portal’s registration guidance requires businesses dealing in goods to provide relevant HSN information.

Example

Suppose a Tiruppur business manufactures cotton T-shirts and sells them to retailers in Tamil Nadu and customers in other states.

The entrepreneur should assess:

  1. Whether GST registration is required.
  2. Correct classification of the products.
  3. Applicable GST rate.
  4. Invoice requirements.
  5. Input tax credit eligibility.
  6. Interstate supply requirements.
  7. Return filing obligations.

The answer should be based on the actual business model, not simply the fact that the business is located in Tiruppur.

3. Udyam Registration for Textile and Garment Businesses

Many textile businesses in Tiruppur may fall within the MSME ecosystem.

Udyam Registration is the government’s official MSME registration system.

The official Udyam portal states that registration is free, online, paperless and based on self-declaration, and that an enterprise receives a permanent Udyam Registration Number and an online certificate.

Current MSME Classification

Under the current classification shown on the official Udyam portal:

MSME CategoryInvestment LimitTurnover Limit
MicroUp to ₹2.5 croreUp to ₹10 crore
SmallUp to ₹25 croreUp to ₹100 crore
MediumUp to ₹125 croreUp to ₹500 crore

These criteria are based on the current Udyam framework and should be checked against the latest government notifications when publishing or updating this article.

Why Textile Businesses Consider Udyam Registration

Udyam registration can be useful for eligible businesses because MSME status can be relevant to:

  • Government schemes
  • Institutional support
  • Certain procurement opportunities
  • Business financing
  • MSME-related programmes
  • Formal recognition as an MSME

However, Udyam registration does not replace company registration or GST registration.

These are different regulatory systems serving different purposes.

Company Registration in Chennai

4. Trademark Registration for a Textile or Clothing Brand

If you are building a clothing or textile brand, protecting the brand name should be considered early.

For example, imagine a Tiruppur manufacturer launches its own clothing brand.

The entrepreneur may invest heavily in:

  • Brand name
  • Logo
  • Packaging
  • Labels
  • Website
  • Social media
  • Retail distribution
  • Advertising

Without a proper trademark strategy, the entrepreneur may face brand-protection issues later.

Trademark registration is therefore different from company registration.

Company registration establishes an entity. Trademark registration protects a brand identifier.

Which Trademark Classes Are Relevant to Textile Businesses?

Trademark classification depends on what you sell or provide.

For textile and apparel businesses, the appropriate Nice Classification class or classes should be determined based on the actual goods/services being protected.

The Indian Trade Marks system uses the Nice Classification framework.

A clothing brand may need to examine classes relevant to its:

  • Garments
  • Footwear
  • Headwear
  • Textile goods
  • Retail services
  • Online retail services
  • Manufacturing-related services
  • Other branded products

The correct class should be selected based on the actual business and the goods/services for which protection is sought.

Current Trademark Filing Fees

As of the current IP India fee schedule, the official e-filing fee for a TM-A application is:

  • ₹4,500 per class/per mark for an individual, startup or small enterprise.
  • ₹9,000 per class/per mark for other applicants.

These are official government filing fees; professional service charges, if any, are separate.

Because trademark fees and rules can change, the latest IP India fee schedule should be checked before publication or filing.

5. IEC for Textile Export Businesses

Tiruppur has a strong export-oriented apparel ecosystem, so many entrepreneurs may eventually consider international markets.

If your textile business plans to undertake import or export activities, Importer Exporter Code (IEC) becomes an important consideration.

DGFT’s Foreign Trade Policy states that an IEC is a 10-character alphanumeric number allotted to an entity and is mandatory for undertaking import/export activities unless specifically exempted.

This can be particularly relevant for:

  • Garment exporters
  • Knitwear exporters
  • Textile manufacturers exporting directly
  • Apparel brands selling internationally
  • Textile sourcing businesses
  • Businesses importing textile machinery or materials

Export Business Planning Should Start Early

An entrepreneur planning exports should consider more than IEC.

The business may also need to understand:

  • GST treatment of exports
  • Export documentation
  • Invoicing
  • Shipping documentation
  • Buyer requirements
  • Product specifications
  • Country-specific requirements
  • Customs procedures
  • Payment mechanisms
  • Foreign exchange considerations
  • Product certifications where required

GST materials describe exports as zero-rated supplies under the GST framework, subject to the applicable conditions and procedures.

6. Textile Manufacturing Can Require Additional Approvals

This is one of the most important distinctions for textile entrepreneurs.

A clothing brand and a dyeing or processing factory should not be treated as having identical compliance requirements.

For example:

Apparel Trading Business

A business that purchases finished garments and resells them may have a relatively different compliance profile.

Garment Manufacturing Unit

A manufacturing facility may need to consider additional requirements relating to:

  • Premises
  • Machinery
  • Workers
  • Factory-related compliance
  • Fire and safety
  • Local approvals
  • Labour compliance

Dyeing or Processing Unit

Textile processing can involve environmental considerations, wastewater and effluent management.

Tamil Nadu’s Handlooms and Textiles Department specifically identifies Tiruppur as a hub for textile processing and knitting and notes the presence of Common Effluent Treatment Plants in the cluster.

Therefore, entrepreneurs planning:

  • Dyeing
  • Bleaching
  • Printing
  • Washing
  • Processing
  • Effluent-generating activities

should identify the applicable environmental and operational approvals before setting up the facility.

This is an area where a generic “company registration checklist” is not sufficient.

7. What Documents Are Commonly Needed?

The exact documents depend on the structure and registration.

A textile entrepreneur may commonly need information relating to:

Promoters / Owners

  • PAN
  • Aadhaar or other identity information
  • Address details
  • Photographs/contact information where applicable

Business

  • Proposed business name
  • Business activity
  • Ownership details
  • Capital/contribution details
  • Partnership or incorporation documents where applicable

Business Premises

  • Address proof
  • Ownership document or rental/lease documentation
  • Utility bill or other acceptable premises evidence, depending on the registration

Tax and Banking

  • PAN
  • Bank account information where applicable
  • GST-related information where applicable

Trademark

Trademark applications require information about the applicant, mark and relevant goods/services, along with the applicable filing details.

Export

An exporter will need the relevant entity and tax information required for IEC and related export procedures.

The important principle is:

Do not collect documents randomly. First determine which registrations apply to your particular textile business.

8. Textile Business Registration: Manufacturer vs Trader vs Brand

A major mistake is assuming every textile business needs the same registration package.

Consider these three examples.

Example 1: Tiruppur Garment Manufacturer

The business manufactures T-shirts and exports them.

Potential areas to evaluate:

  • Business structure
  • GST
  • Udyam
  • Trademark if operating a brand
  • IEC
  • Manufacturing/factory requirements
  • Environmental requirements where applicable
  • Labour compliance

Example 2: Textile Trader

The business purchases garments from manufacturers and sells them to retailers.

The focus may instead be:

  • Business structure
  • GST applicability
  • Udyam eligibility
  • Trademark if operating a brand
  • Trading-related compliance

Example 3: D2C Clothing Brand

The entrepreneur designs products, outsources manufacturing to Tiruppur factories and sells through a website.

The entrepreneur may not operate a textile factory at all.

The focus may include:

  • Business structure
  • GST applicability
  • Udyam eligibility
  • Trademark
  • E-commerce/business compliance
  • Vendor agreements
  • Product and consumer-related requirements
  • Export/IEC if selling internationally

These three businesses operate in the same textile ecosystem but have different compliance requirements.

9. Should a Small Textile Business Register as an MSME?

If the enterprise qualifies under the current MSME criteria, Udyam registration can be considered.

The official portal allows eligible enterprises to register online through a free, paperless process and provides a permanent registration number.

Importantly, Udyam registration is not limited to one type of textile activity.

An enterprise can specify multiple activities, including manufacturing or services, within the Udyam framework.

This can be useful for textile businesses that combine activities.

For example:

Manufacturing + wholesale + branded apparel

may involve multiple business activities that need to be correctly reflected in the business’s registrations and records.

10. When Should You Register Your Trademark?

Ideally, trademark planning should happen before substantial investment in the brand.

Before launching a clothing brand, consider:

Step 1: Choose the brand name

Do not assume that a domain name or social-media username means the brand is legally protected.

Step 2: Search existing trademarks

Check whether similar marks already exist.

Step 3: Identify relevant classes

Determine which goods and/or services your brand needs protection for.

Step 4: File the application

The appropriate trademark application can then be submitted through IP India’s system.

Step 5: Monitor the application

The trademark process can involve examination, responses and potentially opposition proceedings.

The official IP India process and forms should be checked for the current requirements.

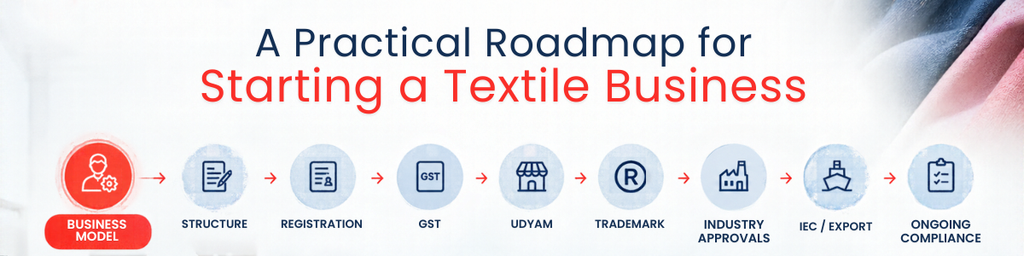
11. A Practical Registration Roadmap for a Tiruppur Textile Startup

Instead of treating registrations as unrelated tasks, entrepreneurs can approach the process in stages.

Stage 1: Define the Business

Decide:

  • What products will you sell?
  • Will you manufacture or outsource?
  • Will you sell B2B or B2C?
  • Will you export?
  • Will you operate a brand?
  • How many owners are involved?

Stage 2: Select the Business Structure

Compare:

  • Proprietorship
  • Partnership
  • LLP
  • Private Limited Company

The choice should reflect ownership, growth and operational requirements.

Stage 3: Establish the Business

Complete the relevant incorporation or registration process.

Obtain the necessary PAN and other foundational business information.

Stage 4: Evaluate GST

Determine whether GST registration applies based on:

  • Turnover
  • Nature of supply
  • Interstate transactions
  • Applicable compulsory-registration provisions
  • Business model

Do not rely on outdated threshold information.

Stage 5: Obtain Udyam Registration Where Eligible

If the business qualifies as an MSME, evaluate Udyam registration.

The official portal currently states that Udyam registration is free and does not require payment to private intermediaries for the government registration itself.

Stage 6: Protect the Brand

If you are building a clothing or textile brand:

  • Search the brand
  • Select appropriate classes
  • File the trademark application
  • Monitor the application

Stage 7: Evaluate Industry-Specific Requirements

For manufacturing, processing and other physical operations, check:

  • Factory-related requirements
  • Local approvals
  • Fire/safety requirements
  • Labour compliance
  • Environmental requirements
  • Electricity/power-related requirements
  • Waste/effluent requirements

The exact requirements depend on the activity and premises.

Stage 8: Prepare for Exports

If exporting:

  • Evaluate IEC
  • Review GST export procedures
  • Understand customs documentation
  • Identify destination-market requirements
  • Review buyer-specific certifications
  • Establish appropriate export documentation processes

12. Common Mistakes Textile Entrepreneurs Make

Mistake 1: Thinking Company Registration Is Enough

Registering a company does not automatically complete GST, MSME, trademark, export or industry-specific compliance.

Each serves a different purpose.

Mistake 2: Choosing a Business Structure Without Considering Growth

A structure suitable for a small family trading operation may not necessarily be the best fit for a business planning external investment or rapid expansion.

Mistake 3: Treating Udyam and GST as the Same Registration

They are not.

GST = indirect tax registration/compliance framework.

Udyam = MSME registration/classification framework.

Mistake 4: Delaying Trademark Registration

Building a clothing brand first and thinking about trademark protection later can create unnecessary risk.

Mistake 5: Assuming Every Textile Business Has the Same Approvals

A garment trader, clothing brand, garment factory and dyeing unit can have substantially different compliance requirements.

Mistake 6: Ignoring Export Requirements

If international sales are part of the business plan, export-related requirements should be considered before accepting overseas orders.

Mistake 7: Using Outdated GST or MSME Information

GST thresholds, procedures and government schemes can change.

The same applies to MSME classifications and regulatory requirements.

Always verify current rules before filing.

Textile Business Registration Checklist for Tiruppur

Use this as a starting checklist:

Business Setup

  • Decide business structure
  • Select business name
  • Establish business address
  • Prepare promoter/partner/director information
  • Complete relevant business registration

Tax

  • Obtain PAN
  • Evaluate GST applicability
  • Identify relevant HSN classifications
  • Establish invoicing system
  • Understand GST return requirements

MSME

  • Check MSME eligibility
  • Complete Udyam registration if applicable
  • Keep Udyam information updated

Brand

  • Search proposed brand name
  • Identify relevant trademark classes
  • File trademark application where appropriate
  • Monitor trademark status

Manufacturing

  • Check premises requirements
  • Check factory-related requirements
  • Evaluate labour requirements
  • Evaluate fire/safety requirements
  • Check environmental approvals where applicable

Export

  • Evaluate IEC requirement
  • Understand export GST treatment
  • Prepare export documentation
  • Review destination-market requirements

Frequently Asked Questions

1. What registrations are required to start a textile business in Tiruppur?

There is no single checklist for every business. Depending on the model, you may need business/entity registration, GST registration where applicable, Udyam registration, trademark registration and IEC for import/export activities. Manufacturing and processing businesses may have additional requirements.

2. Is GST registration mandatory for every textile business in Tiruppur?

Not necessarily. GST registration depends on the applicable GST rules, turnover, nature of supply and circumstances that may trigger compulsory registration. The current GST framework should be checked before deciding.

3. Is Udyam registration useful for a textile business?

Eligible textile and garment businesses can consider Udyam registration. The official portal states that Udyam registration is free, paperless and based on self-declaration.

4. Can a textile business have both GST and Udyam registration?

Yes. They serve different purposes. GST relates to the GST tax framework, while Udyam establishes MSME registration/classification.

5. Do I need a trademark for my clothing brand?

Trademark registration is not the same as company registration, but it can be an important part of protecting a clothing or textile brand.

6. What trademark class should a clothing business choose?

The appropriate class depends on the actual goods and services offered by the business. Textile and apparel entrepreneurs should identify the relevant Nice Classification categories before filing.

7. How much does trademark registration cost?

IP India’s current e-filing fee for a TM-A application is ₹4,500 per class/per mark for an individual, startup or small enterprise and ₹9,000 for other applicants. Professional fees, if applicable, are separate.

8. Do textile exporters in Tiruppur need IEC?

Businesses undertaking import/export activities generally need an Importer Exporter Code unless a specific exemption applies. DGFT describes IEC as mandatory for import/export activities, subject to applicable exemptions.

9. Is company registration compulsory for every textile business?

No. The appropriate business structure depends on how the entrepreneur intends to operate. A textile business may operate through different legal structures depending on its circumstances.

10. Does a garment manufacturing business need additional approvals?

Potentially, yes. Manufacturing premises, workforce, machinery, fire/safety, environmental impact and other factors can create additional compliance requirements.

11. Is a clothing brand the same as a garment manufacturing company?

No. A clothing brand may outsource manufacturing to a third-party factory. Its compliance requirements can therefore differ from those of a business operating its own manufacturing facility.

12. Can a Tiruppur textile business sell internationally?

Yes, textile and apparel businesses can target international markets, but export-related requirements, documentation, taxation and destination-market rules need to be evaluated.

13. Can an MSME have multiple business activities under Udyam?

The official Udyam portal states that multiple activities, including manufacturing or services, can be specified or added under one Udyam Registration, subject to the applicable framework.

14. Should I register my business or trademark first?

Business formation and trademark protection are separate processes. Entrepreneurs planning a brand should consider trademark searches and protection early rather than waiting until the brand has significant market exposure.

15. What is the first step for starting a textile business in Tiruppur?

Start by defining your business model: manufacturer, trader, exporter, clothing brand, D2C business, job-work unit or processor. Once that is clear, you can identify the appropriate business structure and registrations.

Final Takeaway

Starting a textile business in Tiruppur is not simply a matter of registering a company and beginning production.

Your compliance requirements should be built around the actual nature of your business.

A typical roadmap may look like:

Business Model → Business Structure → Business Registration → GST Assessment → Udyam/MSME → Trademark → Industry-Specific Approvals → IEC/Export Compliance → Ongoing Compliance

The requirements can vary significantly between a garment manufacturer, textile trader, clothing brand, exporter and textile-processing unit.

Tiruppur’s textile ecosystem creates significant opportunities, but entrepreneurs should establish the correct legal and compliance foundation before investing heavily in manufacturing, branding or international sales. Tamil Nadu’s official textile ecosystem specifically recognizes Tiruppur’s importance in knitting, garmenting and textile processing.

If you are planning to start a textile, garment, apparel, clothing brand, manufacturing or export business in Tiruppur, getting the registration roadmap right at the beginning can make future expansion and compliance much easier.

Planning to start a textile business in Tiruppur? FilingPoint can help you evaluate the appropriate business structure, registration requirements, GST, MSME/Udyam, trademark and related business compliance based on your specific business model.

Important Note

Registration and compliance requirements can vary according to the business structure, turnover, products, premises, manufacturing activity, workforce, interstate transactions and export activity. Government rules and fees can change. Entrepreneurs should verify the latest requirements with the relevant government authority before filing.

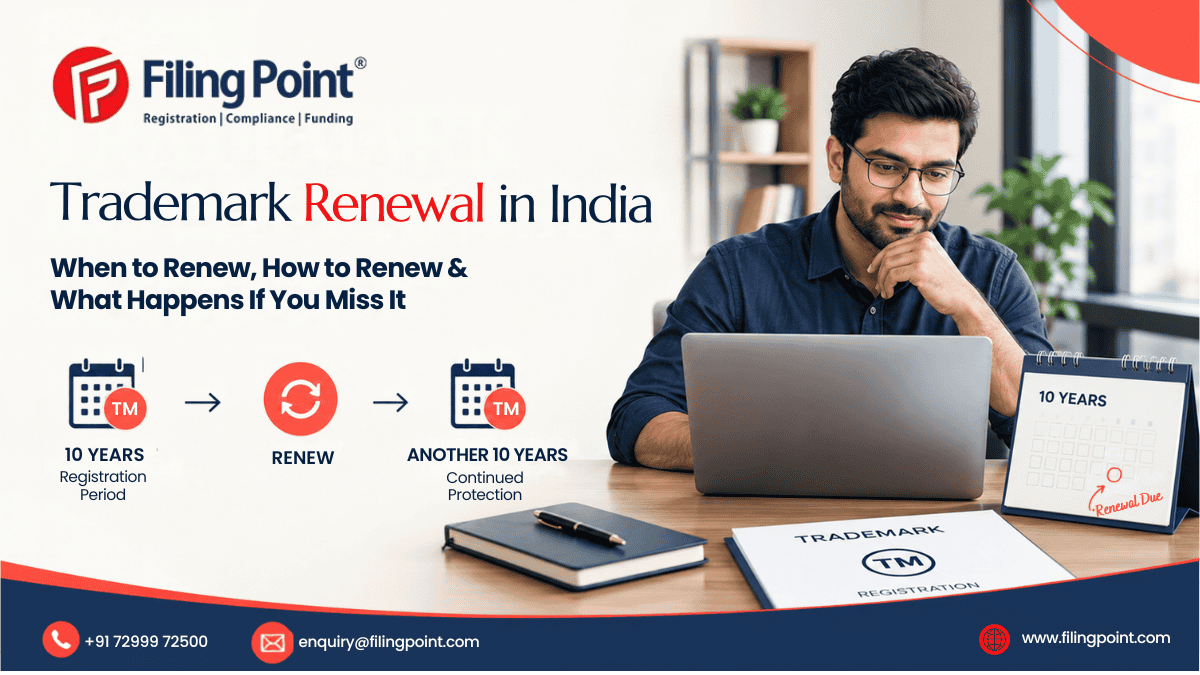
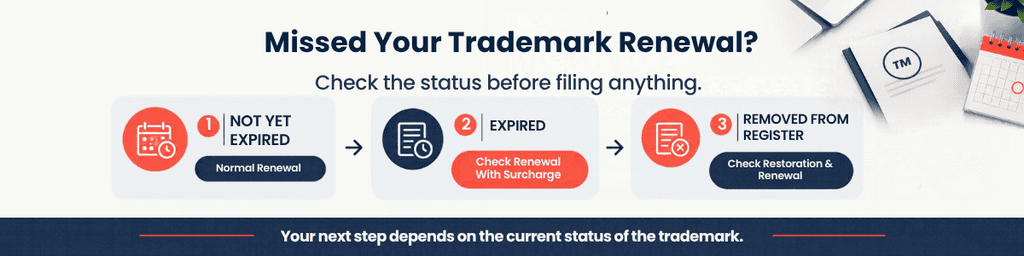
Trademark registration in India is generally valid for 10 years and can be renewed every 10 years. The renewal application is filed using Form TM-R with the prescribed fee. Under the Trade Marks Rules, an application for renewal may be made up to one year before the expiry of the existing registration.

If renewal is not completed by the expiry date, the owner may still have a statutory window to apply for renewal with surcharge. If the trademark has already been removed from the Register for non-payment, restoration may be possible within the prescribed period, subject to the applicable requirements.

What Is Trademark Renewal?

Trademark renewal is the process of extending the validity of an existing registered trademark.

When a trademark is registered in India, the registration is granted for a period of 10 years. The registration can then be renewed from time to time for additional periods of 10 years.

For example, if a trademark registration is due to expire in June 2027, the proprietor should not wait until the final days to start the renewal process. The renewal can be planned in advance, allowing time to verify the registration details and complete the required filing.

Trademark renewal is different from applying for a new trademark registration.

If you already have a registered mark that you want to continue protecting, the relevant process is renewal. A fresh application may have different implications and does not simply substitute for maintaining an existing registration.

How Long Is a Trademark Registration Valid in India?

A trademark registration is generally valid for 10 years.

Section 25 of the Trade Marks Act, 1999 provides that registration is for a period of 10 years and may be renewed from time to time. Each renewal extends the registration for another 10-year period.

There is therefore no fixed lifetime limit on the number of times a trademark can be renewed.

A business may continue renewing its registered trademark as long as it remains eligible and the applicable requirements are satisfied.

Example

Suppose a business has a registered trademark with an expiry date in August 2027.

The owner can plan the renewal before August 2027 rather than waiting until the last moment.

If the renewal is completed correctly, the trademark can continue for another 10-year period.

This is why businesses should maintain a simple trademark renewal calendar for all their registered marks.

When Should You Renew a Trademark in India?

Under Rule 57 of the Trade Marks Rules, 2017, an application for renewal of trademark registration can be made not more than one year before the expiration of the last registration.

This gives trademark owners an opportunity to plan renewal well in advance.

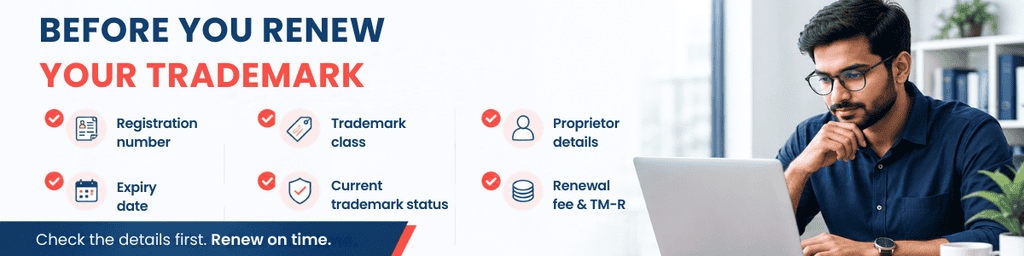
A practical approach is to review the trademark several months before its expiry date and check:

  • Trademark registration number
  • Registered proprietor’s name
  • Trademark class or classes
  • Expiry date
  • Current address and contact details
  • Whether the trademark is still being used
  • Whether ownership details have changed
  • Whether any related applications or proceedings are pending

Early review can help identify issues before the renewal filing is made.

Which Form Is Used for Trademark Renewal?

The prescribed form for renewal of trademark registration is Form TM-R.

IP India lists TM-R for renewal of trademark registration under Section 25. The current official fee schedule also specifies the renewal fee for each class.

The application should be prepared using the details of the registered trademark and filed through the applicable Trade Marks Registry process.

It is important to distinguish renewal from other trademark forms.

For example, if the proprietor’s details have changed because of an assignment or transfer, that may involve a separate procedure. Renewal should not be treated as a way to automatically correct every change in ownership or registration details.

What Is the Trademark Renewal Fee in India?

Trademark renewal fees are prescribed under the Trade Marks Rules and the official IP India fee schedule.

As currently listed by IP India, ordinary renewal of a trademark under Section 25 is charged per class. The current e-filing fee shown for ordinary renewal is ₹9,000 per class, while physical filing is listed at ₹10,000 per class.

Additional amounts apply where renewal is filed with surcharge or where restoration is involved.

Because government fees and filing procedures can change, businesses should check the latest IP India fee schedule before making payment rather than relying on an old fee quotation.

Check IP India Forms & Official Fees

Important: Fee depends on the situation

The amount payable may differ depending on whether the application is:

  • Normal renewal
  • Renewal after expiry with surcharge
  • Restoration and renewal after removal

The applicable fee is also relevant per class, so businesses with multiple registered classes should review each registration carefully.

What Happens If You Miss the Trademark Renewal Date?

Missing the renewal date does not necessarily mean that all options immediately disappear.

Section 25 of the Trade Marks Act provides a statutory mechanism for renewal after expiry with payment of the prescribed fee and surcharge within the specified period. The Registrar may remove the trademark from the Register if the applicable renewal conditions are not fulfilled, subject to the statutory protection available during the prescribed post-expiry period.

This is why a missed renewal should be addressed promptly.

The longer the matter remains unattended, the more complicated the position can become.

A trademark owner who discovers that a registration has expired should first verify:

  1. The exact expiry date.
  2. Whether the registration is still on the Register.
  3. Whether renewal can be filed with surcharge.
  4. Whether the mark has already been removed.
  5. Whether restoration provisions may apply.

Do not assume that an expired trademark and a removed trademark are exactly the same situation.

What Is Trademark Renewal With Surcharge?

If the ordinary renewal deadline has passed, the law provides a period in which renewal may be sought with the prescribed surcharge.

Section 25(3) provides that where the prescribed fee and surcharge are paid within six months from the expiration of the last registration, the Registrar shall renew the registration in accordance with the statutory provision.

IP India’s current fee schedule separately lists an application for renewal with surcharge and specifies the additional amount payable per class.

Therefore:

Normal renewal → prescribed renewal fee

Late renewal within the applicable period → renewal fee + prescribed surcharge

The exact amount should be checked against the current official fee schedule at the time of filing.

What Happens If the Trademark Has Already Been Removed?

A trademark that has been removed from the Register for failure to pay the renewal fee may still have a route to restoration.

Section 25(4) provides for restoration where the application is made after six months and within one year from the expiration of the last registration, subject to the Registrar being satisfied that restoration is appropriate and the prescribed fee is paid.

This is different from ordinary renewal.

The owner should therefore establish the current status of the trademark before deciding what filing to make.

In simple terms

SituationPossible route
Renewal period not yet expiredNormal renewal
Registration expired but within statutory late-renewal periodRenewal with surcharge
Trademark removed from RegisterRestoration and renewal may be possible, subject to the law
Statutory restoration period has also passedFurther legal assessment may be required

This table is a simplified guide. The actual position should be checked against the current Register and applicable provisions.

What Is Trademark Restoration?

Trademark restoration is the process of seeking restoration of a trademark that has been removed from the Register because the renewal requirements were not completed.

It is not simply another name for late renewal.

The Trade Marks Act creates a separate mechanism for restoration after removal, while IP India’s fee schedule separately identifies an application for restoration and renewal.

This distinction matters because the appropriate filing depends on the current status of the trademark.

If a business discovers an old registered trademark that was allowed to lapse, it should first check the official trademark record instead of immediately filing a new application.

Does a Trademark Need to Be Used to Renew It?

Trademark renewal and trademark use are related to the broader protection of a mark, but renewal itself should not be understood as a substitute for actual trademark use.

The renewal provisions primarily deal with maintaining the registration by complying with the applicable renewal requirements and paying the prescribed fees.

At the same time, registered trademarks can be subject to other legal issues, including proceedings concerning non-use in appropriate circumstances.

Therefore, businesses should not think of renewal as simply paying a fee and ignoring the trademark thereafter.

If the business has stopped using the mark, changed its brand, sold the business or substantially changed its products or services, it is sensible to review the trademark portfolio before renewal.

Trademark Registration Chennai

Should You Renew a Trademark If Your Business Has Changed?

Not necessarily without first reviewing the trademark portfolio.

Businesses often change over a 10-year period.

For example:

  • A company may change its legal name.
  • Ownership may change.
  • A brand may be assigned to another entity.
  • Products or services may expand.
  • Some brands may be discontinued.
  • The business may start using a new logo.
  • The proprietor’s address may change.

A renewal exercise is therefore a useful opportunity to check whether the trademark records still reflect the business.

However, renewal does not automatically update ownership or other registration details. Where a separate change is required, the appropriate Trade Marks Registry procedure should be considered.

Trademark Renewal vs New Trademark Registration

These two processes should not be confused.

Trademark RenewalNew Trademark Registration
Applies to an existing registered trademarkApplies to a new trademark application
Extends the existing registrationStarts a new registration process
Generally every 10 yearsDepends on successful registration
Uses TM-R for renewalUses the applicable registration application process
Maintains the existing registered markSeeks registration of a mark

If your trademark is already registered and approaching expiry, renewal is generally the starting point for maintaining that registration.

If the brand has materially changed, however, the business may need to assess whether additional trademark applications or other filings are appropriate.

What Documents and Details Should You Keep Ready?

Trademark renewal is primarily an official filing process, but businesses should keep their trademark records organised.

Before filing, review:

  • Trademark registration certificate/details
  • Trademark registration number
  • Class or classes
  • Registered proprietor name
  • Current address
  • Expiry date
  • Details of any assignment or ownership change
  • Details of any pending trademark proceedings
  • Authorisation details, where a representative is filing

The exact documentation required can depend on the nature of the application and the circumstances of the trademark.

Do not assume that every renewal application requires the same supporting documents.

How to Check Your Trademark Renewal Status

Before filing a renewal application, check the trademark record through the official Trade Marks Registry system.

The purpose is to establish:

  • Whether the mark is registered
  • Registration number
  • Class
  • Proprietor
  • Registration date
  • Expiry date
  • Current status
  • Relevant proceedings or correspondence

This is particularly important where a trademark was registered many years ago and the business does not have complete historical records.

A business should work from the current official trademark record, not only from an old certificate or internal spreadsheet.

Common Mistakes in Trademark Renewal

1. Waiting until the last day

Even where the law provides a renewal window, waiting creates unnecessary risk.

2. Looking only at the registration certificate

Old records may not reflect later changes or current status.

3. Confusing renewal with ownership change

Renewal does not automatically transfer a trademark to a new proprietor.

4. Ignoring multiple classes

Renewal fees are prescribed per class, so a business with multiple classes should review each applicable registration.

5. Assuming an expired mark is automatically permanently lost

The law provides specific post-expiry mechanisms, including renewal with surcharge and restoration in prescribed circumstances.

6. Treating renewal as the only trademark compliance issue

A business should also consider changes in ownership, address, use, branding and other relevant trademark matters.

7. Relying on outdated fee information

Government fees and procedures can change. Always check the current IP India fee schedule before filing.

A Practical Trademark Renewal Checklist

Before the renewal date, use this checklist:

Trademark details

  • Registration number checked
  • Class or classes checked
  • Registered proprietor verified
  • Expiry date confirmed

Business details

  • Proprietor details reviewed
  • Address reviewed
  • Ownership changes checked
  • Brand/logo changes reviewed

Renewal

  • Renewal eligibility checked
  • Current IP India fee verified
  • TM-R prepared
  • Correct class details confirmed
  • Filing/payment completed
  • Filing acknowledgement retained

After filing

  • Application status monitored
  • Renewal record checked
  • Updated expiry information recorded
  • Next renewal reminder created

Example: A Small Business With an Expiring Trademark

Suppose an Indian clothing business registered its brand in 2017.

The registration is approaching its 2027 expiry date.

Instead of waiting until the final month, the business checks the trademark record, confirms the proprietor and class details, reviews whether the brand is still being used and prepares the renewal application.

Because the renewal can be made within the permitted advance period, the business has an opportunity to deal with the matter before the registration expires.

Now consider another business that discovers after expiry that it never completed renewal.

The correct response is not automatically to file a new trademark application. The business should first check whether the existing registration is eligible for renewal with surcharge or, if already removed, whether restoration is available under the applicable provisions. 

What Should You Do If Your Trademark Renewal Is Already Overdue?

If you have missed your trademark renewal date, take these steps:

Step 1: Check the trademark record

Confirm the current status with the Trade Marks Registry.

Step 2: Confirm the expiry date

Do not rely only on an old reminder or internal record.

Step 3: Identify the applicable route

Determine whether the matter falls under:

  • Normal renewal
  • Renewal with surcharge
  • Restoration and renewal

Step 4: Check the current official fee

Use the latest IP India fee schedule.

Step 5: Review the trademark details

Check the proprietor, class, address and other relevant information.

Step 6: File the appropriate application

Use the applicable form and procedure based on the current status.

Step 7: Monitor the application

Keep the acknowledgement and track the application until the renewal or restoration is reflected appropriately.

Why Trademark Renewal Matters for Businesses

A trademark can become an important business asset over time.

A registered brand may be used on:

  • Products
  • Packaging
  • Websites
  • Marketing materials
  • Online marketplaces
  • Storefronts
  • Franchise operations
  • Business communications

Allowing an important trademark registration to lapse can create avoidable uncertainty around the brand’s registered protection.

For a business that has invested years in building brand recognition, trademark renewal should therefore be treated as part of its intellectual property management, not just as an administrative deadline.

Is Trademark Renewal Mandatory?

The better way to understand this is that renewal is required if the proprietor wants to continue the registered status of the trademark beyond the current registration period.

A registered trademark has a defined registration period. If the proprietor does not comply with the applicable renewal requirements, the Registrar can remove the mark from the Register subject to the statutory safeguards and post-expiry mechanisms. 

Therefore, businesses that want to maintain their registered trademark should actively track and complete renewal.

Frequently Asked Questions

How often does a trademark need to be renewed in India?

A registered trademark is generally valid for 10 years and can be renewed for further 10-year periods.

Which form is used for trademark renewal?

Trademark renewal is filed using Form TM-R with the prescribed fee. 

Can I renew my trademark before expiry?

Yes. Under Rule 57, an application for renewal may be made at any time not more than one year before the expiration of the last registration. 

What happens if I miss the trademark renewal deadline?

A statutory mechanism exists for renewal with surcharge within the prescribed period after expiry. If the trademark has been removed, restoration may be possible within the prescribed period, subject to the applicable requirements. 

What is the current trademark renewal fee?

IP India’s current fee schedule lists ₹9,000 for e-filing of ordinary renewal per class. Additional fees apply for surcharge and restoration. Check the current official schedule before filing.

Can a trademark be renewed after it is removed from the Register?

In certain circumstances, yes. Section 25(4) provides for restoration and renewal after removal for non-payment, subject to the statutory period and applicable requirements.

Does trademark renewal change the owner of the trademark?

No. Renewal itself does not automatically transfer ownership. A change in proprietor may require a separate procedure.

Should I file a new trademark application if my old trademark expired?

Not necessarily. First check the current status of the existing trademark and whether renewal with surcharge or restoration is available.

Final Takeaway

Trademark renewal in India is a recurring requirement for businesses that want to maintain their registered trademark. Registration generally lasts for 10 years, after which it can be renewed for another 10 years and subsequently renewed again.  

The safest approach is to track the expiry date, review the trademark details in advance and file TM-R within the permitted period.

If the deadline has already been missed, do not immediately assume that the trademark is permanently lost. Check its current status and determine whether renewal with surcharge or restoration is available under the applicable provisions.

For businesses, trademark renewal is also a good opportunity to review whether the registered proprietor, brand, classes and other details still match the way the business operates.

Need help with trademark registration or renewal?

Filing Point can help businesses understand the applicable trademark filing and compliance requirements.

📞 +91 72999 72500
📧 enquiry@filingpoint.com

Registered a company but haven’t started the business yet? You may still have compliance obligations even if your company has earned ₹0 revenue.

Many founders incorporate a Private Limited Company before they are ready to start actual business operations. They may still be developing their product, looking for funding, finalising their premises, hiring employees or waiting for the right time to launch.

During this period, it is easy to assume that there is nothing to comply with because the company has no customers and no sales.

That assumption can create problems.

A company can have zero revenue and still have ROC, accounting, income-tax, GST or director-related obligations, depending on its registrations, transactions and circumstances.

For example, a company with no sales but an active GST registration may have a different compliance position from a company that has not obtained GST registration. Similarly, a company with no revenue but with professional fees, bank charges or other expenses still has financial transactions that need to be considered.

So, the better question is not:

“Did my company make any money?”

Instead, founders should ask:

  • Is the company still active?
  • Has the business actually started?
  • Does the company have GST registration?
  • Has it incurred any expenses?
  • Has it received or issued any invoices?
  • Has shareholder capital been introduced?
  • Do the directors have applicable KYC obligations?
  • Is the registered office still valid?
  • Have applicable ROC filings been completed?
  • Does the company still need to exist?

This guide explains what founders should review when a newly incorporated company has zero revenue or has not yet started business.

Does Zero Revenue Mean Zero Compliance?

No.

This is one of the most important distinctions for a newly incorporated company.

Consider two companies.

Company A

  • Incorporated in April
  • No sales
  • No employees
  • No GST registration
  • No bank transactions except incorporation-related expenses

Company B

  • Incorporated in April
  • No sales
  • GST registration obtained
  • Company bank account active
  • Director expenses paid through the company account
  • Professional fees incurred

Both companies have zero revenue, but their compliance position may not be identical.

Company B has an active GST registration and financial transactions that need to be considered. Company A may have a different set of obligations.

Therefore, founders should not use revenue alone to determine whether compliance is required.

The company’s registrations, transactions, legal status and activities all matter.

Does ROC Compliance Continue If the Company Has No Business?

Zero revenue does not automatically eliminate applicable corporate compliance.

A registered company may still have obligations relating to its books of account, financial statements, annual filings, director-related requirements and other applicable MCA filings.

The exact requirements depend on the company’s structure, status and circumstances.

This means:

₹0 sales does not necessarily mean ₹0 ROC compliance.

Depending on the company, continuing compliance may involve:

  • Books of account
  • Financial statements
  • Auditor-related requirements, where applicable
  • Annual return
  • Applicable MCA forms
  • Director-related filings
  • Registered-office records
  • Other event-based filings

The absence of customers or sales does not automatically remove these obligations.

Why this matters for a newly incorporated company

A founder may incorporate a company in April and plan to launch in October.

During those six months, the company may have no customers or revenue.

However, the company still exists as a legal entity during that period.

It is therefore important to review its applicable corporate obligations rather than waiting until the business launch.

What If the Company Has No Transactions at All?

The phrase “no transactions” can mean different things.

Situation 1: No operational activity

There are no customers, sales, purchases or business expenses.

Situation 2: No revenue but expenses exist

The company may have paid:

  • Accounting fees
  • Bank charges
  • Professional fees
  • Software subscriptions
  • Office rent
  • Other business expenses

Situation 3: Shareholder money was introduced

A founder may have deposited money into the company’s bank account or paid expenses on behalf of the company.

Situation 4: GST registration is active

The company may have no sales but still have applicable GST return obligations.

Situation 5: The company has been abandoned

The founders may have decided that they no longer want to pursue the business.

These situations should not automatically be treated as the same.

Before deciding that a company has “no activity”, review what actually happened after incorporation.

Why Accounting Records Still Matter

“No revenue” does not necessarily mean “nothing to record”.

Even a company that has not started operations may have financial entries such as:

  • Bank charges
  • Incorporation-related expenses
  • Professional fees
  • Shareholder funds
  • Assets purchased
  • Liabilities
  • Statutory payments
  • Software subscriptions
  • Other business expenses

These transactions may need to be appropriately reflected in the company’s books and financial statements.

This is why it is better to maintain accounting records from the date of incorporation instead of waiting until the company starts generating revenue.

Example

Suppose a company has no sales for six months but spends:

  • ₹15,000 on professional services
  • ₹3,000 on software
  • ₹2,000 on bank charges

The company’s revenue is still ₹0.

However, it has had financial activity.

That distinction becomes important when preparing the company’s accounts and reviewing its tax and corporate compliance.

Does a Company With No Income Need to File an Income-Tax Return?

Do not assume that no income means no income-tax compliance.

A company’s income-tax obligations need to be assessed based on the applicable tax framework and its actual circumstances.

A company may have:

  • No sales
  • No profit
  • Expenses only
  • Share capital
  • Bank interest
  • Preliminary expenses
  • Other financial entries

Therefore:

No profit does not automatically mean no income-tax compliance.

The applicable return and reporting position should be determined based on the company’s records and the tax framework applicable to the relevant period.

For a newly incorporated company, it is therefore important to distinguish between:

No revenue
No taxable income
No tax compliance

These are not necessarily the same thing.

Important Income-Tax Update for 2026

There is an important tax-framework transition in 2026.

The Income Tax Act, 2025 came into effect from 1 April 2026.

This means companies need to identify the correct tax framework and relevant tax year when reviewing their obligations.

For example, income relating to FY 2025–26 is dealt with under the earlier framework for AY 2026–27, while Tax Year 2026–27 falls under the new Income Tax Act, 2025.

For a company that has not started business, this distinction is still relevant.

The company should review:

  • The relevant financial/tax year
  • Whether any income was received
  • Whether expenses were incurred
  • Whether other financial transactions occurred
  • The applicable return requirements

The fact that the company has not started commercial operations does not, by itself, answer all of these questions.

What If the Company Has GST Registration but No Sales?

This is another common issue for newly incorporated businesses.

Suppose you registered your company and obtained GST registration because you expected to begin business.

The launch is then delayed.

There are:

  • No sales
  • No taxable supplies
  • No tax collected
  • No business activity

Does GST compliance automatically stop?

No.

If the GST registration remains active and the taxpayer is required to file the applicable returns, the absence of transactions may mean that nil returns need to be filed rather than filing nothing.

So:

No sales does not automatically mean no GST return.

The specific GST filing obligations depend on the taxpayer’s registration and applicable filing category.

This is why an inactive business with an active GST registration should periodically review its GST compliance rather than simply stop filing because there are no invoices.

GST Registration Chennai

Should You Keep the GST Registration?

There is no single answer for every inactive company.

It depends largely on what you intend to do with the business.

If the business will start soon

You may decide to retain the GST registration and continue the applicable GST compliance.

If the launch has been postponed

Review whether retaining the registration is appropriate based on your expected business plans.

If the business has been permanently discontinued

You can assess whether GST cancellation is appropriate.

The important distinction is:

GST cancellation is not the same as company closure.

Cancelling the GST registration does not automatically dissolve the company.

Company Registration and GST Registration Are Separate

This distinction is particularly important for first-time founders.

A founder may think:

“I cancelled my GST registration, so my company is closed.”

That is not correct.

Company incorporation and GST registration are separate legal and regulatory matters.

AreaWhat it relates to
Company incorporationCreation of the corporate entity
ROC complianceCorporate-law filings and obligations
Income taxDirect-tax compliance
GSTIndirect-tax registration and returns
UdyamMSME registration
TrademarkBrand protection
Company closureFormal exit from the corporate register

Cancelling one registration does not automatically cancel the others.

If the company itself is no longer required, its corporate status needs to be addressed separately.

What Is a Dormant Company?

A company that is not currently carrying on business may potentially consider dormant company status, provided it satisfies the applicable legal conditions.

The Companies Act provides a framework for dormant companies, including companies formed for a future project or to hold an asset or intellectual property and meeting the applicable conditions.

However:

An inactive company does not automatically become a dormant company.

Dormant status is a formal statutory status.

An eligible company needs to follow the prescribed process and meet the applicable conditions.

This can be useful to consider where founders want to preserve a company for a future project rather than immediately close it.

Dormant Is Not the Same as Abandoned

These terms are sometimes used interchangeably, but they describe different situations.

Dormant

The company has formally obtained dormant status under the applicable legal framework.

Inactive

The company has little or no business activity, but that does not necessarily mean it has formal dormant status.

Non-compliant

The company has failed to complete applicable statutory obligations.

Closed

The company has gone through an appropriate legal closure or strike-off process.

These are different situations.

Simply stopping business activity does not automatically convert a company into a dormant company or close it.

What About Udyam Registration?

Udyam registration is separate from company incorporation.

A company should not assume:

“I registered my company, so I am automatically an MSME.”

Udyam eligibility depends on the applicable MSME classification criteria and the enterprise’s relevant information.

For a newly incorporated company that has not started business, the practical question is whether it meets the applicable conditions for Udyam registration and whether registration is relevant to its business.

Udyam registration also does not replace:

  • Company incorporation
  • ROC compliance
  • GST compliance
  • Income-tax compliance
  • Company closure procedures

Each registration serves a different purpose.

UDYAM Registration

What Happens to the Registered Office?

Even if the company has no customers, it still has a registered office.

The registered office remains important because statutory communications and company records are connected with the company’s registered details.

If the company moves to another address, the applicable MCA process should be followed.

If the company operates from a rented premises, founders should also ensure that the relevant address documentation remains valid.

An inactive company should not assume that its registered office is irrelevant simply because the business has not started.

Does Director KYC Still Apply?

Another common misconception is:

“There is no business, so the directors don’t need to do anything.”

Director-related MCA compliance can continue even when the company has little or no business activity.

Where applicable, directors holding DIN need to comply with prescribed KYC requirements.

Therefore, an inactive or pre-launch company should review:

  • DIN status
  • Director KYC
  • DSC validity
  • Changes in director details
  • Other applicable director-related requirements

Company inactivity does not automatically remove director-level compliance.

What About INC-20A?

For applicable companies, the declaration of commencement of business is a separate post-incorporation requirement.

This is important because:

Incorporation and commencement of business are not necessarily the same compliance event.

A founder may receive a Certificate of Incorporation and still have post-incorporation requirements to consider.

If the company is subject to the applicable commencement-of-business provisions, the founders should check the relevant requirement rather than assuming that incorporation itself completes every post-incorporation compliance step.

When Should You Consider Closing the Company?

Sometimes a business idea never gets launched.

A company may be incorporated, but after several months the founders may decide that they no longer want to pursue the business.

In that situation, simply abandoning the company is not a good substitute for assessing its formal status.

The founders can review whether the company should:

  • Continue as an active company
  • Consider dormant status, if eligible
  • Explore formal closure or strike-off, if eligible

Before considering closure, review:

  • Pending ROC filings
  • Income-tax compliance
  • GST status
  • Outstanding liabilities
  • Bank account
  • Assets
  • Contracts
  • Employee obligations
  • Shareholder matters
  • Regulatory or legal matters

The appropriate route depends on the company’s actual circumstances.

Keep the Company, Make It Dormant or Close It?

A simple framework can help founders organise the decision.

Current situationWhat to assess
Business launching soonContinue the company and maintain applicable compliance
Business delayed but still plannedReview whether continuing as active is appropriate
Future project with no current operationsAssess eligibility for dormant status
Business permanently abandonedAssess formal closure/strike-off
GST no longer requiredSeparately assess GST cancellation
Company still needed for future business or IPAssess whether retaining the entity is appropriate
Compliance has already been missedReview and regularise applicable obligations first

There is no universal answer.

The company’s structure, compliance history, registrations, liabilities and future plans all need to be considered.

Example: Startup Incorporated Before Launch

Consider Arun and Priya.

They incorporate ABC Technologies Private Limited in April and plan to launch their SaaS product in October.

Between April and September:

  • No customers
  • No sales
  • No taxable turnover
  • ₹20,000 in software expenses
  • ₹5,000 in bank charges
  • Founders introduce money into the company
  • Company bank account remains active

They should not simply conclude:

“We had no business, so there is nothing to file.”

Instead, they should review:

  1. Accounting records
  2. Financial statements
  3. Applicable ROC filings
  4. Income-tax requirements
  5. GST obligations, if registered
  6. Director KYC
  7. Registered-office compliance
  8. Commencement-of-business requirements, where applicable
  9. Whether the company should remain active for the planned launch

The company has zero revenue, but it has still had financial activity.

Example: A Business That Was Permanently Abandoned

Now consider another founder who incorporated XYZ Retail Private Limited but never launched the business.

After one year:

  • No sales
  • No employees
  • No active contracts
  • No planned launch
  • No future requirement for the company

This is a different situation.

The founder should review whether the company should:

Remain active,
seek dormant status if eligible, or
explore formal closure/strike-off if eligible.

The appropriate route depends on the company’s compliance position and future plans.

The key point is that zero revenue alone does not determine the company’s next legal status.

10 Common Mistakes Founders Make

1. “No sales means no ROC filing.”

Not necessarily.

Applicable corporate compliance can continue even when revenue is zero.

2. “No GST sales means no GST return.”

If GST registration remains active and the applicable return is due, nil filing may still be required.

3. “GST cancellation closes the company.”

It does not.

GST cancellation and company closure are separate processes.

4. “An inactive company automatically becomes dormant.”

Dormant status follows a formal statutory framework.

5. “We can ignore MCA until the business launches.”

This can allow applicable compliance obligations to accumulate.

6. “No bank activity means no accounting is required.”

The company’s records should still be reviewed for all financial entries and obligations.

7. “No income means no income-tax compliance.”

The applicable tax-return position should be assessed for the relevant tax year.

8. “Udyam registration replaces company registration.”

It does not.

9. “Closing the office means closing the company.”

It does not.

10. “We will fix everything when we restart.”

Delaying compliance can make the eventual regularisation process more complicated.

Inactive Company Compliance Checklist

If your company is registered but has not started business, review these areas.

Corporate Compliance

  • Certificate of Incorporation
  • CIN
  • MOA and AOA
  • Registered-office details
  • Applicable post-incorporation requirements
  • INC-20A, where applicable
  • Annual ROC compliance

Accounting

  • Bank account
  • Bank statements
  • Expenses
  • Shareholder funds
  • Assets
  • Liabilities
  • Financial statements

Tax

  • Income-tax return requirements
  • GST registration status
  • Applicable GST returns
  • GST cancellation assessment, if appropriate
  • TDS obligations, if applicable

Directors

  • DIN status
  • Director KYC
  • DSC validity
  • Director information

MSME

  • Udyam eligibility
  • Existing Udyam registration
  • Required updates, where applicable

Future Status

Finally, decide whether the company should:

Continue → Consider dormant status, if eligible → Consider closure, if appropriate

 What Should You Do First?

If your company is registered but has not started business, do not immediately cancel registrations or assume that nothing needs to be filed.

Start with a compliance-status review.

Step 1: Check the company’s MCA status

Confirm that the company is active and identify any pending filings.

Step 2: Review the financial records

Check whether the company has had:

  • Income
  • Expenses
  • Bank transactions
  • Capital introduced
  • Assets
  • Liabilities

Step 3: Check GST

Determine whether the company has an active GSTIN and identify the applicable filing requirements.

Step 4: Review income-tax obligations

Identify the relevant tax year and applicable return framework.

Step 5: Review director compliance

Check DIN, KYC and other applicable director-related requirements.

Step 6: Decide the company’s future

Ask:
“Are we actually going to use this company?”

If yes, maintain the applicable compliance.

If the business is postponed, assess whether continuing as an active company or considering dormant status is appropriate.

If the business has been permanently abandoned, assess whether formal closure is available.

Frequently Asked Questions

Does a company with zero revenue still need ROC filing?

Zero revenue does not automatically remove applicable ROC and corporate compliance obligations. The company’s structure, status and circumstances need to be considered.

Does a company with no sales need to file GST returns?

If the company has an active GST registration and the applicable return is due, nil filing may still be required.

Can I cancel the GST without closing my company?

Yes. GST cancellation and company closure are separate processes.

Does an inactive company automatically become dormant?

No. Dormant status is a formal statutory status subject to applicable eligibility and procedural requirements.

Does Director KYC apply if the company has no business?

Director-related KYC obligations can continue even when the company has little or no business activity.

Should I close a company that has never started business?

Not automatically. First review the company’s compliance position and determine whether it should remain active, qualify for dormant status or be considered for formal closure.

Is Udyam registration the same as company registration?

No. Udyam registration and company incorporation serve different purposes and have separate eligibility and compliance frameworks.

What should I check first if my company has been inactive for a year?

Start with the company’s MCA status, pending ROC filings, accounting records, GST status, income-tax position, director KYC and registered-office details. Then assess the appropriate future status of the company.

Final Takeaway

A company does not stop being a company simply because the founders have not started selling.

That is why:

Zero revenue and zero compliance are not the same thing.

For a newly incorporated or inactive company, the important areas to review are:

ROC → Accounting → Income Tax → GST → Director KYC → Registered Office → Udyam → Future Status

The key question is not simply whether the company has made money.

It is whether the company is:

  • Preparing to launch
  • Temporarily inactive
  • Being preserved for a future project
  • Or permanently abandoned

Once that is clear, the founders can determine which compliance obligations need attention and whether the company should continue, seek an appropriate dormant status or explore formal closure.

Need Help With Company Compliance?

Need help understanding your company’s compliance position after incorporation?

Filing Point can help you understand the applicable requirements for your business.

📞 +91 72999 72500
📧 enquiry@filingpoint.com

This article is for general information. Company, GST, income-tax and MCA requirements can vary depending on the company’s structure, transactions, registrations and circumstances. Verify the applicable requirements before filing, cancelling a registration or closing a company.

Starting a manufacturing business in Coimbatore involves more than registering a company. Depending on the business model, founders may need to consider company or LLP registration, GST, Udyam/MSME registration, trademark protection, factory-related approvals, pollution-control requirements, labour registrations and product-specific licences.

The exact requirements depend on the legal structure, manufacturing activity, premises, turnover, employees, machinery, products and applicable Tamil Nadu and central regulations.

This guide explains how these registrations fit together and what entrepreneurs should consider before starting a manufacturing business in Coimbatore.

Quick Answer: What Registration Does a Manufacturing Business in Coimbatore Need?

A manufacturing business in Coimbatore may need several registrations and approvals depending on its circumstances.

Company or LLP registration establishes the legal structure of the business. GST registration deals with indirect tax requirements. Udyam registration provides MSME recognition for eligible enterprises. Trademark registration protects the business brand, while factory, pollution-control, labour and product-specific approvals may apply depending on the manufacturing activity and premises.

There is therefore no single registration that covers every requirement for a manufacturing business.

Why Coimbatore Is a Strong Location for Manufacturing Businesses

Coimbatore has a long-established industrial and manufacturing ecosystem.

The Coimbatore District administration identifies textiles, textile machinery, auto components, pumps, motors, wet grinders, engineering products and other manufacturing activities as important parts of the local economy. The district also has a substantial base of small, medium and large industries.

This makes the city relevant for entrepreneurs starting businesses such as:

  • Engineering components
  • Industrial machinery
  • Pumps and motors
  • Textile machinery
  • Garments and textile products
  • Auto components
  • Electrical and electronic products
  • Consumer products
  • Food and packaged products
  • Industrial tools and equipment
  • Manufacturing-related technology businesses

For a new entrepreneur, however, choosing Coimbatore as the manufacturing location is only one part of the decision.

The founder also needs to decide how the business will be legally structured and which registrations and approvals will be required for the actual activity

Company Incorporation

Choosing the Right Legal Structure for a Manufacturing Business

The first major decision is the legal structure.

Common options include:

StructureUsually suitable forKey consideration
Private Limited CompanyGrowing manufacturers and startupsShare-based ownership and structured corporate framework
LLPPartner-led businesses and some engineering/service businessesFlexible partnership structure with limited liability
Partnership FirmSmall businesses with closely involved partnersPartnership-based ownership
OPCEligible single-founder businessesSingle-member corporate structure
ProprietorshipVery small individual businessesSimpler structure but no separate legal entity

There is no universal answer.

A founder manufacturing industrial components for a few customers may have very different requirements from a startup developing a new technology product and planning to raise external investment.

Private Limited Company for Manufacturing

A Pvt Ltd manufacturing company can be appropriate when founders want a formal corporate structure with shareholders and directors.

It may be particularly relevant when the business plans to:

  • Bring in investors
  • Add shareholders
  • Expand ownership
  • Build a larger corporate organisation
  • Pursue institutional funding
  • Create a scalable manufacturing business
  • Establish a long-term brand

Company incorporation is handled through the Ministry of Corporate Affairs (MCA) framework.

For a new company, the incorporation process involves matters such as name selection, incorporation documents, directors, registered office details, Digital Signature Certificates and other linked registrations.

The exact government fees depend on factors such as the incorporation details and applicable state stamp duty, so founders should avoid relying on a single advertised “company registration fee” as a universal cost.

LLP for Manufacturing and Engineering Businesses

An LLP manufacturing business can be considered where two or more partners want limited liability with a partnership-based structure.

LLPs can be particularly relevant for certain engineering, consulting, design, technical-service or closely held businesses.

MCA’s LLP incorporation process uses FiLLiP for name reservation and LLP incorporation.

An LLP can also be eligible for DPIIT Startup India recognition if it satisfies the applicable requirements.

However, founders should consider future funding and ownership plans before choosing an LLP. Startup India’s guidance notes that investors in an LLP would generally become partners, whereas a company can accommodate investors through its shareholding structure.

Partnership Firm for Small Manufacturing Businesses

A registered partnership firm may be considered by two or more individuals operating a closely held small manufacturing business.

It can be relevant where the founders already have a clear partnership arrangement and do not require a corporate shareholding structure.

However, the partners should understand the legal, financial and tax implications before selecting this structure.

For a manufacturing business that expects significant expansion, external investment or a more formal corporate ownership structure, it is worth comparing a partnership with an LLP or Private Limited Company before registration.

Private Limited Company Registration

MSME/Udyam Registration for Manufacturing Businesses

One of the most common areas of confusion is the difference between company registration and MSME registration.

They are not the same.

Company registration creates the business structure.

Udyam registration provides MSME recognition to an eligible enterprise.

An eligible manufacturing business can obtain Udyam Registration through the official Ministry of MSME portal.

The official Udyam portal states that registration is free, paperless and based on self-declaration, and an enterprise receives a permanent Udyam Registration Number and online certificate.

The current MSME classification uses investment and turnover criteria.

MSME categoryInvestment limitTurnover limit
MicroUp to ₹2.5 croreUp to ₹10 crore
SmallUp to ₹25 croreUp to ₹100 crore
MediumUp to ₹125 croreUp to ₹500 crore

These are the current classification limits displayed on the official Udyam portal following the revision effective from 1 April 2025.

For a company or LLP, the Udyam process also uses the organisation’s PAN and GSTIN where applicable, together with Aadhaar details of the authorised person.

Why Udyam Registration Matters

An eligible manufacturing MSME may consider Udyam registration because MSME recognition can be relevant when accessing government schemes, formal credit channels and other benefits available to eligible enterprises.

However, entrepreneurs should not assume that Udyam registration automatically provides every MSME benefit. Individual schemes can have additional eligibility conditions.

GST Registration for Manufacturing Companies

GST is another important consideration for manufacturing businesses.

GST registration is separate from company registration and Udyam registration.

Whether a manufacturing business needs GST registration depends on its taxable supplies, turnover and the applicable compulsory-registration provisions.

The CGST framework contains turnover-based registration provisions, while specific circumstances can trigger registration under separate provisions.

Therefore, a founder should not simply assume:

“I registered my company, so GST is automatically completed.”

That is not how these registrations work.

A manufacturing company should evaluate:

  • What products it sells
  • Whether the products are taxable or exempt
  • Annual aggregate turnover
  • Whether it makes inter-State supplies
  • Whether any compulsory-registration provision applies
  • Where the business operates
  • Whether it needs GST registration for commercial reasons

For a manufacturing business selling products across Tamil Nadu or other Indian states, GST planning should be considered early because the business may need to issue compliant tax invoices and maintain appropriate GST records once registered.

Trademark Registration for Manufacturing Brands

Manufacturing companies often invest heavily in a product name, logo, packaging and market reputation.

That makes trademark registration worth considering as part of the business setup process.

A manufacturing brand may include:

  • Machinery brands
  • Industrial equipment brands
  • Consumer products
  • Electrical products
  • Textile brands
  • Private-label products
  • Engineering product brands
  • Food or packaged-product brands

Company registration does not automatically give comprehensive trademark protection for the brand.

For example, registering ABC Manufacturing Private Limited as a company does not mean every use of “ABC” as a product or brand name is automatically protected as a trademark.

Before investing heavily in packaging, machinery branding, website development or marketing, founders should consider conducting a trademark search and assessing whether trademark registration is appropriate.

Other Registrations and Approvals for Manufacturing Businesses

This is where manufacturing businesses differ significantly from ordinary service businesses.

There is no universal list of licences that applies to every factory in Coimbatore.

The applicable approvals can depend on:

  • Type of product
  • Manufacturing process
  • Factory premises
  • Machinery
  • Power usage
  • Number of employees
  • Pollution category
  • Chemicals or hazardous materials used
  • Storage requirements
  • Packaging
  • Local-body requirements
  • Environmental impact
  • Industry-specific laws

Factory and Labour Requirements

Manufacturing units may have obligations under applicable factory and labour laws depending on their operations.

Tamil Nadu’s labour systems provide registration-related services for factories and other establishments.

The exact requirement should therefore be assessed based on the proposed premises, workforce and manufacturing activity rather than applying a generic checklist.

Pollution-Control Approvals

Manufacturing activity can also involve the Tamil Nadu Pollution Control Board (TNPCB).

Depending on the nature and pollution category of the unit, the business may need approvals such as Consent to Establish (CTE) and/or Consent to Operate (CTO).

TNPCB maintains processes for consent-related approvals and its technical committee handles specified categories of industrial units.

A manufacturing founder should therefore identify the applicable pollution category and approval requirements before setting up the unit.

Businesses manufacturing, packing or importing certain products for sale may also have requirements under Legal Metrology laws.

For example, Tamil Nadu’s labour/legal-metrology department provides registration procedures for manufacturers, packers and importers of packaged commodities.

This illustrates why a product-specific assessment is important.

A machinery manufacturer, food manufacturer and packaged consumer-product manufacturer may not have the same compliance requirements.

Manufacturing Business Registration Checklist

The following checklist can help a founder identify the major areas to evaluate.

RequirementWhy it mattersWhen applicable
Business structureEstablishes the legal form of the businessAlways choose an appropriate structure
PAN/TANTax and financial complianceDepending on entity and tax requirements
GSTIndirect tax complianceBased on applicable GST rules
UdyamMSME recognitionEligible enterprises
TrademarkProtects brand identityWhen protecting a brand
Factory-related approvalsRegulatory compliance for manufacturing premisesDepending on factory/activity
TNPCB approvalEnvironmental complianceDepending on industry and pollution category
Labour registrationsEmployee and workplace complianceDepending on workforce and applicable laws
Legal MetrologyProduct/packaging complianceWhere applicable
Sector-specific licencesCompliance with industry-specific lawsDepending on product
Local approvalsPremises and local operational requirementsDepending on location and activity

This should be treated as a starting checklist, not a universal licence list.

Company Registration vs MSME Registration

This is one of the most important distinctions for a manufacturing entrepreneur.

Company RegistrationMSME/Udyam Registration
Creates/registers the chosen business entityRecognises an eligible enterprise as an MSME
Governed through the applicable legal framework for the entityGoverned through the Ministry of MSME framework
Relevant to companies such as Private Limited CompaniesAvailable to eligible enterprises meeting MSME criteria
Does not automatically provide MSME statusDoes not create a Private Limited Company or LLP
Company incorporation is separate from UdyamUdyam is a separate registration

For example, suppose two founders start a machinery manufacturing business in Coimbatore.

They could first establish a Private Limited Company or another suitable business structure.

If the enterprise meets the applicable MSME classification criteria, it could then obtain Udyam Registration.

The two registrations serve different purposes.

This distinction is particularly important for founders searching for MSME registration in Coimbatore or Udyam registration in Coimbatore because Udyam registration is not a replacement for company incorporation.

How to Register a Manufacturing Company in Coimbatore

The practical process can be approached in stages.

Step 1: Define the Manufacturing Business

Clearly identify:

  • Product
  • Manufacturing process
  • Target customers
  • Proposed premises
  • Machinery
  • Number of employees
  • Expected turnover
  • Whether sales will be local, across India or international

This information affects later compliance decisions.

Step 2: Choose the Business Structure

Compare the suitability of:

  • Private Limited Company
  • LLP
  • Partnership
  • OPC, where appropriate

Do not choose a structure only because its initial registration cost appears lower.

Consider ownership, funding, liability, compliance and long-term plans.

Step 3: Complete the Business Registration

For a Private Limited Company, incorporation is carried out through the MCA framework.

For an LLP, MCA provides the FiLLiP incorporation route.

The incorporation process involves submitting the required details and documents and obtaining the applicable identification and registration details.

Step 4: Set Up Tax and Banking Requirements

After incorporation, assess:

  • PAN
  • TAN
  • GST
  • Business bank account
  • Accounting system
  • Applicable tax registrations

Do not assume that every optional or conditional registration is automatically required.

Step 5: Obtain Udyam Registration if Eligible

If the business qualifies as a micro, small or medium enterprise, consider Udyam Registration.

The official Udyam portal states that the registration process is free and paperless.

Step 6: Check Factory and Product-Specific Approvals

Before starting production, assess applicable:

  • Factory requirements
  • TNPCB approvals
  • Labour requirements
  • Local-body approvals
  • Fire/safety requirements where applicable
  • Legal Metrology requirements
  • Product-specific licences
  • Industry-specific regulations

This stage should be based on the actual manufacturing activity.

How Much Does Manufacturing Company Registration Cost in Coimbatore?

There is no single fixed cost for registering a manufacturing business in Coimbatore.

The cost depends on the legal structure and the requirements of the business.

For example, the overall setup cost can involve:

  • Government incorporation fees
  • Applicable stamp duty
  • Professional service fees
  • DSC-related costs where applicable
  • GST-related professional assistance, if required
  • Udyam registration assistance, if any
  • Trademark fees, if applicable
  • Factory or local approvals
  • Environmental approvals
  • Product-specific licences

Udyam Registration itself is officially free on the government portal.

Manufacturing businesses should therefore avoid comparing structures solely by their incorporation fee.

A better question is:

What will this business need to legally start production and sell its products?

That gives a more realistic picture of the setup requirement.

How Long Does Manufacturing Company Registration Take?

There is no single guaranteed timeline for every manufacturing business.

The time required depends on:

  • Whether the proposed company name is accepted
  • Accuracy of incorporation documents
  • MCA processing
  • Government approvals
  • Nature of the manufacturing activity
  • Premises-related requirements
  • Pollution-control requirements
  • Factory approvals
  • Product-specific licences

Company incorporation itself and obtaining permission to operate a manufacturing facility are also separate processes.

A business may complete its legal entity registration while still needing additional approvals before commencing a particular manufacturing activity.

Therefore, founders should plan the registration and approval process as a compliance sequence, rather than assuming that incorporation alone means the factory is ready to operate.

Practical Example: Engineering Startup in Coimbatore

Consider two founders starting an engineering company that manufactures industrial pump components.

They may decide to establish a Private Limited Company because they expect to grow the business and potentially bring in investors later.

Their setup could involve:

Stage 1: Private Limited Company incorporation

Stage 2: PAN/TAN and business banking

Stage 3: GST assessment and registration, where applicable

Stage 4: Udyam registration if the enterprise qualifies as an MSME

Stage 5: Trademark assessment for the product/brand

Stage 6: Factory and premises-related compliance

Stage 7: TNPCB assessment and applicable consent

Stage 8: Labour and employee-related compliance

Stage 9: Product-specific regulatory assessment

Notice that there is no single “manufacturing registration” completing all these steps.

Each requirement addresses a different part of the business.

Common Mistakes Manufacturing Entrepreneurs Make

1. Assuming incorporation covers everything

Registering a Private Limited Company or LLP does not automatically mean every manufacturing approval is completed.

Better approach: Prepare a separate post-incorporation and factory-compliance checklist.

2. Treating Udyam as company registration

Udyam registration and business entity registration serve different purposes.

Better approach: Complete the appropriate entity registration first and then evaluate Udyam eligibility.

3. Choosing a structure only because it is cheaper

A low initial registration cost does not necessarily mean lower long-term business costs.

Better approach: Consider ownership, funding, compliance and future expansion.

4. Ignoring product-specific rules

A food manufacturer, machinery manufacturer and packaged-product manufacturer can have very different regulatory requirements.

Better approach: Identify the exact product and manufacturing process before finalising the compliance checklist.

5. Checking licences after taking the premises

Some manufacturing approvals can depend on the location, premises and nature of operations.

Better approach: Check applicable premises and regulatory requirements before making significant investments.

6. Forgetting brand protection

Manufacturers often invest heavily in a product name before checking trademark availability.

Better approach: Conduct a trademark search early and consider registration where appropriate.

Frequently Asked Questions

1. Is company registration mandatory for a manufacturing business in Coimbatore?

Not every manufacturing business must be incorporated as a company. Depending on the business model, an entrepreneur may consider a Private Limited Company, LLP, partnership or other suitable structure. The correct choice depends on ownership, liability, funding and business plans.

2. Is Udyam registration the same as company registration?

No. Udyam registration is not company incorporation. Udyam provides MSME recognition to eligible enterprises, while company registration establishes a company as a legal entity.

3. Is Udyam registration compulsory for a manufacturing company?

Udyam registration should not be confused with incorporation. It is the official MSME registration mechanism for eligible enterprises. Whether an entrepreneur should obtain it depends on the business’s eligibility and intended use of MSME-related benefits.

4. Does a manufacturing company need GST registration?

It depends on the business’s taxable supplies, turnover and applicable GST provisions. GST registration is separate from company incorporation and Udyam registration.

5. Is LLP suitable for a manufacturing business?

An LLP can be suitable for some partner-led businesses, particularly where flexibility and closely held ownership are important. However, founders expecting substantial external equity investment should compare LLP and Private Limited structures carefully.

6. Is a Private Limited Company suitable for manufacturing?

A Private Limited Company can be suitable for manufacturers planning a formal corporate structure, shareholders, expansion or external investment. Its suitability depends on the founders’ business and funding plans.

7. Does every manufacturing unit need TNPCB approval?

Not necessarily in the same form. Requirements depend on the nature and category of the industrial activity and applicable environmental regulations. A manufacturing business should assess the specific requirements before starting operations.

8. What is the MSME limit for a manufacturing business?

Under the current Udyam classification, a micro enterprise can have investment up to ₹2.5 crore and turnover up to ₹10 crore; a small enterprise up to ₹25 crore investment and ₹100 crore turnover; and a medium enterprise up to ₹125 crore investment and ₹500 crore turnover.

9. Can a manufacturing startup get DPIIT recognition?

An eligible Private Limited Company, LLP or registered partnership can apply for DPIIT startup recognition if it meets the current Startup India criteria.

10. What documents are needed for manufacturing company registration?

The documents depend on the chosen structure. Incorporation generally involves identity and address information of the founders/directors or partners, registered-office information and other documents required by the applicable MCA process. Additional documents may be required for GST, Udyam, factory and sector-specific approvals.

Final Checklist for Entrepreneurs in Coimbatore

Before starting a manufacturing business, review these areas:

Business structure

  • Private Limited Company
  • LLP
  • Partnership
  • OPC, where appropriate

Tax and statutory

  • PAN
  • TAN
  • GST, where applicable
  • Accounting and tax compliance

MSME

  • Udyam eligibility
  • Udyam Registration

Brand

  • Trademark search
  • Trademark registration, where appropriate

Factory and premises

  • Factory-related requirements
  • Local approvals
  • Labour requirements
  • Fire/safety requirements where applicable

Environmental

  • TNPCB category
  • Consent requirements where applicable

Product

  • Legal Metrology, where applicable
  • Industry-specific licences
  • Product-specific regulatory requirements

The final checklist should be based on the actual product, premises, manufacturing process and workforce, not simply on the fact that the business is located in Coimbatore.

Conclusion

Starting a manufacturing business in Coimbatore requires more than choosing a company name and completing incorporation.

The first step is selecting the appropriate business structure. The next steps may include GST registration, Udyam/MSME registration, trademark protection, factory-related compliance, pollution-control approvals, labour registrations and product-specific licences, depending on the business.

The key distinction is simple:

Company registration establishes your business structure. Udyam registration provides MSME recognition. GST registration addresses indirect tax requirements. Other approvals may be required to legally operate the manufacturing activity.

If you are planning company registration for a manufacturing business in Coimbatore, FilingPoint can help you evaluate the appropriate business structure and complete the relevant incorporation process.

You can explore FilingPoint’s company registration, LLP registration and OPC registration services before deciding which structure fits your business.

Choosing a legal structure is one of the first important decisions when starting a technology business in India.

For a two-founder SaaS business, software development company, AI startup, IT services company or technology product business, the two structures most commonly considered are a Limited Liability Partnership (LLP) and a Private Limited Company.

Both provide limited liability and can operate as independent legal entities. But they are not interchangeable.

A Private Limited Company is generally better suited to a technology startup that plans to raise equity investment, issue shares to founders or employees, build a formal ownership structure and scale aggressively. An LLP can be attractive when the founders want limited liability with comparatively flexible management and a simpler ownership arrangement.

The right choice depends on your business model and growth plans not simply on which registration is cheaper.

LLP vs Private Limited Company: Quick Answer

A Private Limited Company is usually the stronger choice for a tech startup planning to raise angel or venture capital, issue equity, create an employee stock option structure or build a business for rapid scale. An LLP can be more suitable for a founder-led technology services or consulting business where external equity funding is not a major objective.

Both Private Limited Companies and LLPs can be eligible for Startup India recognition, subject to the applicable eligibility conditions. Startup India currently recognises Private Limited Companies, registered partnership firms and LLPs, among other eligible entities.

What Is an LLP in India?

A Limited Liability Partnership (LLP) is a separate legal business structure governed by the Limited Liability Partnership Act, 2008.

It combines features of a traditional partnership with limited liability protection. The business is operated through partners, including designated partners who are responsible for statutory and regulatory matters.

For example, suppose two software developers in Chennai start a technology consulting business. They do not intend to raise venture capital and expect most of their income to come from client projects.

An LLP may provide the limited-liability structure they need without creating a share-based company structure.

An LLP is particularly worth considering for:

  • Technology consulting firms
  • Software development agencies
  • IT service businesses
  • Freelance teams becoming formal businesses
  • Professional service businesses
  • Bootstrapped businesses
  • Businesses owned and operated primarily by their founders

However, an LLP may become less convenient if the business later wants to bring in multiple equity investors.

What Is a Private Limited Company?

A Private Limited Company is a separate legal entity incorporated under the Companies Act, 2013 and registered with the Ministry of Corporate Affairs (MCA).

Ownership is represented through shares held by shareholders, while management is handled by directors.

This structure is commonly used by technology startups because it creates a formal framework for:

  • Founder shareholding
  • Equity investment
  • Share transfers
  • Investor participation
  • Employee equity arrangements
  • Corporate governance
  • Future fundraising

For example, consider three founders building an AI SaaS platform.

They expect to spend the first two years developing the product and then approach angel investors or venture capital funds.

For this type of business, Private Limited Company Registration is generally more suitable than LLP registration because the company already has a share-based ownership structure.

LLP vs Private Limited Company: Key Differences

FactorLLPPrivate Limited Company
Governing frameworkLLP Act, 2008Companies Act, 2013
Separate legal entityYesYes
Liability protectionLimited, subject to lawLimited, subject to law
OwnershipPartnership interest/contributionShares
ManagementPartners/designated partnersDirectors
Equity fundraisingLess suitable for conventional startup equity fundingGenerally better suited
Angel/VC investmentCan be possible depending on structure and applicable rules, but less conventionalCommonly preferred
Employee equityLess straightforwardShare-based ESOP structures can be used, subject to law
ComplianceGenerally lighter than a company, but still requires statutory filingsGenerally more extensive
GovernanceMore flexibleMore formal
Founder controlFlexible through LLP agreementDetermined through shareholding, Articles and shareholder arrangements
Best suited forBootstrapped/service-led businessesFundable/scalable startups
Startup India eligibilityCan qualify, subject to conditionsCan qualify, subject to conditions
Conversion considerationsMay be possible depending on circumstancesMay be converted/restructured subject to applicable law

The important point is that “less compliance” does not mean “no compliance.” An LLP still has annual statutory filing requirements with MCA, while a company has a broader corporate compliance framework. MCA provides separate filing processes for companies and LLPs.

Which Is Better for a Tech Startup?

There is no universal answer.

But you can use this simple rule:

Choose a Private Limited Company if you plan to:

  • Raise angel investment
  • Raise venture capital
  • Give equity to investors
  • Create an employee stock option plan
  • Have several shareholders
  • Bring in strategic investors
  • Build a technology product for rapid scale
  • Potentially sell or transfer part of the business
  • Create a formal corporate ownership structure

Consider an LLP if you plan to:

  • Bootstrap the business
  • Operate mainly as a technology services company
  • Earn revenue from consulting or development projects
  • Keep ownership among a small group of founders
  • Avoid conventional equity fundraising
  • Prefer comparatively flexible internal management
  • Keep ongoing corporate formalities more manageable

The distinction becomes particularly important when you think beyond the first year.

A Realistic Example: Two Tech Startups, Two Different Choices

Example 1: Chennai SaaS startup

Suppose Arun and Priya develop a cloud-based HR software product in Chennai.

Their plan is:

  1. Build the MVP.
  2. Acquire 100 paying customers.
  3. Raise ₹1 crore from angel investors.
  4. Hire a product team.
  5. Raise a larger VC round later.

For this business, a Private Limited Company would normally be the more practical starting structure.

Why?

Because the founders can establish shareholding between themselves and subsequently issue or transfer shares subject to applicable law and documentation.

The company structure is designed around shareholders and shares, which fits the way equity-funded startups are normally structured.

Example 2: Software development business

Now consider three developers who start a software development and consulting firm.

Their plan is:

  • Get clients in India and overseas
  • Earn revenue from projects
  • Hire 10–15 employees
  • Distribute profits between the founders
  • Remain privately funded
  • Have no immediate plan to raise venture capital

Here, an LLP may be worth considering.

The founders may value flexibility and a comparatively lighter corporate compliance framework more than an investor-oriented equity structure.

The important lesson is:

Do not choose a Private Limited Company merely because someone says it is the “best” structure. Choose it when its ownership and fundraising model match your business plan.

Private Limited Company vs LLP for Startup Funding

This is one of the biggest differences.

Private Limited Company

A company has share capital and shareholders.

That makes it easier to design a conventional investment structure involving:

  • Founder shares
  • Investor shares
  • Different shareholding percentages
  • Future equity rounds
  • Share transfers
  • Employee equity arrangements, subject to applicable law

For a startup that expects multiple rounds of investment, this structure is usually easier for investors and professional advisers to work with.

LLP

An LLP does not operate through shares in the same way.

The relationship between partners is primarily governed through the LLP agreement and applicable law.

That can work very well for a closely held business.

But if your five-year plan includes multiple institutional investors and repeated equity funding rounds, you should think about the implications before registering the business.

Changing structures later can involve additional legal, tax, accounting and compliance work.

What About Startup India Recognition?

This is an important point for founders.

You do not need to form a Private Limited Company merely to become a recognised startup.

Startup India states that eligible startups can include Private Limited Companies and LLPs, subject to the applicable recognition conditions.

The current Startup India recognition framework also considers factors such as the age of the entity, turnover and whether the business is working towards innovation, development or improvement of products, processes or services, or has a scalable business model with potential for employment or wealth creation.

The current Startup India portal states that a startup can generally remain within the recognition period for up to 10 years, or 20 years for a DeepTech startup, and the turnover ceiling is currently ₹200 crore for a non-DeepTech startup and ₹300 crore for a DeepTech startup, subject to the applicable conditions.

So the decision should not be:

“LLP or Private Limited—which one gets Startup India?”

Both can potentially qualify.

The better question is:

“Which structure fits the way we intend to own, fund and operate the startup?”

What About Tax?

Tax should be considered, but it should not be the only reason for choosing the structure.

For AY 2026–27, the Income Tax Department states that a partnership firm, including an LLP, is taxable at 30%, with applicable surcharge and 4% health and education cess; AMT provisions can also apply in specified circumstances.

Private Limited Company taxation depends on the applicable tax regime and conditions. Companies may have different corporate tax options and should be assessed based on their circumstances rather than assuming a single tax rate applies to every company.

For a startup, the bigger financial question is often:

What will happen to the money generated by the business?

If profits are regularly distributed to founders, the tax and cash-flow implications may differ from a startup that retains profits and reinvests them into:

  • Product development
  • Employees
  • Marketing
  • Technology
  • Research
  • Expansion

Therefore, founders should compare the structure with their expected profit, salary/remuneration, reinvestment and fundraising plans rather than selecting one purely because of a headline tax rate.

What About GST?

LLP registration or Private Limited Company Registration does not automatically mean that every business must immediately obtain GST registration simply because the entity exists.

GST registration depends on the nature of supplies, turnover, applicable thresholds and specific compulsory-registration provisions.

For example, a technology company providing taxable services may need GST registration when the applicable conditions are met.

A startup should therefore treat these as separate questions:

  1. What legal entity should we form?
  2. Do we need GST registration?
  3. What GST compliance will apply to our business?

Do not assume that incorporation and GST registration are the same process.

The GST system is administered through the GST framework and portal, with registration and compliance requirements depending on the business’s circumstances.

GST Registration

PAN and TAN After Company or LLP Registration

PAN is important for the entity’s tax and financial operations.

TAN is relevant where the entity is required to deduct or collect tax at source under the applicable provisions.

For companies incorporated through the MCA’s SPICe+ process, MCA’s incorporation FAQs explain that PAN and TAN-related services are integrated into the incorporation process. The exact charges and process should always be checked against the current MCA filing system before quoting a registration package.

This is one reason founders should not treat company incorporation as simply “getting a certificate”.

There are several connected registrations and post-incorporation steps.

How Does Private Limited Company Registration Work in India?

The incorporation process is handled through the MCA’s online system.

For a typical Private Limited Company, the broad process involves:

Step 1: Decide the business structure

Determine whether Private Limited Company, LLP, OPC, partnership or proprietorship is appropriate.

Step 2: Decide founders and ownership

For a Private Limited Company, decide:

  • Shareholders
  • Directors
  • Proposed shareholding
  • Capital structure
  • Business activities

Step 3: Obtain Digital Signature Certificates

Digital signatures are used for electronically signing applicable incorporation documents.

Step 4: Select and reserve the company name

The proposed name must comply with MCA naming requirements and should not conflict with existing names or trademarks.

Step 5: Prepare incorporation documents

Typical incorporation documentation can include identity and address proofs, registered-office-related documents, declarations and constitutional documents as applicable.

Step 6: File through SPICe+

MCA’s SPICe+ framework covers company name reservation and incorporation-related services.

MCA’s official FAQ explains that SPICe+ Part A is used for name reservation, while Part B covers incorporation and linked services such as DIN, PAN and TAN, with GSTIN available as an optional linked service where applicable.

Step 7: MCA review

MCA examines the submitted application. If clarification or resubmission is required, the applicant needs to respond accordingly.

Step 8: Certificate of Incorporation

Once approved, the company receives its Certificate of Incorporation and related identification details.

The actual time can vary depending on document accuracy, name availability, MCA processing and whether resubmission or clarification is required. Therefore, a fixed “X-day guarantee” should not be treated as a government rule.

How Does LLP Registration Work?

LLP registration also takes place through the MCA system.

Broadly, founders need to:

  1. Decide the proposed LLP name.
  2. Identify partners and designated partners.
  3. Arrange required digital signatures and identification requirements.
  4. Prepare registered-office and partner documents.
  5. Apply for name reservation where applicable.
  6. File the LLP incorporation application.
  7. Receive the LLP incorporation/registration approval.
  8. Execute and file the LLP agreement within the applicable framework.
  9. Complete tax and other registrations relevant to the business.

After registration, an LLP also has continuing MCA compliance.

For example, MCA provides Form 8 for the Statement of Account and Solvency and Form 11 for the LLP’s annual return.

How Much Does Company Registration Cost in India?

There is no single government fee that applies to every startup.

The cost can depend on:

  • Business structure
  • State
  • Authorised share capital for a company
  • Contribution for an LLP
  • Stamp duty
  • Number of partners/directors
  • Documentation
  • Professional assistance
  • Additional registrations
  • Optional services

For companies incorporated through SPICe+, MCA’s published FAQ states that filing fees depend on authorised share capital and that stamp duty varies by state. It also describes a “zero filing fee” concession for companies incorporated through SPICe+ with authorised capital up to ₹15 lakh, while applicable state stamp duty remains payable.

That means an online advertisement saying:

“Company registration ₹999”

does not necessarily tell you what the founder will actually pay.

Before comparing service providers, ask for a clear breakup of:

Cost componentWhat to check
MCA filing feeBased on applicable structure/capital
Stamp dutyState-specific
DSCWhether included
PAN/TANWhether included in quoted package
Professional feeSeparate or included
GST registrationIncluded or additional
Annual complianceSeparate recurring cost
Other registrationsCheck based on business requirement

The initial registration cost is only one part of the decision. Annual compliance cost can matter much more over five years.

LLP vs Private Limited: Compliance Difference

This is often overlooked by new founders.

Private Limited Company

A company generally has more formal corporate compliance requirements.

These can include:

  • Maintenance of statutory records
  • Board-related requirements
  • Financial statements
  • Annual return
  • Income-tax compliance
  • TDS compliance where applicable
  • GST compliance where applicable
  • Audit requirements where applicable
  • Event-based MCA filings when changes occur

MCA’s filing system includes forms such as AOC-4 for financial statements and MGT-7/MGT-7A for applicable annual returns.

LLP

An LLP generally has a comparatively simpler internal governance structure, but it is still required to maintain statutory compliance.

Typical recurring filings include:

  • Annual Return
  • Statement of Account and Solvency
  • Income-tax return
  • TDS compliance where applicable
  • GST compliance where applicable
  • Event-based filings for applicable changes

MCA’s Form 8 instructions specifically relate to the Statement of Account and Solvency, demonstrating that LLPs also have formal annual reporting obligations.

So the real comparison is:

LLP = generally lighter corporate compliance

versus

Private Limited = more formal corporate governance and reporting

—not:

LLP = no compliance.

Other Business Structures You Could Consider

Before choosing LLP registration or Private Limited Company Registration, founders should also understand the alternatives.

StructureSuitable forFundingCompliance level
Private Limited CompanyScalable startupsStrong fit for equity fundingHigher
LLPBootstrapped/service businessesLess conventional for VC equityModerate
OPCSingle-founder businessLimited compared with investor-focused company structureModerate
Partnership FirmSmall founder groupsLimited suitability for startup equity fundingRelatively lower
Sole ProprietorshipIndividual/small businessNot designed for institutional equity fundingLower

A sole proprietorship is particularly different because the business does not have the same separate-entity structure as a company or LLP.

For a technology startup with ambitions to raise institutional capital, it is usually worth discussing the long-term ownership model before registering.

What About MSME/Udyam Registration?

Your legal entity and your MSME/Udyam status are separate matters.

A Private Limited Company or LLP may potentially qualify for Udyam registration if it satisfies the applicable MSME classification and registration requirements.

Do not confuse:

Company Registration

with:

Udyam Registration

or:

Startup India Recognition

They serve different purposes.

A startup may have:

  • MCA incorporation
  • PAN
  • GST registration, where applicable
  • Udyam registration, where eligible
  • DPIIT Startup recognition, where eligible
  • Trademark registration

These are not automatically the same registration.

Tamil Nadu Tech Startups: Does Location Change the Choice?

The fundamental choice between LLP and Private Limited Company is governed primarily by India’s central legal framework.

However, Tamil Nadu startups may also need to consider the state’s startup ecosystem and schemes.

Startup India’s Tamil Nadu policy information recognises Private Limited Companies, registered partnership firms and LLPs as possible eligible forms for the relevant state startup policy, subject to the policy’s conditions.

Therefore, a Chennai founder should not choose LLP simply because the business is in Tamil Nadu, or choose Private Limited merely because it is a “startup”.

The better approach is:

Choose the legal structure first based on ownership, funding and business model, then examine the central and Tamil Nadu schemes for which the business may qualify.

Common Mistakes Founders Make

1. Choosing based only on registration price

Saving a few thousand rupees during incorporation may not matter if the structure becomes inconvenient when you raise funding.

2. Assuming every startup needs a Private Limited Company

Not every technology business is a VC-funded startup.

A profitable software consulting company may be perfectly comfortable as an LLP.

3. Assuming LLP cannot be a startup

This is incorrect.

Eligible LLPs can apply for Startup India recognition subject to the applicable criteria.

4. Ignoring future investors

If you expect to approach investors within 12–24 months, discuss the ownership structure before incorporation.

5. Looking only at incorporation cost

The recurring compliance and professional costs can become more important than the initial registration expense.

6. Treating GST as part of incorporation

GST registration is a separate tax registration. Whether it is required depends on the business and applicable GST provisions.

7. Ignoring founder agreements

Registration alone does not solve founder disputes.

Founders should consider documenting:

  • Ownership
  • Roles
  • Decision-making
  • Intellectual property
  • Exit arrangements
  • Founder departure
  • Confidentiality
  • Investment rights

A technology startup should also pay attention to ownership of source code, product IP, domain names, designs and other intellectual property.

A Practical Decision Checklist

Before choosing LLP registration or Private Limited Company Registration, answer these 10 questions:

Choose Private Limited if most answers are “Yes”

  • Do we want angel or VC funding?
  • Will outside investors receive equity?
  • Do we expect multiple funding rounds?
  • Will we create an employee equity programme?
  • Do we want a formal shareholding structure?
  • Are there several founders?
  • Do we expect strategic investors?
  • Are we building a scalable technology product?
  • Could we eventually sell part or all of the business?
  • Are we comfortable with greater corporate compliance?

Consider LLP if most answers are “Yes”

  • Are we bootstrapping?
  • Is the business primarily service-based?
  • Will the founders remain closely involved?
  • Do we have no immediate VC funding plans?
  • Do we want a flexible partner-based structure?
  • Is profit distribution between founders more important than equity fundraising?
  • Do we want comparatively lighter corporate formalities?

This is not a substitute for professional legal or tax advice, but it is a useful first filter.

Frequently Asked Questions

1. Which is better for a tech startup: LLP or Private Limited?

A Private Limited Company is generally more suitable when a tech startup expects external equity funding, multiple shareholders, employee equity or rapid scaling. An LLP can be a good fit for bootstrapped technology services and consulting businesses.

2. Is LLP registration cheaper than Private Limited Company Registration?

Not necessarily in every case. Government fees, stamp duty, contribution/share capital and professional fees vary. More importantly, founders should compare ongoing compliance costs rather than only incorporation costs.

3. Can an LLP get Startup India recognition?

Yes. Eligible LLPs can apply for Startup India recognition, subject to the applicable eligibility requirements.

4. Can a Private Limited Company get Startup India recognition?

Yes. A Private Limited Company can apply for DPIIT Startup recognition if it satisfies the applicable conditions.

5. Can an LLP raise investment?

An LLP can bring in additional partners or restructure partner interests subject to the LLP agreement and applicable laws. However, conventional angel and venture-capital equity investment is generally structured more naturally through a company with shares.

6. How long does company registration take in India?

There is no single guaranteed government timeline applicable to every incorporation. Processing depends on name approval, documentation, filing accuracy, MCA processing and whether clarification or resubmission is required.

7. Do I need GST immediately after registering a company?

Not necessarily. GST registration depends on the nature of the business, turnover and other compulsory-registration provisions. Incorporation and GST registration are separate matters.

8. Is an LLP suitable for a SaaS startup?

It can be, particularly for a bootstrapped or founder-funded SaaS business. If the SaaS startup expects substantial equity funding, investor participation or employee equity, a Private Limited structure may be more appropriate.

9. Can I convert an LLP into a Private Limited Company later?

There are legal routes for restructuring/conversion in certain circumstances, but the process, tax implications and eligibility should be evaluated before assuming that conversion will be simple or cost-free.

10. Do LLPs have annual compliance?

Yes. LLPs have continuing statutory filing obligations. MCA provides annual filing mechanisms including Form 11 and Form 8.

11. Do Private Limited Companies have more compliance than LLPs?

Generally, yes. A Private Limited Company has a more formal corporate governance framework and additional filing and record-keeping requirements.

12. Should a two-founder technology startup choose an LLP?

It depends on the business plan. If the founders are building a bootstrapped service business, LLP may work well. If they intend to raise equity investment and build a scalable product company, Private Limited is usually the more practical starting point.

Final Verdict: LLP or Private Limited?

For most funding-oriented technology startups in India, a Private Limited Company is usually the better long-term structure.

For a bootstrapped technology services, consulting or closely held business, an LLP can be a sensible alternative.

The decision should come down to four things:

Funding + ownership + compliance + growth plans.

Do not choose a structure only because the registration price is lower.

If your business is still at the idea stage, spend some time deciding how the founders will own the business and where you expect the company to be in three to five years. Changing the structure later can involve additional professional, legal, tax and compliance work.

If you want to register your company in India, FilingPoint can help you complete the incorporation process and understand the registrations and compliance requirements relevant to your business.

Introduction

Running a company involves more than serving customers and growing sales. Every registered company also has yearly compliance duties. Company Annual Return Filing is one of the key ROC requirements in India. A company may need to file forms such as AOC-4 and MGT-7 with the Ministry of Corporate Affairs (MCA). These filings keep important company information and financial records updated with the ROC. Missing or delaying these filings can lead to additional fees and compliance issues. This is why completing your annual ROC filing correctly and on time is important for your company.

What Is Company Annual Return Filing?

Company Annual Return Filing is the yearly process of submitting important company information to the Registrar of Companies (ROC) through the MCA portal. It gives the government an updated view of your company’s financial and business records. This filing is not only for companies with high turnover. Depending on the type of company and applicable rules, even a company with little or no business activity may have annual filing responsibilities.

Think of annual ROC filing as your company’s yearly compliance update. It tells the ROC, “This is the current position of our company.”For business owners, this is important because keeping company records updated can make future compliance work much easier. It can also help when the company needs changes such as adding directors, transferring shares, raising capital, or carrying out other corporate actions.FilingPoint makes ROC annual filing simple, clear, and stress-free for businesses.Get expert support for AOC-4, MGT-7, and other annual compliance filings.

Who Needs to File AOC-4 and MGT-7?

Most registered companies in India have annual ROC filing responsibilities. The exact forms and requirements depend on the company’s type, size, and applicable rules. Private Limited Companies, Public Companies, OPCs, and other eligible companies may have to submit annual documents to the ROC. It is important to check the correct form before filing. Using the wrong form or missing a required filing can create compliance problems. A professional review can help business owners understand what their company needs to file each year.

Companies That May Have Annual Filing Requirements

  • Private Limited Companies
  • Public Limited Companies
  • One Person Companies (OPCs)
  • Small Companies
  • Other companies covered under the Companies Act
  • Companies with active business operations
  • Companies with limited or no business activity, where filing is applicable

The applicable annual return form can also depend on the company category. For example, eligible OPCs and small companies may use MGT-7A instead of MGT-7. AOC-4 is generally used for filing financial statements and related documents. The filing requirements should be checked based on the company’s current status and applicable MCA rules. This is important because every company does not have exactly the same compliance requirements. Getting the form and filing requirement right from the beginning can help avoid unnecessary corrections, delays, and additional costs.

Documents Required for AOC-4 Filing

AOC-4 filing is connected with the company’s financial statements. Before preparing the form, the company should keep its financial records and supporting documents ready. The accounts should be properly prepared and approved as required. Depending on the company and its circumstances, additional documents may also be required. Having all documents ready before starting the filing makes the process smoother. It also gives the filing team enough information to check whether the financial figures and company details are consistent before submitting the form to the MCA.

Common Documents and Information Required

  • Balance Sheet
  • Statement of Profit and Loss
  • Cash Flow Statement, where applicable
  • Notes to Accounts
  • Board’s Report
  • Auditor’s Report
  • Financial statements
  • AOC-1, where applicable
  • CIN and company details
  • Registered office details
  • Details required for applicable attachments
  • Digital Signature Certificate (DSC) of the authorised person, where applicable

The exact documents can vary based on the company’s structure and applicable requirements. Financial statements should be checked carefully before filing because errors in figures, dates, or company information can create problems later. Missing attachments can also result in the form being rejected or requiring further action. This is why document verification is an important part of AOC-4 filing. A good compliance process does not simply upload documents. It checks the information first and then proceeds with the MCA filing.

AOC-4 vs MGT-7 – Comparison Table

FeatureAOC-4MGT-7
Main purposeFiling financial statementsFiling annual return
Main focusFinancial informationCompany and ownership information
IncludesBalance sheet, profit & loss and applicable financial documentsDirectors, members, shareholding and other company details
Filed withRegistrar of Companies (ROC)Registrar of Companies (ROC)
Filing platformMCA portalMCA portal
Applies toCompanies required to file financial statementsCompanies required to file annual returns
Main benefitKeeps financial records updated with ROCKeeps annual company information updated with ROC
Filing timelineGenerally within 30 days of AGMGenerally within 60 days of AGM
Professional helpUseful for accurate preparation and filingUseful for checking company and shareholder information

Documents and Information Required for MGT-7

MGT-7 focuses on the company’s annual return rather than only its financial statements. The form requires important information about the company and its activities during the relevant financial year. Before filing, the company should collect its basic corporate records and check whether the information matches its MCA records. Details relating to directors, members, shareholding and meetings should be reviewed carefully. Proper preparation helps reduce mistakes and makes the annual return filing process easier for both the company and the professional handling the ROC compliance.

Common Information Required for MGT-7

  • Corporate Identity Number (CIN)
  • Company name
  • Registered office address
  • Company email address
  • Details of directors
  • Details of members
  • Shareholding details
  • Changes in shareholding, where applicable
  • Details of company meetings
  • Details of directors’ meetings
  • Details of members’ meetings
  • Details of changes during the year
  • Other applicable annual return information

MGT-7 should be prepared using accurate and updated company records. Even a small mismatch in shareholding, director details, registered office information, or other corporate records can create unnecessary filing issues. Before submission, the information should be reviewed against the company’s documents and MCA records. This simple verification step can save time later. If the company has made changes during the year, those changes should also be considered while preparing the annual return and related compliance documents.

Step-by-Step Company Annual Return Filing Process

Step 1 – Collect Company Records

Collect the company’s financial statements, annual return information, director details, shareholder information, registered office details, previous filings, and other documents required for the applicable ROC forms.

Step 2 – Finalise Financial Statements

Prepare and finalise the company’s financial statements according to applicable accounting and legal requirements. Ensure the figures, dates, company details, and supporting records are properly checked.

Step 3 – Complete Audit Requirements

Where an audit is applicable, complete the audit process and obtain the required auditor’s report and related documents before proceeding with the annual ROC filing.

Step 4 – Conduct the AGM

The company should conduct its Annual General Meeting according to the applicable requirements. The financial statements and other required matters are considered during the AGM.

Step 5 – Prepare AOC-4

Prepare AOC-4 using the company’s approved financial statements and required information. Check every important figure and attachment carefully before moving to the submission stage.

Step 6 – Prepare MGT-7 or MGT-7A

Prepare the applicable annual return form using updated company, director, member, shareholding, meeting, and other required information for the relevant financial year.

Step 7 – Verify Company Details

Compare the information in the forms with the company’s records and previous MCA filings. Correct mismatches before submission to reduce the chance of filing problems.

Step 8 – Apply Digital Signature

The required authorised person and professional should complete the applicable digital signature and certification requirements before the forms are submitted through the MCA system.

Step 9 – Submit Forms on MCA

Upload the completed forms and required attachments through the MCA portal. Review the information once more before submitting to avoid simple errors or missing documents.

Step 10 – Pay Applicable Fees

Pay the applicable government filing fees and any additional fees, if applicable. The amount can depend on the filing circumstances and whether the filing is delayed.

Step 11 – Check Filing Status

After submission, keep the generated acknowledgement and SRN safely. Check the MCA filing status to confirm whether the forms have been successfully processed.

Step 12 – Keep Records Safely

Keep copies of the filed forms, acknowledgements, financial statements, annual return and supporting documents. Proper records make future ROC compliance and company-related work easier.

What Happens If You Delay ROC Annual Filing?

ROC annual filing should not be treated as a task that can be postponed without checking the consequences. A delay in AOC-4 or MGT-7 filing may result in additional filing fees and can create a compliance backlog. It may also make future company-related work more difficult. Business owners may need updated ROC records for banking, investments, due diligence, or corporate changes. Therefore, completing annual filing within the applicable time is a smart way to keep your company’s compliance records in order.

Problems That May Arise From Delayed Filing

  • Additional government filing fees may apply.
  • Pending ROC compliance can build up.
  • Future company changes may become more difficult.
  • Due diligence may identify pending filings.
  • Investors or lenders may ask for updated compliance records.
  • Directors may face additional compliance concerns.
  • Old pending filings can increase the overall compliance burden.
  • Correcting mistakes later may take additional time.
  • The company may need professional help to clear accumulated filings.

A delayed filing does not simply mean completing the same work a few days later. Depending on the situation, additional fees, documents, explanations, or corrective actions may be required. The longer compliance remains pending, the more difficult it can become to manage company records. Business owners should therefore keep a yearly compliance calendar and start the process early. If you are unsure about your filing status, checking the company’s MCA records and previous annual filings can be a useful first step.

Common Mistakes Companies Make During AOC-4 & MGT-7 Filing

Many companies do not intentionally ignore ROC compliance. Mistakes often happen because the filing involves several documents, figures, company details, and deadlines. A small mismatch can create unnecessary problems. Common examples include entering incorrect financial figures, providing outdated director or shareholder information, missing an attachment, or preparing the wrong annual return form. Some companies also wait until the deadline and then rush the filing. This can increase the chance of mistakes. A proper review before submission can make the process smoother and help prevent avoidable compliance issues.

Common mistakes include:

  • Entering incorrect financial figures.
  • Using outdated company information.
  • Incorrect director details.
  • Incorrect shareholder or shareholding information.
  • Missing required attachments.
  • Selecting an incorrect form.
  • Not checking previous ROC filings.
  • Ignoring changes made during the financial year.
  • DSC-related problems during filing.
  • Filing close to the deadline.
  • Not checking the final form before submission.
  • Failing to keep filing acknowledgements safely.

These mistakes may look small, but they can take additional time to correct. A careful filing process should therefore include document collection, data verification, form preparation, attachment checking, digital signature verification, and final review. The goal is not only to submit the form but to submit accurate information. Companies should also keep copies of their filed documents and acknowledgements for future reference. If you are not comfortable handling MCA forms yourself, professional ROC filing support can make the yearly process easier and more organised.

Your ROC Filing Journey With FilingPoint

START

  │

  ▼

Contact FilingPoint

  │

  ▼

Share Company Details

  │

  ▼

Submit Required Documents

  │

  ▼

Document & Data Review

  │

  ▼

AOC-4 Preparation

  │

  ▼

MGT-7 / MGT-7A Preparation

  │

  ▼

Final Verification

  │

  ▼

MCA Filing

  │

  ▼

Filing Acknowledgement

  │

  ▼

ROC Compliance Completed

Frequently Asked Questions

1. What is Company Annual Return Filing?

Company Annual Return Filing is the yearly compliance process where a company submits required financial, ownership, management, and other company information to the ROC through the MCA portal.

2. What is AOC-4 filing?

AOC-4 is generally used to file a company’s financial statements and related documents with the Registrar of Companies through the MCA system, subject to applicable requirements.

3. What is MGT-7 filing?

MGT-7 is an annual return form used to report important company information, including details about the company, directors, members, shareholding, and other applicable information.

4. Is AOC-4 mandatory for a Private Limited Company?

A Private Limited Company generally has financial statement filing obligations. The applicable form and requirements should be checked based on the company’s specific circumstances and current rules.

5. Is MGT-7 mandatory for a Private Limited Company?

Applicable companies generally need to file their annual return with the ROC. The correct annual return form depends on the company’s category and applicable MCA requirements.

6. What is the difference between AOC-4 and MGT-7?

AOC-4 mainly deals with financial statements, while MGT-7 mainly deals with annual company information, including directors, members, shareholding, and other applicable corporate details.

7. What documents are required for AOC-4 filing?

Common documents include financial statements, Board’s Report, Auditor’s Report, notes to accounts, and other applicable documents. Exact requirements can vary according to the company.

8. What documents are required for MGT-7 filing?

MGT-7 generally requires company details, director information, member details, shareholding information, meeting details, and other applicable annual return information for the relevant year.

9. When should AOC-4 be filed?

The applicable AOC-4 filing deadline is generally linked to the company’s AGM. The exact deadline should be checked according to the applicable Companies Act requirements.

10. When should MGT-7 be filed?

The applicable MGT-7 filing deadline is generally linked to the company’s AGM. The exact deadline should be checked based on the company’s circumstances and current rules.

11. What happens if ROC annual filing is delayed?

Delayed ROC filing can result in additional fees and compliance issues. Pending filings may also create difficulties when the company later needs other corporate or regulatory services.

12. Can FilingPoint handle my complete ROC annual filing?

Yes. FilingPoint can guide you through document collection, information checking, applicable form preparation, ROC filing, and acknowledgement, helping make your annual compliance process simpler.

Why Choose FilingPoint for ROC Annual Filing?

Choosing the right professional for your ROC filing can save time and reduce compliance stress. FilingPoint makes the annual filing process simple by guiding you from document collection to final submission. Our team helps you understand the required documents, checks important company information, and supports the preparation of applicable ROC forms. We focus on making the process clear instead of making you deal with complicated compliance terms. Whether you need AOC-4, MGT-7, or related ROC support, FilingPoint provides a convenient and organised filing experience for your company.

Conclusion

Company Annual Return Filing is an important yearly responsibility for maintaining proper ROC compliance. AOC-4 and MGT-7 serve different purposes, so submitting the correct information and documents is essential. Delaying the filing can also lead to additional fees and compliance difficulties. Instead of waiting until the deadline, start your annual filing early and keep your company records updated. With the right professional support, the process can be simple and stress-free. FilingPoint helps businesses manage their ROC annual filing with clear guidance, document support, and an organised process from beginning to
completion.


Introduction

Annual ROC filing is an important duty for companies in India. Every year, companies must submit certain documents and details to the Ministry of Corporate Affairs (MCA). These filings help keep company records updated and show that the business is following company law. Many business owners delay ROC filing because they think it is needed only when the company makes a profit. This is not always true. Understanding the forms, due dates, documents, and process can help you avoid late fees and compliance problems. This guide explains annual ROC filing in simple words.

What Is Annual ROC Filing?

Annual ROC filing means submitting a company’s yearly financial and business information to the Registrar of Companies (ROC) through the Ministry of Corporate Affairs (MCA). It is a regular compliance requirement for companies registered in India. The company needs to provide details such as its financial statements, directors, shareholders, share capital, and other required information. The exact forms and documents can depend on the type and size of the company. Even a company with little or no business may still have annual filing requirements. Filing these documents on time helps keep the company’s MCA records updated and reduces the risk of additional fees and other compliance issues.

For business owners who are not sure which forms to file or what documents are needed, FilingPoint can help check the applicable requirements and assist with the ROC filing process. FilingPoint provides simple and professional ROC filing support for companies.

Is ROC Filing Mandatory for Every Company?

Yes, annual ROC filing is generally mandatory for registered companies in India. The requirement does not depend only on whether the company made a profit. A company may still need to complete its annual compliance even if it has not started business or has had no income during the year. However, the exact forms and requirements can differ based on the company’s type, size, and applicable rules. Before filing, it is important to check the company’s current compliance position and identify the forms that apply to it.

Common company types that may have annual ROC filing requirements include:

  • Private Limited Company
  • Public Limited Company
  • One Person Company (OPC)
  • Small Company
  • Section 8 Company
  • Other companies registered under the Companies Act

The filing process can be confusing if you are doing it for the first time. You need to check financial statements, annual return details, directors, shareholders, AGM details, and other information before submitting the forms. Missing a requirement can lead to additional fees or compliance issues. FilingPoint can help you understand the applicable ROC requirements and complete your annual filing with proper document support.

Main ROC Forms for Annual Filing

Different companies may need different ROC forms. The two important annual filing forms are generally AOC-4 and MGT-7 or MGT-7A. AOC-4 is used for filing financial statements with the ROC. MGT-7 is used for filing the annual return for companies to which it applies. Eligible One Person Companies and small companies generally use MGT-7A for their annual return. Some companies may also come under XBRL filing requirements. The correct form depends on the company’s structure and applicable rules, so it is important to check before filing.

Common ROC Annual Filing Forms

  • AOC-4 – Filing of financial statements
  • MGT-7 – Annual return for applicable companies
  • MGT-7A – Annual return for eligible OPCs and small companies
  • AOC-4 XBRL – Financial statement filing for companies covered by XBRL requirements
  • Other applicable forms – Certain companies may have additional filing requirements

Using the correct form is important because each form asks for different company information. Before submitting, the financial statements and annual return details should be checked carefully. Errors in company names, directors, shareholders, financial figures, or other details can create problems. FilingPoint can review the applicable forms and help prepare your annual ROC filing correctly and smoothly.

ROC Filing Due Dates

ROC filing has specific due dates, and companies should plan their compliance before the deadline. Generally, the due date for AOC-4 is within 30 days from the date of the Annual General Meeting (AGM). The annual return in MGT-7 or MGT-7A is generally filed within 60 days from the date of the AGM. The AGM itself also has a separate legal deadline. These timelines can vary in certain situations, so the company should check the rules that apply to its specific case.

Common Annual ROC Filing Timelines

  • AOC-4: Generally within 30 days from the AGM
  • MGT-7: Generally within 60 days from the AGM
  • MGT-7A: Generally within 60 days from the AGM
  • AGM: Must also be conducted within the applicable legal timeline
  • Late filing: May result in additional fees and, where applicable, penalties

Do not wait until the final day to start the filing. Financial statements, audit work, Board’s Report, AGM records, DSC, and other documents may need to be ready first. Starting early gives you time to correct mistakes and collect missing documents. FilingPoint can help you plan and complete your annual ROC filing before the applicable due dates, making the process easier for your business.

Documents Required for Annual ROC Filing

Annual ROC filing needs different documents and company details. The documents help the ROC understand the company’s financial position and yearly activities. The exact documents can change based on the company type and applicable rules. Before starting the filing, the company should collect and check all required records. This can help avoid delays and mistakes during MCA submission. Properly prepared documents also make it easier to complete the annual forms correctly and keep the company’s compliance records in order.

Common Documents Required

  • Audited Balance Sheet
  • Profit and Loss Statement
  • Cash Flow Statement, where applicable
  • Notes to Accounts
  • Auditor’s Report
  • Board’s Report
  • Details of directors
  • Details of shareholders
  • Share capital details
  • Registered office details
  • AGM details
  • Financial year details
  • Digital Signature Certificate (DSC)
  • Other documents, where applicable

Before filing, all information should be checked carefully. The names of directors, shareholders, share capital, financial figures, and other company details should match the company’s records. Missing or incorrect information can cause filing errors or require corrections later. The documents also depend on the company’s size, structure, and legal requirements. FilingPoint can help you identify the required documents and support you in preparing them for annual ROC filing.

Step-by-Step Annual ROC Filing Process

Step 1: Prepare Books of Accounts

The company should keep its books of accounts updated for the financial year. All business transactions, income, expenses, assets, and liabilities should be properly recorded.

Step 2: Prepare Financial Statements

Prepare the company’s Balance Sheet, Profit and Loss Statement, and other applicable financial statements using the completed books of accounts.

Step 3: Complete Statutory Audit

Where audit is required, the company’s financial statements must be reviewed by the appointed statutory auditor before the annual ROC filing process continues.

Step 4: Prepare Board’s Report

The company prepares its Board’s Report with the required information about company performance, directors, financial matters, and other applicable compliance details.

Step 5: Hold the AGM

The company conducts its Annual General Meeting within the applicable legal timeline and approves the financial statements and other required matters.

Step 6: Prepare AOC-4

AOC-4 is prepared with the company’s financial statement information and required attachments before it is submitted to the MCA.

Step 7: File AOC-4

The completed AOC-4 is submitted electronically through the MCA portal with the required digital signatures and applicable filing fees.

Step 8: Prepare Annual Return

The company prepares MGT-7 or MGT-7A, depending on its type and eligibility, using the required company and annual return information.

Step 9: File Annual Return

The completed annual return is submitted on the MCA portal after checking all information, attachments, signatures, and applicable filing requirements.

Step 10: Save Filing Proof

After successful submission, save the SRN, acknowledgement, challan, and submitted documents for future reference and company compliance records.

ROC Filing for Private Limited Companies

Private Limited Companies registered in India generally have annual ROC compliance requirements. They need to submit their financial statements and annual return to the ROC within the applicable time limits. AOC-4 is generally used for filing financial statements, while MGT-7 is generally used for the annual return. The company must also maintain proper books of accounts, complete the required audit, prepare the Board’s Report, and conduct its AGM as required. Company information such as directors, shareholders, share capital, registered office, and financial details should be checked before filing. Even if a Private Limited Company has not made a profit, it may still have annual ROC filing obligations.

 The exact requirements can depend on the company’s size, status, and applicable rules. Delaying these filings may result in additional fees and other compliance issues. It is better to prepare the documents early and review the information before submitting the forms.FilingPoint can help Private Limited Companies with document preparation, form checking, and annual ROC filing support.Contact FilingPoint to make your annual ROC compliance simple and easier to manage.

ROC Filing for OPC and Small Companies

One Person Companies (OPCs) and eligible small companies also have annual ROC compliance requirements. Their annual return requirements can be simpler in certain cases. Eligible OPCs and small companies generally use MGT-7A for their annual return, while AOC-4 is generally used for filing financial statements. The company must still maintain proper accounts and complete other applicable requirements. The financial statements should be prepared correctly, and an audit should be completed where required. The company should also check its directors, share capital, registered office, and other details before filing. Small companies should not assume that being a small business means they do not need ROC filing. Even when there is little business activity, applicable annual compliance should be completed.

The exact requirements depend on whether the company meets the legal conditions for a small company or other applicable category. Checking the company’s status before filing helps avoid using the wrong form.FilingPoint can help OPCs and eligible small companies understand their ROC requirements and complete the applicable filings.
Choose FilingPoint for simple, professional, and timely annual ROC filing support.

ROC Filing Checklist

Before submitting annual ROC forms, it is useful to follow a simple checklist. This helps the company make sure that important documents and information are ready. A small mistake or missing document can delay the filing process. The directors should review the company’s records before the forms are submitted. Financial statements, annual return details, AGM information, and other required documents should be checked carefully. A proper checklist also makes the annual compliance process easier to manage every year.

Annual ROC Filing Checklist

  • ☐ Books of accounts completed
  • ☐ Financial statements prepared
  • ☐ Statutory audit completed, where applicable
  • ☐ Auditor’s Report ready
  • ☐ Board’s Report prepared
  • ☐ AGM completed
  • ☐ Director details checked
  • ☐ Shareholder details checked
  • ☐ Share capital details checked
  • ☐ Registered office details checked
  • ☐ DSC is active
  • ☐ AOC-4 prepared
  • ☐ MGT-7/MGT-7A prepared
  • ☐ Required attachments checked
  • ☐ MCA filing completed
  • ☐ SRN and acknowledgement saved

Once the checklist is complete, the company can move ahead with the MCA filing. It is important to compare the information in the forms with the company’s official records before submission. This reduces the chance of errors and unnecessary corrections. FilingPoint can assist you with the ROC filing checklist, document review, form preparation, and MCA submission process.

What Happens If You Do Not File ROC Returns?

Not filing your annual ROC returns on time can create compliance problems for your company. The company may have to pay additional filing fees for delayed forms. Continued non-compliance can also lead to penalties under the Companies Act, depending on the form and situation. It may become harder to keep your company records in good order. Long delays can also create problems when you need to complete other company-related work. For example, investors, banks, or other parties may ask for updated company records.

Directors should therefore take annual ROC filing seriously, even when the company has very little business activity. The exact consequences depend on the type of company, form, and period of delay.FilingPoint can help you check pending ROC filings and complete the applicable annual compliance requirements.
Get professional ROC filing support from FilingPoint and avoid unnecessary compliance stress.

ROC Filing Penalties and Additional Fees

Late ROC filing can increase the cost of company compliance. When a company files certain forms after the prescribed due date, additional fees may apply. The amount can depend on the form and the number of days the filing is delayed. In some situations, separate penalties may also apply under the Companies Act. This is why companies should not wait until a filing becomes overdue. If several years of filings are pending, the total cost and compliance work can become more difficult. Before making a filing, the company should check the latest MCA rules and the fees applicable to its specific situation.

 Companies should also keep their financial statements, annual returns, and other documents ready before the due date. Filing on time is usually easier and less costly than correcting years of pending compliance.FilingPoint can help review your company’s ROC status and guide you through applicable filing requirements and fees.Choose FilingPoint for professional support in completing your annual ROC compliance on time.

ROC Filing vs Income Tax Filing Compression Table

ROC filing and Income Tax filing are two different compliance requirements. Many business owners think that completing one filing means the other is also completed. This is not correct.

PointROC FilingIncome Tax Filing
Filed withMinistry of Corporate Affairs / ROCIncome Tax Department
Main purposeCompany and corporate complianceReporting income and tax
Common formsAOC-4, MGT-7/MGT-7AApplicable ITR
Main informationFinancial statements and company detailsIncome, deductions, tax and related details
Applies toCompanies based on applicable rulesTaxpayers based on applicable rules
Filing deadlineDepends on the applicable ROC form and AGMDepends on the applicable ITR and taxpayer
Late filingAdditional fees/penalties may applyInterest, late fee or penalties may apply

Important: Completing your Income Tax return does not replace your ROC filing requirement. Both should be checked separately.

Why Should You Not Delay ROC Filing?

Delaying ROC filing can make a simple annual compliance task more difficult. When you wait until the last moment, you may find missing documents, expired DSCs, incorrect company details, or other filing issues. You may also have less time to correct mistakes before the deadline. Timely filing helps keep your company records updated and makes future compliance easier. It also gives directors peace of mind because the annual filing is completed within the applicable timeline.

Reasons to File on Time

  • Avoid unnecessary additional filing fees
  • Reduce the risk of compliance problems
  • Keep MCA company records updated
  • Get enough time to correct errors
  • Keep financial documents organised
  • Make future filings easier
  • Maintain better compliance records
  • Reduce last-minute pressure
  • Avoid accumulation of pending filings
  • Make company information easier to verify

Early preparation also helps you identify problems before they become urgent. Your accounts, audit, Board’s Report, AGM records, DSC, and annual forms can be checked in advance. This gives you a smoother filing process and reduces avoidable delays. If you are unsure about your company’s ROC due date or pending filings, professional assistance can help you understand what needs to be completed.

Frequently Asked Questions

1. What is annual ROC filing?

Annual ROC filing is the process of submitting required company information and financial documents to the Registrar of Companies through the MCA within the applicable legal timeline.

2. Is ROC filing mandatory for Private Limited Companies?

Yes. Private Limited Companies generally have annual ROC filing requirements, even when the company has little business activity or does not make a profit.

3. Is ROC filing required if my company has no business?

Generally, yes. A company may still have annual compliance requirements even when there is no business activity or income during the financial year.

4. What is AOC-4?

AOC-4 is generally used by companies to file their financial statements and applicable attachments with the Registrar of Companies through the MCA.

5. What is MGT-7?

MGT-7 is the annual return form generally used by companies that are required to file their annual return using this form.

6. What is MGT-7A?

MGT-7A is a simplified annual return form generally applicable to One Person Companies and eligible small companies under the applicable rules.

7. What happens if ROC filing is late?

Late filing can result in additional fees and, depending on the circumstances, penalties or other compliance consequences under applicable company law.

8. Is ROC filing the same as Income Tax filing?

No. ROC filing is related to corporate compliance with the MCA, while Income Tax filing deals with income and tax-related requirements.

9. Can I file ROC returns myself?

Yes, a company can manage its own filing if it understands the applicable requirements and has the necessary information, documents, digital signatures, and MCA access.

10. Does an OPC need annual ROC filing?

Yes. An OPC generally has annual ROC compliance requirements. Eligible OPCs generally use MGT-7A for their annual return.

Why Choose FilingPoint for Annual ROC Filing?

Annual ROC filing can feel difficult when you are not familiar with MCA forms and compliance rules. FilingPoint helps make the process simple. We can assist with understanding applicable forms, preparing required information, checking documents, and supporting the MCA filing process. Our goal is to reduce confusion and help business owners complete their annual compliance properly. Whether you operate a Private Limited Company, OPC, or eligible small company, FilingPoint can help you understand the applicable requirements. With clear communication and professional support, you can spend less time worrying about ROC compliance and more time focusing on your business.

Conclusion

Annual ROC filing is an important responsibility for companies registered in India. It helps keep company information and financial records updated with the MCA. Companies should understand which forms apply to them, prepare the required documents, and complete filing within the applicable deadlines. Delaying compliance can lead to additional fees and other problems. If you are unsure about your company’s ROC requirements, getting professional support can make the process easier. FilingPoint can help you manage your annual ROC filing with simple guidance and professional support. Contact FilingPoint today and take the next step toward keeping your company compliance on track.

Introduction

A media company spends a lot of time building its name, logo, and brand. People may know the company through news, videos, films, podcasts, social media, or websites. As the brand grows, protecting it becomes important. Trademark registration helps a media company protect its unique brand identity and build trust with its audience. It also gives the company stronger rights over its registered brand. Registering early can help avoid problems later and support smooth business growth.FilingPoint can help media companies understand the trademark process.Get professional support from FilingPoint to protect your media brand.

What Is a Trademark for a Media Company?

A trademark is a name, logo, word, symbol, or other brand identity that helps people identify a business. For a media company, the trademark can be an important part of its public identity. For example, a media company may use one name for its news channel, website, YouTube channel, podcast, or entertainment content.When we build a media brand, we want people to remember our name and identify our content easily. A trademark can help protect that identity. It can also help us create a strong and professional image in the market.

A media company may consider protecting its company brand, channel name, logo, or other important brand elements, depending on its business activities and trademark strategy. Before filing, it is important to check the availability of the proposed mark and choose the suitable trademark class.FilingPoint can guide media companies through trademark search, class selection, documentation, and filing.Choose FilingPoint for simple and professional support with your media trademark registration.

Why Is Trademark Registration Important for a Media Company?

A media company builds its brand through content, marketing, audience trust, and years of work. Once people start recognizing our name, that name becomes valuable to our business. Trademark registration helps us take steps to protect this important brand identity.

Some key benefits include:

  • Protecting our media brand name
  • Helping prevent confusingly similar brand use
  • Building a strong brand identity
  • Supporting audience trust and recognition
  • Giving stronger legal protection to the registered mark
  • Supporting future business expansion
  • Adding value to the company’s intellectual property
  • Helping protect important logos or brand elements

For a growing media company, trademark registration is not only about legal protection. It is also about planning for the future. We may start with a website or YouTube channel today and expand into podcasts, television, publishing, events, or other media services later.By protecting our brand early, we can build our media business with greater confidence and focus on creating good content.

Protect Your Media Brand From Copying

As a media company, our brand name can become one of our biggest assets. We spend time creating content, promoting our name, building an audience, and earning trust. If another business starts using a very similar name or logo, our audience may become confused. This can affect our brand image and business growth.Trademark registration gives us stronger rights over the registered mark and helps us take action if someone uses the mark in a way that creates a legal problem. It can also make our brand ownership clearer.For a new media company, it is better to think about trademark protection at an early stage. Before spending heavily on advertising, social media promotion, websites, videos, or other marketing, we can check whether our proposed brand name is available for registration.

A strong trademark strategy allows us to grow our media brand with confidence. It helps us focus on our audience, content, and future plans while taking steps to protect the identity we are building.FilingPoint can help with trademark search, application filing, and registration support.Protect your growing media brand with simple trademark support from FilingPoint.

Step-by-Step Process for Media Trademark Registration

Step 1 — Choose Your Media Brand

First, we choose the media company name, channel name, logo, podcast name, or other brand we want to protect. The mark should be distinctive and suitable for registration.

Step 2 — Search the Trademark

We search existing trademarks to check whether a similar name or logo is already registered. This helps us identify possible conflicts before submitting our trademark application.

Step 3 — Select the Correct Class

We identify the trademark class that matches our media business activities. The correct class is important because trademark protection applies to the goods or services covered by registration.

Step 4 — Prepare the Documents

We prepare the required applicant details, brand information, identity documents, business details, logo, and other supporting documents needed for the trademark registration application.

Step 5 — File the Application

We submit the trademark application with the required details and applicable government fee. After successful filing, we receive an application number to track its progress.

Step 6 — Trademark Examination

The Trademark Registry examines the application to check whether it meets the applicable requirements. If an examination report raises an objection, we may need to respond.

Step 7 — Handle Opposition

If the trademark is published for opposition, another party may oppose the application within the prescribed period. We may need to respond and defend our trademark application.

Step 8 — Get Trademark Registration

If there are no successful objections or oppositions, the application can proceed toward registration. The registered trademark gives the media company stronger rights over its protected brand.

Step 9 — Maintain Your Trademark

After registration, we should continue using the trademark properly and remember its renewal requirements. This helps us maintain protection and keep our media brand secure.


Protects Your Name Across Media Platforms

A media company may use its brand on many platforms. We may have a website, YouTube channel, podcast, social media pages, news portal, or television program. As our business grows, the same brand name can become well known. Protecting that name becomes important. Trademark registration helps us build stronger rights over our registered brand. It also helps us create one clear identity across different media platforms. This can make it easier for our audience to recognize our genuine company and content.

When we use the same protected brand across our media activities, we can build a stronger and more consistent business identity. This is useful when we add new services or enter new platforms. It also helps us think about our brand as a long-term business asset instead of only a company name.

Trademark Can Become a Valuable Business Asset

When we build a media company, our brand can become more than just a name. Our audience may connect our brand with the quality of our news, videos, entertainment, podcasts, or other content. As this recognition grows, the brand can become an important part of our business value. Trademark registration helps us protect this valuable identity. It can also support our long-term plans when we expand the company, enter partnerships, or develop new media services.

Some ways a strong trademark can support our business include:

  • Strengthening our brand identity
  • Supporting long-term brand ownership
  • Helping build brand recognition
  • Supporting business expansion
  • Adding value to intellectual property
  • Helping during business partnerships
  • Supporting licensing opportunities
  • Creating a stronger professional image

As a media company, we want the value we create to stay connected with our business. A recognizable and protected brand can become an important part of that value. It can support our plans as we grow from a small media project into a larger and trusted media business.

What Can a Media Company Trademark?

A media company can have many different elements that make its brand unique. The company name may be the first thing people remember, but the brand can also include a logo, channel name, tagline, or other distinctive identity used in its business. Protecting the right elements can help us build a stronger brand strategy.

For example, a media company may consider trademark protection for:

  • Media company name
  • News channel name
  • Entertainment brand name
  • YouTube channel brand
  • Podcast name
  • Digital publication name
  • Logo
  • Tagline or slogan
  • Brand names used for media services

Before applying, we should check whether the proposed trademark is available and identify the suitable class based on our actual business activities. This is important because trademark protection is connected to the goods or services covered by the application.Our goal should be to protect the brand elements that are important to our current business and future plans. A well-planned trademark application can give us a better foundation for building a trusted media brand.FilingPoint can guide media companies in selecting and preparing their trademark applications.
With FilingPoint, we can get professional support from search to filing and build our brand with confidence.

Frequently Asked Questions About Media Trademark Registration

1. What is media trademark registration?

Media trademark registration is the process of registering a media company’s brand name, logo, or other eligible mark to get stronger legal protection for the brand.

2. Which trademark class is suitable for a media company?

The suitable class depends on the actual services offered by the media company. News, publishing, entertainment, advertising, and other services may require different classification considerations.

3. Can a new media company register a trademark?

Yes. A new media company can apply for trademark registration if the proposed mark meets the applicable requirements and is available for registration.

4. Can I register my media company name before starting business?

A trademark application can be considered before the business becomes fully operational, depending on the application basis and applicable requirements. Early planning can help protect the proposed brand.

5. How do I check if my media brand name is available?

We can conduct a trademark search before filing. The search helps identify existing identical or similar trademarks that may create problems for the proposed media brand.

6. What documents are needed for media trademark registration?

The required documents depend on the applicant and application. Generally, applicant details, identity information, business details, and the proposed trademark information may be required.

7. How much does media trademark registration cost?

The cost can depend on factors such as the applicant type, number of classes, government fees, and professional service charges. The exact cost should be checked before filing.

8. How long does media trademark registration take?

There is no single fixed timeline. The process can take different amounts of time depending on examination, objections, opposition, and other steps in the trademark process.

9. Can a media company register its brand in more than one class?

Yes. If a media company provides services covered by different classes, it may consider filing in multiple appropriate classes to seek protection for those relevant services.

10. How can FilingPoint help with media trademark registration?

FilingPoint can help media companies with trademark search, suitable class guidance, document preparation, application filing, and support throughout the trademark registration process.

When Should a Media Company Register Its Trademark?

For a media company, timing can be an important part of brand protection. We may spend months creating our company name, logo, website, social media pages, and content. If we plan to build a brand for the long term, it makes sense to think about trademark protection early. Ideally, we should check the proposed name before making a large investment in marketing and promotion.

A media company should consider trademark registration:

  • Before launching a new media brand
  • Before starting a new channel
  • Before spending heavily on marketing
  • Before building a large audience around the name
  • When creating a new media service
  • When expanding into new business areas
  • When developing an important logo or brand identity

Early planning can help us reduce the risk of choosing a name that creates problems later. A trademark search can help us understand whether similar marks already exist. We can then make a more informed decision about our proposed brand.For a growing media company, protecting the brand early can be a smart business step. It allows us to focus on content, audience growth, and expansion while taking steps to protect the identity we are building.

Trademark Registration Process for a Media Company

When we decide to register our media company trademark, we should follow a clear process. The first step is to choose the brand we want to protect. This may be our company name, channel name, logo, or another important brand element. We then check whether a similar trademark already exists.After the search, we identify the suitable trademark class based on our media services. We prepare the required details and documents and submit the trademark application. Once filed, the application goes through the examination process. There may also be an opportunity for others to oppose the application during the relevant stage.

If there are objections, the applicant may need to respond. Once the process is successfully completed, the trademark can be registered. The registered trademark can then become an important part of our brand protection strategy.The process may take time, so proper preparation is useful from the beginning. FilingPoint can support media companies with trademark search, documentation, application filing, and process guidance.
Choose FilingPoint for simple, professional, and reliable trademark registration support.

Comparison table

PointWith Trademark RegistrationWithout Trademark Registration
Brand protectionStronger statutory protection for the registered markProtection may be more limited and harder to enforce
Media brand nameHelps protect the registered name for the covered servicesAnother business may use a similar name
Logo protectionA distinctive logo can be registeredProtection may be less clear
Audience recognitionHelps build a clear and consistent brand identityBrand identity may be easier to copy or confuse
Legal rightsProvides stronger legal rights in relation to the registered goods/servicesRights may depend more on other legal protections
Business valueCan become a valuable business assetBrand value may be harder to protect formally
ExpansionSupports plans to grow the brand across relevant servicesExpansion may carry greater brand-conflict risk
Brand confidenceAllows the company to build its brand with greater confidenceThe company may face more uncertainty
LicensingA registered trademark can be licensed or assignedBrand arrangements may be less straightforward
Long-term planningSupports a structured brand protection strategyBrand protection may be less organised

Common Mistakes Media Companies Should Avoid

A media company works hard to build its brand. We create content, promote our name, connect with audiences, and invest in marketing. Because of this, choosing and protecting the right brand should be taken seriously. Avoiding common mistakes can make our trademark journey smoother and help us build our brand with greater confidence.

Some common mistakes include:

  • Not checking the trademark before choosing a name
  • Selecting a name that is too similar to another brand
  • Waiting too long to consider registration
  • Choosing an unsuitable trademark class
  • Not preparing accurate information
  • Ignoring important trademark notices
  • Not protecting important brand elements
  • Forgetting about trademark renewal requirements

A little planning at the beginning can help us avoid unnecessary problems later. We should check our proposed name carefully and understand what we want to protect. We should also keep our business activities in mind when selecting the appropriate trademark class.For a growing media company, trademark protection should be part of our brand planning. Good preparation can help us build a strong and lasting media identity.

Why Choose FilingPoint for Media Company Trademark Registration?

As a media company, we want the trademark process to be simple and clear. We may already have many things to manage, such as content creation, marketing, audience growth, advertising, and business operations. Professional support can make it easier to understand the trademark process and complete the required steps.

With FilingPoint, media companies can get support for areas such as:

  • Trademark search
  • Trademark class guidance
  • Document preparation
  • Application filing
  • Application status guidance
  • Support during the registration process
  • Clear communication about the process
  • Support for growing media brands

Our goal is not only to register a trademark. We want to build a strong brand that can support our company for years. FilingPoint can help us understand the process in simple language and take the right steps for our brand.Whether we are starting a new media company, launching a digital platform, or growing an existing media brand, proper trademark planning can give us greater confidence. FilingPoint can be a useful partner in protecting the brand we are working hard to build.

Conclusion

A media company puts time, creativity, and money into building its brand. The company name, logo, channel name, and other brand elements can become valuable as the audience grows. Trademark registration helps us take steps to protect this identity and support our future plans. It can also help us build a professional and trusted brand across different media platforms. For a growing media company, protecting the brand early can be a smart business decision.FilingPoint can help make trademark registration simple and clear.
Choose FilingPoint to protect your media brand with professional support.