GSTR-1 - 11-Oct-2026
GSTR-3B - 20-Oct-2026

Trending Articles

Running a private limited company involves more than completing transactions, issuing invoices and preparing financial statements. Companies must also follow statutory governance requirements, including conducting an Annual General Meeting (AGM), maintaining proper records and completing the applicable Registrar of Companies (ROC) filings.

For many founders, AGM compliance becomes particularly important during the annual compliance season. They may know that AOC-4 and MGT-7 or MGT-7A have to be filed, but may not fully understand the meeting that precedes those filings.

An AGM is not simply a formality where directors sign documents. It is a statutory meeting through which shareholders consider the company’s annual business, financial statements and other matters that require their attention.

The Companies Act, 2013 lays down requirements concerning the AGM deadline, notice, place and time of the meeting, quorum, proxies, resolutions and minutes. Failing to follow the applicable requirements can create compliance problems even if the company later submits its annual ROC forms.

This guide explains the AGM process for private limited companies in India, the responsibilities of directors, the documents that should be prepared and the steps to take after the meeting.

What is an Annual General Meeting (AGM)?

An Annual General Meeting is a statutory meeting of a company’s members or shareholders held every year to consider specified company matters.

Under Section 96 of the Companies Act, 2013, every company other than a One Person Company (OPC) must hold an AGM each year, subject to the applicable statutory requirements and exemptions.

The AGM provides shareholders with an opportunity to consider the company’s financial performance, receive information from the Board and take decisions on matters placed before them.

For a typical private limited company, AGM business may include:

  • Consideration and adoption of the audited financial statements.
  • Consideration of the Board’s report and auditor’s report.
  • Declaration of dividend, where applicable.
  • Appointment or reappointment of directors, where applicable.
  • Appointment of auditors or matters relating to their remuneration, where applicable.
  • Other business that is validly included in the meeting notice.

The exact agenda depends on the company’s circumstances and the provisions of the Companies Act and its Articles of Association.

Important: An AGM and an annual ROC filing are two different compliance activities. Holding the meeting does not itself complete the filing obligations. Similarly, filing annual forms should not be treated as a substitute for holding the AGM where the company is legally required to do so.

Which companies must conduct an AGM?

Section 96 applies to every company other than a One Person Company.

This generally includes:

  • Private limited companies.
  • Public limited companies.
  • Listed and unlisted companies, subject to applicable requirements.
  • Companies that have not commenced commercial operations, unless a specific exemption applies.

A company cannot assume that it is exempt from holding an AGM merely because it has not generated revenue, has no active business or has not undertaken significant transactions.

An OPC is treated differently under the Companies Act. It is not required to hold an AGM in the same manner as other companies. Its member-related decisions and records are governed by the applicable provisions for OPCs.

Practical example: A private limited company incorporated in Chennai may have no sales during the financial year. That does not automatically remove its obligation to conduct an AGM. The company should examine its financial-year closing date, incorporation date, applicable exemptions and statutory requirements.

What is the AGM deadline for a private limited company?

The AGM deadline is one of the most important aspects of annual compliance.

Section 96 of the Companies Act, 2013 establishes two main timelines.

First AGM

A company’s first AGM must be held within nine months from the close of its first financial year.

For example, if a company closes its first financial year on 31 March 2026, its first AGM would ordinarily need to be held by 31 December 2026.

The company is not required to hold another AGM in the calendar year of its incorporation if it holds its first AGM within the permitted period.

Subsequent AGMs

For subsequent AGMs, the company must hold the meeting within six months from the close of the financial year.

For a company following the usual 1 April to 31 March financial year, the ordinary deadline is 30 September.

The interval between two AGMs must also not exceed 15 months.

SituationGeneral statutory timeline
First AGMWithin 9 months from the close of the first financial year
Subsequent AGMWithin 6 months from financial-year closing
Maximum gap between two AGMs15 months
Registrar’s extensionUp to 3 months for an AGM other than the first AGM, for special reasons

The Registrar of Companies may extend the time for holding an AGM other than the first AGM by up to three months for special reasons. Do not assume that an extension is automatic. The company must follow the appropriate process and obtain the applicable approval.

Important: An extension for holding an AGM should not be confused with an extension for filing annual forms. Each statutory obligation must be examined separately.

What is the required AGM notice period?

Section 101 of the Companies Act, 2013 generally requires at least 21 clear days’ notice for a general meeting.

The term “clear days” is important. The day on which the notice is served and the day of the meeting are excluded when calculating the notice period.

For example, a company planning to hold an AGM on 30 September should not calculate the notice period by simply counting 21 calendar dates backwards. It should calculate the clear days correctly and allow sufficient time for service.

The notice should specify:

  • The place of the meeting.
  • The date and day.
  • The time.
  • The business to be transacted.
  • Any explanatory statement required under Section 102.
  • Relevant information about the resolutions proposed.

The notice must be sent to the persons entitled to receive it under the Act, including members, directors and auditors, as applicable.

Companies should maintain evidence of dispatch and service. Email delivery records, postal records and other permitted proof may be relevant.

Can an AGM be held at shorter notice?

Yes, subject to the statutory consent requirement.

For an AGM, shorter notice requires consent in writing or through electronic mode from at least 95% of the members entitled to vote at the meeting.

A company should not treat informal conversations or a verbal indication as sufficient proof of consent. Maintain the required written or electronic records.

What is the quorum for a private limited company AGM?

Quorum refers to the minimum number of members who must be personally present for a meeting to proceed validly.

Under Section 103, unless the Articles of Association provide for a larger number, the quorum for a private company is two members personally present.

This requirement is important even when the company has only a small number of shareholders.

For example:

  • A private company with two individual shareholders will ordinarily require both members to be personally present.
  • A private company with several shareholders will generally require at least two members personally present, unless its Articles prescribe a higher quorum.

If the required quorum is not present within half an hour from the scheduled time, the meeting is generally subject to the statutory adjournment rules.

The company should check its Articles of Association before finalising the meeting arrangements. The Articles may prescribe a larger quorum or contain relevant procedural provisions.

Do not confuse quorum with the number of directors. The quorum under Section 103 is based on members, not merely the directors attending.
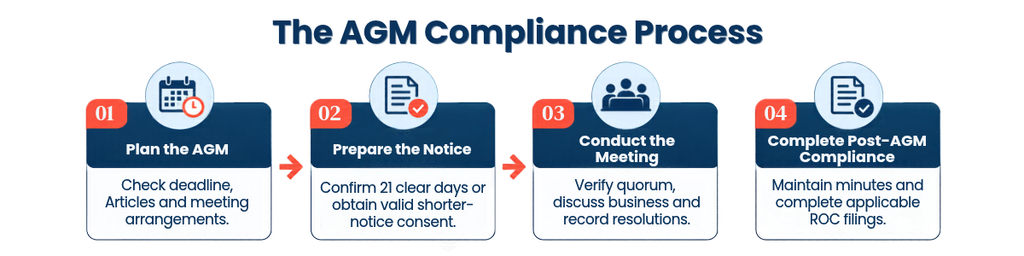
AGM Compliance Process

Where and when can a private company hold its AGM?

Section 96 provides that an AGM must ordinarily be held:

  • During business hours, between 9 a.m. and 6 p.m.
  • On a day that is not a National Holiday.
  • At the registered office or another place within the city, town or village where the registered office is situated.

There is an important provision for unlisted companies: an AGM may be held at any place in India if consent is given in writing or by electronic mode by all members in advance.

This is not a general permission to hold every AGM at any location without conditions. The company must satisfy the applicable statutory requirements.

The company should also check its Articles of Association and the applicable rules before selecting the venue.

Can a private limited company hold an AGM through video conferencing?

The Ministry of Corporate Affairs introduced relaxations during the COVID-19 period to allow companies to conduct AGMs through video conferencing (VC) or other audio-visual means (OAVM).

MCA General Circular No. 03/2025 dated 22 September 2025 continued the facility for companies to conduct AGMs and EGMs through VC or OAVM until further orders, subject to the framework and conditions in the earlier circulars.

This is an important distinction: the circular continues the facility to use VC/OAVM, but it does not extend the statutory time limit for holding the AGM.

Companies using this facility should follow the applicable procedural requirements, including arrangements for participation, attendance, voting, recording and preservation of meeting records.

Do not assume that an ordinary video call automatically qualifies as a compliant AGM. The company must follow the applicable MCA framework and the relevant provisions of the Act and rules.

Before conducting a meeting through VC/OAVM, verify the latest MCA circulars and confirm that the company can meet the prescribed requirements.

What business is generally transacted at an AGM?

The AGM agenda should be prepared according to the company’s circumstances.

Section 102 distinguishes between ordinary business and special business at an AGM.

The ordinary business generally includes:

  1. Consideration of financial statements, the Board’s report and the auditor’s report.
  2. Declaration of dividend, if any.
  3. Appointment of directors in place of those retiring, where applicable.
  4. Appointment of auditors and fixing their remuneration, where applicable.

Other matters are generally treated as special business and may require an explanatory statement.

Not every company will have every item on its AGM agenda. For example, the appointment of directors in place of retiring directors depends on the company’s applicable director-rotation requirements.

What is an explanatory statement?

Section 102 requires an explanatory statement to accompany the notice for special business at a general meeting.

The statement should disclose material facts relevant to the proposed business, including the nature of the concern or interest of directors, managers, key managerial personnel and their relatives, where applicable.

The objective is to give members sufficient information to make an informed decision.

What is the difference between ordinary and special resolutions?

A resolution is a formal decision made by members at a meeting or through another legally permitted process.

Ordinary resolution

An ordinary resolution is passed when votes cast in favour exceed votes cast against, subject to the applicable provisions.

Examples may include ordinary business at an AGM, such as adoption of financial statements.

Special resolution

A special resolution requires the votes in favour to be at least three times the votes against, or the statutory threshold of votes in favour specified under Section 114.

Special resolutions are required for matters where the Companies Act or the company’s Articles prescribe that level of approval.

The notice must clearly identify a proposed special resolution as such.

The company should retain the meeting notice, explanatory statement, voting record and signed minutes to support the decision.

What documents should a company prepare before its AGM?

Preparation should begin well before the meeting date.

The following checklist is a practical starting point. The exact requirements depend on the company and the matters proposed for approval.

Corporate and meeting records

  • Articles of Association.
  • Register of members and relevant shareholder information.
  • Details of directors and auditors.
  • Previous AGM minutes, where relevant.
  • Board meeting records approving the AGM arrangements.

Financial and statutory documents

  • Financial statements for the financial year.
  • Board’s report.
  • Auditor’s report.
  • Relevant schedules and annexures.
  • Draft resolutions and explanatory statements, where required.

Meeting documents

  • AGM notice.
  • Proof of dispatch and service.
  • Attendance register.
  • Proxy forms, where applicable.
  • Authorisations and consents, where applicable.
  • Voting records.
  • Draft minutes.

Practical preparation

  • Confirm the date, time and venue.
  • Verify the quorum requirement.
  • Check whether shorter notice consent is needed.
  • Identify ordinary and special business.
  • Confirm whether any shareholder has a relevant interest in a proposed matter.
  • Arrange the meeting records and statutory registers.

A company should not prepare minutes after the event by guessing what happened. The minutes should reflect the actual proceedings and decisions.
How should AGM minutes be prepared and maintained?

Section 118 requires companies to prepare and maintain minutes of general meetings, Board meetings and other specified proceedings.

Minutes should provide a fair and correct summary of the meeting.

Under the Act, minutes must be entered in the appropriate books within 30 days of the conclusion of the meeting. They should be maintained in accordance with the applicable rules and Secretarial Standards.

For general meetings, the relevant standard is Secretarial Standard-2 (SS-2), issued by the Institute of Company Secretaries of India and approved by the Central Government.

AGM minutes should appropriately record matters such as:

  • Date, time and venue.
  • Details of the chairperson.
  • Attendance and quorum.
  • Confirmation of proper notice.
  • Business considered.
  • Resolutions proposed and passed.
  • Voting results, where applicable.
  • Any relevant proceedings and decisions.

The minutes should be signed and maintained in the prescribed manner.

They are important evidence of the proceedings and decisions of the company. Incomplete or inaccurate minutes can create problems during audits, due diligence, shareholder disputes and future compliance reviews.

What should a company do after completing its AGM?

Holding the AGM is not the final step in annual compliance.

The company must identify the filings and records that follow the meeting.

File financial statements in AOC-4

Under Section 137, the company generally has to file its financial statements and required attachments with the Registrar within 30 days of the AGM.

The applicable form and attachments depend on the company’s circumstances.

If financial statements are not adopted at the AGM or an adjourned AGM, the statutory provisions dealing with filing of unadopted financial statements must be considered.

File annual return in MGT-7 or MGT-7A

Under Section 92, the annual return must generally be filed within 60 days from the date of the AGM.

The applicable form depends on the company’s classification and eligibility.

MGT-7A is prescribed for OPCs and small companies, while other companies generally use MGT-7, subject to the applicable rules.

Update company records

The company should also ensure that its statutory registers, minutes books and other records are updated as required.

Where resolutions require separate filings, the company should check the applicable provisions and filing deadlines.

Important: AOC-4 and MGT-7/MGT-7A are separate forms with separate statutory timelines. Completing one does not complete the other.

What happens if a company fails to hold its AGM?

Failure to hold an AGM within the statutory period can lead to legal consequences.

Section 99 of the Companies Act, 2013 addresses default in complying with Sections 96 to 98.

The company and every officer in default may be subject to the prescribed penalty. The section provides for a penalty of up to ₹1 lakh for the company and up to ₹5,000 for each officer in default.

The consequences should not be confused with late filing fees or penalties under provisions relating to AOC-4 or MGT-7.

There are separate legal requirements for:

  • Failure to hold an AGM.
  • Failure to file financial statements.
  • Failure to file the annual return.
  • Failure to maintain minutes and other statutory records.

A company facing a missed AGM deadline should obtain professional advice promptly. Depending on the circumstances, an application to the Tribunal under Section 97 may be relevant where the AGM has not been held.

Do not assume that filing annual forms later automatically cures the failure to hold the AGM.

Common AGM compliance mistakes made by private limited companies

Mistake 1: Treating the AGM as a paperwork exercise

An AGM is a statutory meeting. The company must follow the applicable notice, quorum, business and record-keeping requirements.

Mistake 2: Calculating the notice period incorrectly

The 21-day requirement refers to clear days. Incorrect calculation can create procedural issues.

Mistake 3: Ignoring the Articles of Association

The Articles may prescribe a larger quorum or additional procedural requirements.

Mistake 4: Assuming that two directors satisfy quorum

The quorum under Section 103 for a private company is based on members personally present, not simply directors attending.

Mistake 5: Preparing minutes much later from memory

Minutes should accurately reflect the meeting and be maintained within the prescribed period.

Mistake 6: Confusing AGM completion with ROC filing completion

A company may conduct its AGM but still miss AOC-4 or MGT-7/MGT-7A deadlines.

Mistake 7: Assuming VC permission extends the AGM deadline

MCA’s VC/OAVM facility and the statutory deadline are separate matters.

AGM compliance checklist for private limited companies

Use this checklist as a practical planning aid.

StageCompliance action
Before the meetingConfirm the statutory AGM deadline
Before the meetingReview the Articles of Association
Before the meetingPrepare financial statements and reports
Before the meetingApprove meeting arrangements and notice
Before the meetingCalculate 21 clear days or obtain valid shorter-notice consent
Before the meetingIdentify ordinary and special business
At the meetingConfirm quorum
At the meetingConduct the business stated in the notice
At the meetingRecord resolutions and voting
After the meetingFinalise and maintain minutes within 30 days
After the meetingFile AOC-4 within the applicable timeline
After the meetingFile MGT-7 or MGT-7A within the applicable timeline
After the meetingUpdate statutory records and complete other applicable filings

Frequently Asked Questions

1. Is an AGM compulsory for a private limited company in India?

Yes. Section 96 of the Companies Act, 2013 generally requires every company other than an OPC to hold an AGM every year.

2. What is the last date for an AGM for a private limited company?

For a company following the financial year ending 31 March, a subsequent AGM is ordinarily due by 30 September. The first AGM is due within nine months from the close of the first financial year.

3. What is the minimum notice period for an AGM?

The general requirement under Section 101 is 21 clear days. Shorter notice is permitted for an AGM with consent from at least 95% of the members entitled to vote.

4. What is the quorum for a private limited company AGM?

Unless the Articles prescribe a larger number, two members personally present constitute the quorum under Section 103.

5. Can a private limited company conduct an AGM online?

MCA General Circular No. 03/2025 continued the facility for AGMs through VC/OAVM until further orders, subject to the applicable framework and conditions.

6. How many days are allowed to prepare AGM minutes?

Minutes must be entered in the appropriate books within 30 days of the conclusion of the meeting, in accordance with Section 118 and applicable rules.

7. What is the deadline for filing AOC-4 after an AGM?

Financial statements are generally required to be filed within 30 days of the AGM under Section 137, subject to the applicable statutory provisions.

8. What is the deadline for filing MGT-7 after an AGM?

The annual return is generally required to be filed within 60 days from the date of the AGM under Section 92.

9. Does a company with no business activity need to hold an AGM?

A private limited company does not automatically become exempt merely because it has no business activity or revenue. It should examine the applicable statutory requirements.

10. What happens if a company does not hold its AGM?

Section 99 provides for penalties for default in complying with the AGM provisions. The company should obtain professional advice and examine the appropriate remedial process.

How FilingPoint can help with annual company compliance

AGM compliance involves more than selecting a date and sending a notice. Companies need to coordinate financial statements, Board approvals, shareholder communication, meeting records and statutory filings.

FilingPoint supports Indian businesses with company compliance and ROC filing services.

If your company needs help reviewing its annual compliance requirements, preparing the necessary documentation or completing applicable ROC filings, consult our experienced professional before the relevant deadlines.

Do not wait until the last date to discover that your meeting records or financial documents are incomplete.
For a small business, an unpaid invoice is more than an accounting entry. It can affect salaries, supplier payments, rent, stock purchases and the ability to accept new orders.

You may have delivered the goods, completed the project or provided the service as agreed. Yet, weeks later, the customer keeps asking for more time. Emails go unanswered, payment dates keep changing and your working capital remains stuck.

If this sounds familiar, you may have options beyond sending another payment reminder.

India’s Micro, Small and Medium Enterprises Development Act, 2006 contains specific provisions for delayed payments to eligible micro and small enterprises. Depending on your eligibility and circumstances, you may be able to pursue the outstanding amount through the applicable Micro and Small Enterprises Facilitation Council process.

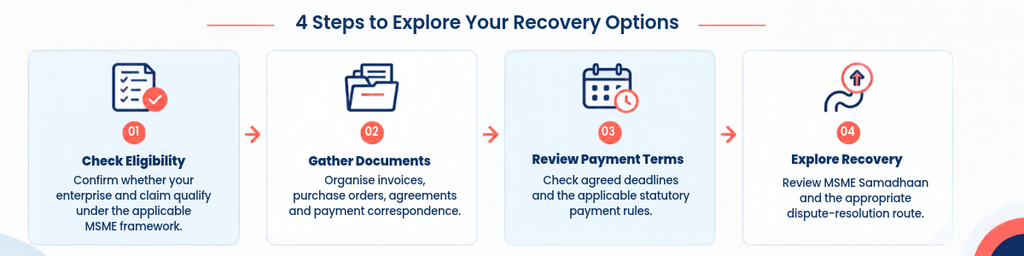
This guide explains the key payment rules, what to check before filing a claim, how MSME Samadhaan and the MSME ODR framework fit into the process, and how to prepare your records.

What Is an MSME Delayed Payment?

An MSME delayed payment occurs when a buyer fails to pay an eligible micro or small enterprise within the applicable payment period for goods supplied or services rendered.

The issue commonly arises when:

  • A customer does not pay an invoice by the agreed date.
  • A buyer repeatedly postpones payment after accepting a delivery.
  • A business completes a service but receives only part of the agreed fee.
  • A supplier’s invoice remains unpaid despite repeated follow-ups.
  • A company disputes an invoice after receiving goods or services.

Not every unpaid invoice automatically qualifies for the special protections under the MSMED Act. The supplier’s eligibility, the timing of registration, the contract, the delivery or service records and the circumstances of the dispute need to be assessed.

Who Can Seek Help for Delayed MSME Payments?

The delayed-payment provisions in Sections 15–24 of the MSMED Act primarily concern eligible micro and small enterprise suppliers.

Your first step is to check whether your business qualifies under the relevant rules.

1. Check your enterprise category

Confirm whether your enterprise falls within the applicable micro or small enterprise classification. A medium enterprise should not assume that the same delayed-payment mechanism is available to it.

2. Check your Udyam registration

Keep your Udyam Registration Certificate and enterprise details ready. The official MSME guidance identifies eligible micro and small enterprises with valid Udyam registration as applicants for the delayed-payment process.

Registration alone, however, does not settle every eligibility question.

3. Check when the registration took effect

This is a critical point. The Supreme Court’s decision in Silpi Industries v. Kerala State Road Transport Corporation explains that MSMED Act benefits do not automatically operate retrospectively for supplies completed before registration.

If you obtained Udyam registration only after entering into the relevant arrangement or completing the supply, do not assume that the registration will cover earlier invoices. The dates and facts need careful review.

4. Check the nature of your business

The applicable rules and official guidance must be reviewed for your activity. In particular, do not assume that every trading activity is eligible simply because the business has an MSME registration.

If you are a trader, distributor, reseller or mixed-activity enterprise, confirm eligibility before relying on the special recovery provisions.

What Is the 45-Day Payment Rule?

Section 15 of the MSMED Act addresses the time allowed for a buyer to pay an eligible micro or small enterprise supplier.

Where the buyer and supplier agree on a payment period in writing, that period cannot exceed 45 days from the day of acceptance or deemed acceptance of the goods or services.

Where there is no written agreement on the payment period, the Act’s definition of the appointed day becomes relevant. It generally refers to the day immediately following the expiry of 15 days from acceptance or deemed acceptance.

The practical takeaway is simple: 45 days is not an automatic grace period that every buyer can add to every invoice. The applicable deadline depends on the agreement and the statutory rules.

Example

Suppose an eligible small manufacturer supplies components to a buyer. The goods are delivered, the delivery records are retained and the buyer accepts the consignment.

If the written agreement provides a 30-day payment period, the agreed period must be considered alongside the Act’s requirements. If the agreement specifies a longer period, the statutory maximum becomes relevant.

This is an illustration only. The actual due date depends on the contract, acceptance date and applicable law.

What Happens When Payment Is Delayed?

Section 16 provides for compound interest with monthly rests at three times the bank rate notified by the Reserve Bank of India, subject to the statutory conditions.

Section 17 addresses the buyer’s liability to pay the amount due together with interest under Section 16.

This does not mean every invoice dispute can be resolved by adding a simple interest percentage to the invoice. The relevant dates, amount outstanding, applicable bank rate and statutory calculation need to be established.

Before calculating interest, assemble the following:

  • Invoice date and invoice value.
  • Date of delivery or service completion.
  • Acceptance or deemed-acceptance records.
  • Contractual payment period.
  • Amounts already paid or adjusted.
  • Relevant RBI bank-rate information for the calculation period.

Avoid publishing or using an arbitrary interest percentage. A calculation should be based on the statutory method and the facts of the case.

MSME Samadhaan: What Does It Do?

MSME Samadhaan is the Ministry of MSME’s online facility for eligible micro and small enterprises to submit information about delayed-payment claims.

It helps suppliers initiate the relevant process by filing information about their claim. The application is routed to the appropriate Micro and Small Enterprises Facilitation Council (MSEFC) for consideration under the applicable procedure.

Important: Submitting an online application is not the same as receiving a payment order or recovering the money. The Council’s role and the steps that follow depend on the applicable procedure and the case.

What Is the MSME ODR Portal?

The Ministry of MSME has also developed an Online Dispute Resolution (ODR) framework for delayed-payment matters.

The framework is designed to support a more digital process for handling disputes. The official scheme guidelines describe features such as guided filing, online negotiation, conciliation or mediation, case management and virtual proceedings.

The relevant route and available features should be checked on the current official portal. Do not assume that every case follows exactly the same sequence or that filing guarantees settlement within a fixed time.

MSME Samadhaan vs MSME ODR

These names are related to delayed-payment support, but they should not be used as if they automatically describe the same procedural step.

PointMSME SamadhaanMSME ODR
Main purposeOnline facility for delayed-payment applicationsDigital dispute-resolution framework
RoleHelps suppliers submit claim informationSupports digital dispute-handling stages
Decision-makingThe relevant MSEFC considers the matterThe applicable process and authority depend on the case stage
What it does not guaranteeImmediate recovery of moneyAutomatic settlement or guaranteed timelines

Before starting, verify the currently applicable filing route and instructions on the official portals.

Documents to Prepare Before Pursuing a Claim

A well-organised record makes it easier to explain what was agreed, what was supplied and what remains unpaid.

Prepare a folder containing the relevant items.

Business and registration records

  • Udyam Registration Certificate.
  • Enterprise details and applicable activity information.
  • Business identification and contact details.

Contract and order records

  • Work order or purchase order.
  • Written agreement, quotation or accepted proposal.
  • Scope of work and payment terms.
  • Relevant email or message confirmations.

Invoice and delivery records

  • Tax invoices or other applicable invoices.
  • Delivery challans and transport records, where relevant.
  • Goods receipt or acceptance records.
  • Service completion reports, timesheets or customer approvals.
  • Correspondence about defects, rework or disputed items.

Payment and follow-up records

  • Bank statements or payment confirmations.
  • Account ledger showing the outstanding balance.
  • Part-payment and credit-note records.
  • Payment reminders and responses.
  • Any written acknowledgement of the amount due.

Keep originals and clear copies. Organise the records invoice by invoice, especially where multiple orders or partial payments are involved.

UDYAM Registration

How to Pursue Outstanding MSME Payments

The appropriate route depends on eligibility and the facts of the dispute. The following workflow can help you prepare.

Step 1: Reconcile the outstanding amount

Confirm which invoices remain unpaid. Deduct payments already received and account for valid credit notes, returns, adjustments and disputed amounts.

Do not claim an amount that your own ledger cannot explain.

Step 2: Review the agreement

Identify the payment terms, delivery requirements, acceptance conditions and dispute-resolution clauses. Check whether the buyer has raised a documented objection.

Step 3: Confirm eligibility

Check your enterprise classification, registration details, registration timing and business activity. Seek professional advice if the facts raise a question about whether the statutory provisions apply.

Step 4: Send a clear written payment demand

State the invoice numbers, dates, outstanding amount and requested payment date. Attach a concise statement of account and relevant records.

A written demand may help clarify the dispute, but it does not replace any required legal step or guarantee payment.

Step 5: Check the official filing process

Review the current instructions on the MSME Samadhaan or MSME ODR portal, as applicable. Confirm the documents, information and filing steps required for your case.

Step 6: Submit accurate information

Use consistent invoice amounts, dates, buyer details and supporting documents. Explain any part-payments or disputed items clearly.

Step 7: Track the case and respond to requests

Retain acknowledgements and case references. Monitor communications and respond to requests from the relevant authority or process administrator.

Step 8: Review the outcome and next steps

If a settlement or order is reached, understand its terms. If the buyer does not comply, obtain advice on the appropriate enforcement or further legal process.

Common Reasons a Delayed-Payment Claim Needs Closer Review

A claim may face complications if:

  • The supplier’s eligibility is unclear.
  • Registration was obtained after the relevant supply.
  • The invoice does not match the purchase order.
  • The buyer disputes delivery, quality or completion.
  • The amount claimed does not account for part-payments.
  • Acceptance records are missing.
  • The supplier cannot establish the contractual payment terms.
  • The claim includes activities or transactions whose eligibility is uncertain.

These issues do not all have the same legal effect. Their significance depends on the evidence and applicable law.

What If the Buyer Disputes the Invoice?

A buyer may say that goods were defective, services were incomplete, a purchase order was not approved or the invoice value is incorrect.

Do not ignore a genuine dispute or assume that the existence of an invoice alone resolves it.

Create a timeline showing the order, delivery, acceptance, complaint and follow-up. Collect inspection reports, customer approvals, photographs where relevant, service records and communications addressing the alleged issue.

Separate the amount that is clearly acknowledged from the portion that remains disputed. If the disagreement concerns contractual interpretation, quality, set-off or jurisdiction, professional advice may be appropriate before filing.

Does GST Registration or GST Filing Recover the Payment?

GST compliance and MSME delayed-payment recovery are different matters.

GST registration, tax invoices and returns may form part of your business records, but GST registration does not by itself guarantee recovery of an unpaid commercial invoice. Similarly, a GST return is not a substitute for following the applicable delayed-payment dispute process.

Make sure your invoices, accounting records and tax records are consistent. If the unpaid invoice creates a separate GST or income-tax question, review that issue under the relevant tax rules rather than assuming the MSME process resolves it.

A Note for Buyers: Why Delayed Payments Matter

Buyers should also take the statutory payment framework seriously.

Eligible micro and small enterprise suppliers may have rights under the MSMED Act. In addition, Section 43B(h) of the Income-tax Act contains a specific deduction-timing provision concerning sums payable to micro and small enterprises covered by Section 15 of the MSMED Act.

The tax treatment depends on the facts and applicable law. Buyers should not assume that an ordinary contractual credit period automatically determines when a deduction is allowed.

Finance teams should maintain supplier classification records, invoice acceptance dates, agreed payment terms and payment evidence, and consult a tax professional about the treatment of outstanding amounts.

Practical Steps to Reduce Future Payment Delays

Recovering an old invoice is important, but preventing future disputes can protect your cash flow.

Before accepting an order

  • Verify the customer’s legal name and billing details.
  • Put scope, price, milestones and payment terms in writing.
  • Confirm who can approve delivery or service completion.
  • Review credit exposure before accepting a large order.

When delivering goods or services

  • Retain delivery and acceptance evidence.
  • Send invoices promptly and to the correct contact.
  • Record any changes to scope or price.
  • Keep written approval for additional work.

When following up

  • Send reminders before and after the due date.
  • Maintain an invoice-wise receivables tracker.
  • Record the buyer’s promised payment date.
  • Escalate unresolved issues through a defined process.

When a customer repeatedly delays

  • Review the customer’s outstanding balance before taking further orders.
  • Consider staged payments or milestone billing where appropriate.
  • Document disputed items promptly.
  • Seek professional advice when the amount or legal issues justify it.

Frequently Asked Questions

1. Can an MSME recover delayed payments in India?

Eligible micro and small enterprises may pursue delayed-payment claims under the MSMED Act, 2006, subject to the applicable conditions and procedure.

2. What is the 45-day payment rule for MSMEs?

Section 15 limits a written payment period to no more than 45 days from acceptance or deemed acceptance of goods or services. The applicable due date must be determined from the agreement and statutory rules.

3. What is MSME Samadhaan?

It is an official online facility for eligible micro and small enterprises to submit delayed-payment applications for consideration through the relevant process.

4. Does filing on MSME Samadhaan guarantee payment?

No. Filing starts or supports the relevant process; it does not guarantee settlement, a favourable decision or immediate recovery.

5. Can I register under Udyam now and claim for an old invoice?

Do not assume that a new registration covers earlier supplies. The Supreme Court has held that MSMED Act benefits do not automatically operate retrospectively for supplies completed before registration. Obtain advice on your facts.

6. Can a service provider pursue delayed payment?

Eligible micro and small service enterprises may fall within the framework, subject to registration, activity and other applicable requirements.

7. Can a trader use the delayed-payment process?

Eligibility should be checked carefully. Do not assume every trading activity qualifies simply because the business has an MSME registration.

8. What documents should I keep?

Commonly relevant records include Udyam details, contracts or purchase orders, invoices, delivery or service-completion evidence, acceptance records, ledger statements and payment correspondence.

9. Is MSME ODR the same as MSME Samadhaan?

They are related to delayed-payment support but serve different functions. Check the current official portal instructions to identify the appropriate route and case stage.

10. Can I claim interest on a delayed MSME payment?

Section 16 provides for compound interest with monthly rests at three times the RBI-notified bank rate, subject to the statutory requirements. The calculation should be based on the actual facts and applicable rate.

Final Checklist Before Taking Action

Before pursuing an unpaid invoice, confirm that you have:

  • Identified the exact outstanding amount.
  • Checked your micro or small enterprise status.
  • Reviewed your registration date and business activity.
  • Located the contract or purchase order.
  • Collected invoices and delivery or completion evidence.
  • Recorded acceptance dates and payment terms.
  • Documented follow-ups and any buyer dispute.
  • Checked the current official filing process.
  • Reviewed the need for professional legal or tax advice.

Need Help Understanding Your Business Compliance?

FilingPoint helps Indian businesses navigate registration and compliance requirements. If your business needs support understanding its registration or compliance position, Email: enquiry@filingpoint.com or contact +91 72999 72500.

Indian companies must complete their annual compliance requirements even when business activity is limited or the company has not generated revenue. However, the type of annual return a company files can depend on its legal classification.

A significant change took effect on 1 December 2025: the Ministry of Corporate Affairs increased the financial thresholds used to determine whether a company qualifies as a small company. The paid-up capital limit increased from ₹4 crore to ₹10 crore, while the turnover limit increased from ₹40 crore to ₹100 crore. The change allows more eligible companies to fall within the small-company definition.  

But does your company automatically qualify because its capital and turnover are below these limits? No. The company must also meet the other requirements under Section 2(85) of the Companies Act, 2013. Certain companies, including holding companies, subsidiary companies and Section 8 companies, are excluded from the definition.

The classification matters because eligible small companies can use the abridged annual return in Form MGT-7A, subject to the applicable rules. Choosing the wrong form, however, can cause filing difficulties and may require professional review.

This guide explains the revised small-company definition, the eligibility conditions, the difference between MGT-7 and MGT-7A, and the practical checks to complete before submitting an annual return.

Quick answer: What is the new small-company limit in India?

From 1 December 2025, the prescribed financial limits for a small company are:

Eligibility measureRevised limit
Paid-up share capitalNot more than ₹10 crore
TurnoverNot more than ₹100 crore

Both financial criteria must be met, and the company must not fall within an excluded category under Section 2(85) of the Companies Act, 2013.

Turnover is assessed with reference to the profit and loss account for the immediately preceding financial year, as stated in the statutory definition. Do not assume that the latest year’s turnover alone settles eligibility without checking the relevant financial-year context and current rules.

What is a small company under the Companies Act, 2013?

A small company is a defined category under Section 2(85) of the Companies Act, 2013. It is not simply a business with a small team, limited customers or modest profits.

The classification is based on the company’s legal status, prescribed financial thresholds and statutory exclusions. A company must be a company other than a public company and meet the relevant paid-up share capital and turnover criteria. It must also be outside the categories specifically excluded by law.

This distinction is important for founders. A startup may have only two directors and a small office but still fail the legal definition. Similarly, a business with a large workforce may potentially meet the financial criteria, although all other conditions must still be checked.

The term “small company” should not be confused with “small enterprise” under the Micro, Small and Medium Enterprises Development framework. The two classifications have different legal purposes and criteria. An enterprise’s Udyam/MSME classification does not automatically establish that it qualifies as a small company under the Companies Act.

What changed on 1 December 2025?

Before the change, the prescribed small-company limits were paid-up share capital of up to ₹4 crore and turnover of up to ₹40 crore. The Companies (Specification of Definition Details) Amendment Rules, 2025 revised the limits to ₹10 crore and ₹100 crore respectively.

The Ministry of Corporate Affairs announced the change as part of efforts to reduce compliance burdens. The new limits may bring companies that previously exceeded one or both thresholds within the financial limits for small-company classification.

Consider a private limited company with paid-up share capital of ₹6 crore and turnover of ₹65 crore. Under the earlier limits, it exceeded both prescribed thresholds. Under the revised limits, it falls within both financial ceilings.

That does not, by itself, confirm that the company qualifies. It must still check whether it is a public company or falls within an excluded category, along with any other applicable conditions.

Practical takeaway: Reassess eligibility using the revised limits rather than relying on an old compliance checklist. Do not change the company’s filing approach until its complete eligibility has been verified.

Does every private limited company qualify?

No. Being a private limited company is not enough.

A private company may meet both financial thresholds but remain excluded from the definition. Section 2(85) specifically excludes:

  • A holding company.
  • A subsidiary company.
  • A company registered under Section 8.
  • A company or body corporate governed by a special Act.

Public companies are also outside the definition because Section 2(85) defines a small company as a company other than a public company.

These exclusions matter because the legal relationship between companies can be more important than the size of the business. For example, a private company that is a subsidiary cannot assume that it qualifies merely because its paid-up capital is ₹1 crore and its turnover is ₹5 crore.

Before selecting MGT-7A, review the company’s ownership structure, constitutional status and relevant financial statements. If the company has a parent entity, subsidiaries or a special statutory framework, obtain a specific eligibility assessment.

Private Limited Company Registration

How do you check whether your company qualifies?

Use the following practical checklist before choosing an annual-return form.

Step 1: Confirm the company type

Check the company’s incorporation records and MCA master data. Confirm whether it is a private company or public company and whether any other legal classification affects eligibility.

Step 2: Check paid-up share capital

Review the company’s latest relevant statutory records and share-capital details. Do not confuse authorised share capital with paid-up share capital. They are different measures.

For example, a company may have authorised share capital of ₹15 crore but paid-up share capital of ₹3 crore. The authorised amount alone does not establish whether it meets the small-company capital test.

Step 3: Check turnover

Review the profit and loss account for the immediately preceding financial year and identify the turnover figure relevant to the statutory test. Ensure that the financial statements relate to the correct year and are consistent with the company’s filing records.

Step 4: Check statutory exclusions

Confirm that the company is not a holding company, subsidiary company, Section 8 company or a company/body corporate governed by a special Act.

Step 5: Check the applicable financial year and current MCA instructions

Do not assume that a change in thresholds means every historical annual return should be filed using a newly selected form. Confirm the rules relevant to the financial year being filed, the company’s eligibility for that period and the latest MCA portal instructions.

Step 6: Document the conclusion

Keep a short eligibility note with the supporting financial figures, company status and the reason for selecting MGT-7 or MGT-7A. This creates a useful record for directors, accountants and compliance professionals.

MGT-7 vs MGT-7A: What is the difference?

MGT-7 and MGT-7A are annual-return forms under the Companies Act framework, but they are not interchangeable at the company’s discretion.

PointMGT-7MGT-7A
General purposeAnnual return for companies other than OPCs and small companiesAbridged annual return for OPCs and small companies
Typical relevanceCompanies that are not eligible for the abridged formEligible OPCs and small companies
SelectionBased on applicable statutory classification and filing rulesRequires confirmation that the company meets the applicable eligibility conditions
Key riskFiling it without checking the applicable requirementsAssuming the company qualifies solely because its capital and turnover are low

The exact form selection must be based on the applicable law, current form instructions and the company’s classification for the relevant filing. An old form-selection rule or a past portal error should not be treated as the definitive position after a regulatory amendment.

Can you use MGT-7A if your company meets the new limits?

Potentially, yes, if the company meets the full statutory definition and the form is applicable to the filing in question. Meeting the financial thresholds is only part of the assessment.

An eligible company should still verify the applicable year, exclusions and MCA filing instructions before submitting the form.

Does the revised definition change AOC-4 requirements?

Not automatically.

MGT-7A relates to the annual return. AOC-4 is associated with filing financial statements under Section 137 of the Companies Act, 2013. These are separate compliance requirements.

A company should not conclude that it no longer needs to file AOC-4 merely because it qualifies as a small company or uses MGT-7A. Financial-statement filing, annual-return filing, statutory audit obligations and other compliance requirements must be assessed separately.

A useful way to organise the annual compliance process is to maintain separate checklist items for:

  • Financial statements and the relevant AOC-4 form.
  • Annual return and the applicable MGT form.
  • Statutory audit and auditor-related requirements.
  • AGM and board-related records.
  • Other filings that apply to the company’s circumstances.

The small-company classification may affect certain obligations or relaxations under the law, but it is not a blanket exemption from company compliance.

What compliance benefits may apply to small companies?

The Companies Act framework provides certain relaxations for small companies. Depending on the provision and the company’s circumstances, these can include differences in board-meeting requirements, financial-statement presentation, penalties and other compliance obligations.

However, avoid treating “small company” as a universal exemption. Each benefit has its own legal provision, conditions and limitations. Some requirements may continue to apply regardless of the company’s size.

Before relying on a relaxation, identify the relevant section or rule and confirm that the company qualifies for it. For example, eligibility to use MGT-7A does not mean the company can skip the statutory audit or avoid all annual filings.

A practical compliance calendar should list each requirement separately and record whether the relevant small-company provision applies.

Does the definition use turnover, profit or revenue?

The statutory definition refers to turnover as per the profit and loss account for the immediately preceding financial year. Turnover is not the same as profit.

A company could report high turnover and low profit because its operating expenses are substantial. Another company might report a high profit margin on lower turnover. For the small-company test, do not substitute profit for the turnover figure.

Similarly, do not automatically substitute cash received, total assets, authorised share capital or the founder’s investment for the measures specified in the law.

Use the relevant financial statements and accounting records. If the figures are unclear or the company has unusual transactions, obtain advice from its accountant or company secretary before making a classification decision.

What happens if your company’s capital or turnover exceeds a limit?

If either financial criterion exceeds the prescribed limit, the company may fail the financial test for small-company status. But the analysis should be carried out using the relevant statutory definitions, financial-year context and applicable rules.

For example, a company with paid-up share capital of ₹8 crore and turnover of ₹105 crore is within the capital ceiling but exceeds the turnover ceiling. It should not assume that it qualifies based only on its paid-up capital.

Likewise, a company with turnover of ₹60 crore but paid-up capital of ₹12 crore exceeds the capital ceiling.

When a company is near a threshold, document the exact figures and confirm the appropriate treatment for the year concerned. Do not alter or restructure capital simply to reach a threshold without assessing the legal, accounting and commercial consequences.

What should existing companies do after the change?

Existing companies should review their classification rather than automatically changing their filing process.

A sensible review involves:

  1. Checking the effective date of the amendment.
  2. Identifying the financial year for which the annual return is being prepared.
  3. Reviewing the relevant paid-up capital and turnover figures.
  4. Checking whether any statutory exclusion applies.
  5. Confirming the applicable MGT form and current MCA instructions.
  6. Checking whether other annual compliance obligations remain applicable.
  7. Keeping a written record of the conclusion.

Companies should be particularly careful when filing returns for different financial years. A company’s present-day status should not be used as a shortcut for every historical filing.

The MCA portal may also change form workflows or validation rules. If the portal appears to conflict with the company’s legal assessment, save the error details and seek clarification through the relevant professional or official support channel instead of repeatedly submitting inconsistent forms.

A practical example: Does a growing startup qualify?

Imagine a private limited technology company with paid-up share capital of ₹7 crore and turnover of ₹80 crore. It is not a holding company, subsidiary, Section 8 company or company governed by a special Act.

On those facts, the company falls within the revised financial ceilings. It may qualify as a small company, subject to confirmation of all applicable statutory conditions and the relevant financial-year requirements.

Now consider a second company with paid-up share capital of ₹2 crore and turnover of ₹10 crore, but it is a subsidiary of another company. Even though its financial figures are well below both limits, the statutory exclusion means it cannot rely on the small-company definition in the same way.

These examples show why a proper assessment needs both financial information and legal-structure information.

Common mistakes to avoid

Mistake 1: Checking only turnover. The paid-up capital criterion must also be checked.

Mistake 2: Checking only paid-up capital. Turnover is a separate test.

Mistake 3: Confusing authorised capital with paid-up capital. These are different figures.

Mistake 4: Ignoring exclusions. Holding companies, subsidiaries and other excluded categories cannot rely on the financial thresholds alone.

Mistake 5: Confusing small-company status with MSME registration. These classifications serve different purposes.

Mistake 6: Treating MGT-7A as an exemption from AOC-4. Annual returns and financial statements are separate compliance matters.

Mistake 7: Relying on an old article or checklist. Confirm that the information reflects the amendment effective 1 December 2025.

Mistake 8: Assuming every portal error proves the legal position. Portal validations are important, but a disputed filing issue may require checking the applicable law and official instructions.

Mistake 9: Assuming the new limits automatically apply to every historical filing. Verify the relevant year and rules before choosing a form.

Mistake 10: Assuming a small company has no other compliance obligations. The company must still assess all applicable statutory requirements.

What about MGT-8 certification and MCA V3?

The Institute of Company Secretaries of India published an advisory dated 24 December 2025 concerning MGT-7/MGT-7A certification under the MCA V3 portal. The advisory discussed how MGT-8 certification was being handled in the MGT-7 workflow and recommended an approach for attaching certification-related material, including in relevant MGT-7A cases, pending further clarification or rule changes.

This is a technical area where the latest official position matters. Do not treat an older advisory as a permanent instruction without checking whether MCA has since issued a clarification or changed the forms or filing workflow.

If your filing requires certification or you are uncertain about the applicable requirement, review the latest MCA form instructions and consult a practising company secretary. Keep the relevant version of the form instructions with the filing record.

Frequently asked questions

What is the new small-company limit in India?

From 1 December 2025, the prescribed financial limits are paid-up share capital not exceeding ₹10 crore and turnover not exceeding ₹100 crore. Other statutory conditions and exclusions also apply.

Can a private limited company file MGT-7A?

An eligible private limited company may use MGT-7A if it meets the applicable small-company definition and the form is appropriate for the relevant filing. Being a private limited company alone is not sufficient.

Is MGT-7A compulsory for every small company?

The applicable annual-return form should be selected based on the company’s legal classification and the relevant rules. Confirm eligibility and current form instructions before filing.

Does a small company need to file AOC-4?

Small-company status does not automatically remove the financial-statement filing requirement. AOC-4 obligations must be assessed separately under the applicable law.

Does a company with turnover below ₹100 crore qualify automatically?

No. It must also meet the paid-up capital criterion, be within the applicable legal definition and not fall into an excluded category.

Is an MSME the same as a small company?

No. MSME classification and small-company status under the Companies Act are separate legal classifications with different criteria and purposes.

Can a subsidiary qualify as a small company?

Section 2(85) excludes a subsidiary company from the small-company definition. Financial figures below the thresholds do not override that exclusion.

Does small-company status remove the statutory audit requirement?

Do not assume so. Audit requirements must be checked separately under the applicable provisions of company law.

What if the MCA portal shows the wrong form?

Record the error and check the company’s legal classification, relevant financial year and current MCA instructions. Seek professional or official clarification if the problem remains unresolved.

Where can I verify the revised limits?

Start with the Ministry of Corporate Affairs announcement and the applicable amendment to the Companies (Specification of Definition Details) Rules, 2014. The company’s specific eligibility should then be assessed against the Companies Act and current filing instructions.

Final checklist before filing

Before selecting MGT-7 or MGT-7A, confirm:

  • The relevant financial year has been identified.
  • The company’s legal type has been checked.
  • Paid-up share capital has been verified.
  • Turnover has been checked against the relevant financial statements.
  • Holding/subsidiary and other statutory exclusions have been reviewed.
  • The applicable MGT form has been confirmed.
  • AOC-4 and other annual obligations have been assessed separately.
  • Current MCA portal instructions have been reviewed.
  • Any required professional certification has been checked.
  • Supporting records and the form-selection decision have been retained.

Conclusion

The revised small-company thresholds introduced from 1 December 2025 may help more Indian companies qualify for the small-company framework. For eligible companies, this can affect the annual-return form selection and may bring certain compliance relaxations into consideration.

But the decision should never be based on turnover or paid-up capital alone. Check both financial criteria, review the statutory exclusions, identify the relevant financial year and verify the latest MCA instructions before filing.

If you are unsure whether your company qualifies for MGT-7A, FilingPoint can help you review your annual filing requirements and identify the appropriate next steps.

Need help with ROC annual filing? Contact +91 72999 72500 / enquiry@filingpoint.com.

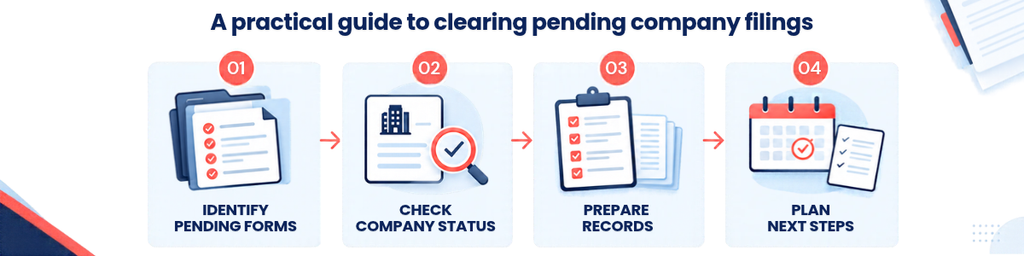
If your company has missed an ROC annual filing deadline, the most useful first step is to identify exactly which filings are pending, for which financial years, and what the company’s current compliance status is. You can then work with a qualified professional to prepare the outstanding documents, calculate the applicable fees and complete the appropriate filings or other required actions.

A missed deadline does not automatically mean that your company has ceased to exist. However, leaving overdue filings unresolved can lead to accumulating additional fees, statutory consequences and complications when applying for finance, bringing in investors, changing company ownership or closing the business.

The correct solution depends on the company’s circumstances. A company that has missed one annual filing may need a different recovery plan from a company with several years of defaults, an ROC notice or a proposed strike-off.

This guide explains how to approach overdue ROC filings in India, what to check before submitting forms, and when professional support may be appropriate.

What Does a Missed ROC Annual Filing Mean?

ROC annual filing refers to statutory filings that a company must make with the Registrar of Companies under the Companies Act, 2013 and applicable rules.

Two key annual filings are:

  • Form AOC-4: Used for filing the company’s financial statements and applicable attachments.
  • Form MGT-7 or MGT-7A: Used for filing the company’s annual return in the applicable format.

The forms serve different purposes. AOC-4 relates to financial reporting, while MGT-7 or MGT-7A reports prescribed company and ownership information. Completing one does not automatically complete the other.

Other event-based and periodic filings may also be outstanding. Depending on the company’s history, these could include filings relating to auditor appointments, changes in directors, share allotments, charges or other corporate events. Do not assume that clearing AOC-4 and MGT-7 alone resolves every compliance issue.

The legal requirements arise from the Companies Act, 2013, including Sections 92 and 137, alongside the relevant rules and prescribed forms. Check the current official requirements for the company’s type and circumstances before proceeding.

Why Do Companies Miss ROC Annual Filings?

A missed filing does not always happen because a founder deliberately ignored compliance. Common situations include:

  1. The founder assumed the accountant had filed everything. Accounting, audit and MCA filing are related but distinct tasks. Confirm that the forms were actually submitted and approved or processed as applicable.
  2. The business was inactive. A company may assume that no revenue means no annual filing obligation. Inactivity alone does not automatically remove statutory responsibilities.
  3. Financial statements were not finalised. Delayed bookkeeping, missing invoices, unresolved bank reconciliations or an unfinished audit can delay the filing process.
  4. The company changed its CA, CS or compliance provider. Records, credentials, working papers or responsibility for outstanding years may not have been handed over properly.
  5. The directors did not know about earlier defaults. A new director or shareholder may discover pending filings only when a bank, investor or adviser reviews the company.
  6. The filing was prepared but not completed. A draft, uploaded form or payment attempt is not the same as a successfully completed filing. Verify the status and retain the acknowledgement.

The lesson is simple: do not rely only on email assurances or a list of forms that someone says were prepared. Check the company’s actual filing records.

Step 1: Identify Every Pending Filing

Start by establishing the company’s current status and building a year-by-year compliance list.

Review the company’s MCA records and available filing history. Identify the financial years for which the relevant annual forms were due, whether each form was filed, and whether any submission was rejected, resubmitted or otherwise requires attention.

Create a working table such as this:

Financial yearAOC-4 statusMGT-7/MGT-7A statusOther issueNext action
FY 2022–23PendingPendingAccounts to verifyConfirm records and prepare documents
FY 2023–24Filed—verify statusPendingAnnual return incompleteReview filed record and prepare return
FY 2024–25PendingFiled—verify statusAudit status to confirmCoordinate with auditor and professional

This is an illustrative template, not a claim about any specific company. Replace the entries with verified information.

Also check whether the company has received notices, whether its status on the MCA register has changed, and whether any director-related or event-based compliance issue needs separate attention.

Important: Do not treat a company master-data page as a complete substitute for checking the individual filing history and documents. The company’s current status and each form’s status are different questions.

Before submitting overdue forms, confirm that the company remains in a position to make the intended filings and determine whether any formal action has already been initiated.

Check for:

  • The company’s current status in MCA records.
  • Any notice or communication from the ROC.
  • Pending or rejected forms.
  • Existing defaults relating to directors or other statutory filings.
  • Any strike-off notice, order or other legal proceeding.
  • Whether the company is active, dormant, under a status change or otherwise subject to a specific restriction.

If a notice has been received, read it carefully and note the issuing authority, reference number, subject, date and response deadline. A routine overdue filing and a formal regulatory notice should not be treated as the same situation.

If the company’s name has already been struck off, do not assume that ordinary annual filing alone will restore it. The available remedy depends on the legal status, applicable provisions, dates and facts. Obtain advice from a practising company secretary or lawyer familiar with company-law restoration proceedings.

Step 3: Collect the Records Needed for Each Year

A common mistake is to begin filling in forms before the underlying records are ready. For overdue filings, collect documents year by year.

Depending on the company and filing involved, the records may include:

  • Trial balance, ledger and bank statements.
  • Balance sheet and statement of profit and loss.
  • Notes to the financial statements and other applicable statements.
  • Auditor’s report and other required reports.
  • Board and shareholder meeting records.
  • Annual general meeting details, where applicable.
  • Register of members, shareholding details and relevant changes.
  • Director and registered-office details.
  • Details of share allotments, transfers or other corporate events.
  • Required declarations, certifications and supporting attachments.

The exact list depends on the company’s type, size, activities, applicable accounting requirements and the form being filed.

For example, if the annual return is pending but the financial statements were already filed, you may not need to repeat the financial-statement preparation exercise. You still need to verify that the previous filing was completed correctly and gather the information needed for the annual return.

Never recreate missing company records from memory when the statutory records, auditor’s working papers, bank statements or previous filings can be obtained. If records are missing or inconsistent, resolve that issue before submitting potentially inaccurate information.

Step 4: Calculate the Applicable Additional Fees and Assess Other Exposure

Late filing can involve more than one financial or legal consequence. Keep the categories separate.

Additional filing fees are amounts payable for delayed submission under the applicable fee framework. The fee may depend on the form, the period of delay and the current rules.

Statutory penalties are separate legal consequences that may arise under the Companies Act or applicable provisions. They are not necessarily settled simply by paying the additional filing fee.

Professional charges are fees charged by a CA, practising CS, lawyer or compliance provider for work such as reviewing records, preparing forms, resolving discrepancies and managing the filing process.

Other costs or consequences may arise if the company has received a notice, needs to correct earlier records, has multiple defaults or is facing strike-off or other proceedings.

Do not rely on a generic online estimate as a final calculation. Check the current MCA filing requirements and fee displayed for each relevant form, and ask a qualified professional to assess any separate statutory exposure. Fee rules and legal provisions can change, and the outcome depends on the facts.

Also verify whether any officially notified fee-relief scheme is currently in force and whether the company and its forms qualify. Do not assume a past scheme is still open, and do not rely on promotional messages that promise a waiver without an official notification.

Step 5: Prepare and Submit the Outstanding Forms

Once the records and compliance position are understood, prepare the forms for the relevant financial years.

A typical recovery workflow is:

  1. Confirm the financial year and applicable form.
  2. Reconcile the form data with the company’s books and statutory records.
  3. Obtain the required audit, approval, signature and certification, where applicable.
  4. Check attachments, director details, dates and other mandatory fields.
  5. Validate the form and resolve any errors.
  6. Complete the prescribed digital-signature and submission steps.
  7. Pay the applicable filing fee and additional fee shown through the official process.
  8. Retain the submission acknowledgement, payment evidence and final filing records.
  9. Verify the resulting filing status and address any resubmission or rejection message.

Do not assume every overdue year can be filed in any order without review. The filing sequence and documents required can depend on the nature of the defaults, the company’s history and the applicable form rules.

If the MCA system rejects a form or requests resubmission, read the reason carefully and correct the underlying issue. Repeatedly uploading the same inaccurate information may waste time and create further problems.

If the company has received a formal notice, do not ignore it while preparing the overdue forms.

Read the notice and identify whether it requires a response, documentary evidence, a hearing, payment, correction or another action. Note the deadline and keep a copy of the response and supporting evidence.

If the company is facing proposed strike-off action or its name has already been removed from the register, the issue may require a specific legal route. The Companies Act and the applicable rules govern the available process. In certain strike-off situations, overdue financial statements and annual returns may need to be filed before a voluntary strike-off application can be made; the applicable requirements should be checked against the company’s exact situation.

A professional should review the notice, the current company status and the relevant filing history before advising on the next step.

What If ROC Filings Have Been Pending for Several Years?

A multi-year default requires a broader review than a single late form.

Prepare a complete list of pending filings and confirm the status of each year. Reconstruct or obtain the financial records, coordinate with the auditor, identify changes in directors or shareholding, and check whether other event-based filings are outstanding.

Then assess:

  • Which financial statements and annual returns remain pending.
  • Whether any previously filed form needs correction.
  • Whether directors or officers may face separate consequences.
  • Whether a formal notice or strike-off action has been initiated.
  • Whether the company intends to continue operating, raise funds, transfer ownership or close.
  • Whether legal or professional advice is required before filing.

Do not assume that a company with several years of defaults is automatically struck off. Equally, do not assume it is safe simply because it still appears in a search result. Verify the actual status and any proceedings.

Can a Company Continue Operating With Pending ROC Filings?

The answer depends on the company’s status, the type of default and any applicable legal restrictions or regulatory action. Pending annual filings do not, by themselves, establish that every business activity is prohibited. However, unresolved non-compliance can create significant legal and practical difficulties.

Banks, investors, purchasers, lenders and other counterparties may ask for statutory records and evidence of compliance during due diligence. Outstanding filings can delay that review or lead to requests for clarification and remediation.

Directors should not treat continued business activity as evidence that the compliance position is acceptable. Establish the company’s status and obtain advice on any specific restrictions or consequences that apply.

How Pending ROC Filings Affect Loans, Investment and Business Transactions

A lender or investor may review the company’s MCA filings, financial statements, ownership information, director details and other statutory records.

If required annual forms are missing, the reviewer may need additional explanations or evidence. The transaction could be delayed while the company clears the backlog or reconciles inconsistencies. A purchaser may also ask for representations, warranties or other protections relating to historical compliance.

This does not mean that every company with an overdue filing will automatically be denied funding or a loan. The outcome depends on the lender or investor, the transaction, the company’s financial position and the nature of the outstanding issues.

If you expect a funding round, business sale or loan application, review the company’s compliance history early rather than waiting until due diligence begins.

Company Registration in Chennai

Common Mistakes to Avoid When Clearing Pending ROC Filings

1. Filing only the most recent year. Older outstanding filings may remain unresolved. Prepare a full year-by-year list.

2. Assuming the accountant has filed everything. Ask for form-wise acknowledgements and independently verify the available records.

3. Ignoring the difference between fees and penalties. Payment of an additional filing fee does not necessarily resolve separate statutory consequences.

4. Submitting forms before reconciling the records. Inconsistent financial statements, shareholder information or dates can cause rejection or create further compliance problems.

5. Ignoring a formal notice. A filing plan may not replace a required response or other action by a deadline.

6. Trusting a supposed waiver without verification. Check the official MCA notification, scheme dates, eligible forms and conditions.

7. Assuming an inactive company has no obligations. Lack of revenue or operations does not automatically remove company-law responsibilities.

8. Failing to retain proof. Keep copies of forms, acknowledgements, payment evidence and communications with professionals.

Frequently Asked Questions

1. Can I file ROC annual returns after the due date?

Late filing may be possible, but the applicable form requirements, additional fees and any separate legal consequences must be checked. If a notice or other proceeding is pending, further action may be required.

2. What should I do first if AOC-4 and MGT-7 are overdue?

Check the company’s filing history, identify every outstanding financial year, confirm the company’s status, collect the required records and calculate the applicable fees before preparing the forms.

3. Does a company need to file ROC returns if it has no business activity?

Inactivity or zero revenue does not automatically remove statutory filing obligations. Confirm the company’s type, status and applicable requirements before deciding what needs to be filed.

4. Will paying the late filing fee clear every default?

Not necessarily. Additional filing fees and statutory penalties are different. Notices, incorrect records, director-related defaults or other proceedings may need separate attention.

5. Can the ROC strike off a company for non-filing?

Strike-off action may be possible under the applicable legal provisions and circumstances. Check the company’s status and any notice received. Do not assume that non-filing has automatically resulted in strike-off.

6. What if the company has not filed for three or more years?

Prepare a year-by-year list of outstanding forms, reconstruct or obtain records, check the company’s legal status and obtain professional advice on the complete backlog. The remedy depends on the facts and any action already taken.

7. Can pending ROC filings affect a loan or investment?

They can create additional due-diligence work or delays because lenders and investors may request statutory records and explanations. The effect depends on the transaction and the company’s overall circumstances.

8. How do I know whether my compliance provider actually filed the forms?

Request the form-wise filing acknowledgements and payment evidence, then verify the available filing records through the official MCA system. Do not rely solely on a message saying that a form was prepared.

When Should You Get Professional Help?

Consider engaging a practising CA, company secretary or lawyer when:

  • Several financial years are pending.
  • Financial statements or statutory records are incomplete.
  • The company has received a notice from the ROC.
  • Forms have repeatedly been rejected or resubmission is unclear.
  • The company may be facing strike-off action or needs restoration advice.
  • Director-related defaults or other statutory issues exist.
  • The company is preparing for a loan, investment, sale or restructuring.
  • You are unsure whether filing alone will resolve the default.

A professional should first review the company’s actual status and list of defaults, then explain the proposed steps, estimated government fees, professional charges and any separate legal risks. Ask for a written scope of work and proof of filing once the work is completed.

How FilingPoint Can Help

If your company has missed one or more ROC annual filings, FilingPoint can help you understand the compliance work required and organise the next steps.

Before starting, gather your company’s CIN, the relevant financial years, available filing acknowledgements and any notices received. This information helps establish what is pending and whether additional review is needed.

Need help reviewing pending ROC filings? Contact our team to enquire about company compliance support. The appropriate solution will depend on your company’s records, filing history and current legal status.

Final Checklist: Before You Regularise Pending ROC Filings

  • List all pending forms and financial years.
  • Confirm the company’s current status and check for notices.
  • Collect financial statements, audit records and statutory information.
  • Reconcile the documents before preparing the forms.
  • Verify the applicable fees and assess separate legal exposure.
  • Submit the required forms and retain acknowledgements.
  • Address any rejection, resubmission or notice separately.
  • Create a compliance calendar to prevent future delays.

The most important step is to establish the facts before acting. Once you know what is pending, the company’s current status and the applicable requirements, you can plan a more accurate route to resolving overdue ROC filings.

Note: This article is general information, not legal or company-secretarial advice for a specific company. Verify current MCA forms, fee rules, notifications and statutory provisions before publication and before acting on an individual case.

Explore by Category

Auditor Resignation

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online Call FilingPoint.Com Experts Now. Seeking professional assistance for Filing of auditor resignation in India? Trust FilingPoint.Com, India’s Largest Registration and Filing Services Provider, to handle the process seamlessly and ensure timely completion. Call us at +91 72999 72500 or visit https://filingpoint.com to avail of our services and experience a hassle-free auditor resignation process. Introduction to Auditor Resignation Auditor resignation is a significant event in the lifecycle of a private limited company, one person company (OPC), or limited liability partnership (LLP) in India. It occurs when the appointed auditor decides to step down from their position due to various reasons such as conflicts of interest, non-compliance issues, or personal circumstances. Managing the Auditor Resignation Filing Services process effectively is crucial to maintain compliance with regulatory requirements and ensure transparency and accountability in financial reporting. Advantages of Auditor Resignation Filing Services in India for Private Limited Companies, OPCs, and LLPs 1. Compliance Assurance: We ensure compliance with all relevant provisions of the Companies Act, 2013, and other applicable laws and regulations governing auditor resignations in India, minimizing the risk of non-compliance. 2. Timely Completion: Our expert team prioritizes timely completion of the auditor resignation process, ensuring minimal disruption to the company’s operations and financial reporting. 3. Efficient Communication: We handle all communication and correspondence with regulatory authorities, including the Ministry of Corporate Affairs (MCA) and Registrar of Companies (ROC), to notify them of the auditor’s resignation promptly. 4. Smooth Transition: We facilitate a smooth transition between the outgoing auditor and the newly appointed auditor, ensuring continuity in the audit process and adherence to statutory timelines. 5. Documentation Support: We assist businesses in preparing and filing the necessary documentation and forms required for notifying the authorities of the auditor’s resignation, ensuring accuracy and completeness. 6. Independent Assessment: Our team conducts an independent assessment of the reasons for the auditor’s resignation, providing valuable insights and recommendations to address any underlying issues or concerns. 7. Stakeholder Confidence: Effective management of the auditor resignation process enhances stakeholder confidence in the company’s governance practices and financial reporting, maintaining trust and credibility. 8. Risk Mitigation: By managing the auditor resignation process professionally, we help mitigate the risk of reputational damage or regulatory sanctions associated with improper handling of auditor resignations. 9. Expert Guidance: Our experienced professionals provide expert guidance and support throughout the auditor resignation process, addressing any queries or concerns and ensuring compliance with regulatory requirements and best practices. Contact Us for Efficient Auditor Resignation Services in India FilingPoint.Com is your trusted partner for seamless and efficient auditor resignation services tailored to the needs of private limited companies, OPCs, and LLPs in India. With our expertise and commitment to excellence, we ensure compliance with regulatory requirements and facilitate a smooth transition during auditor resignations. Call us at +91 72999 72500 or visit https://filingpoint.com to avail of our services and manage auditor resignations with confidence today.
Call Us Now +91 72999 72500

Business Registration

Company Name Reservation

Company Registration

FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your company registration process. Let us handle your registration needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Company Registration Services: Company Registration in India is a pivotal step for entrepreneurs and business owners looking to establish a legal entity for their ventures. Whether it’s a private limited company, One Person Company (OPC), or Limited Liability Partnership (LLP), registering a company offers numerous advantages, providing a solid foundation for growth, compliance, and credibility in the market. Advantages for Company Registration Services for Private Limited Companies, OPCs, LLPs: 1. Legal Recognition: Company Registration grants legal recognition to the business entity, establishing its separate legal identity distinct from its owners or shareholders, ensuring protection of personal assets and liabilities. 2. Limited Liability Protection: Private limited companies and LLPs offer limited liability protection to their owners, shielding personal assets from business debts and legal obligations, providing financial security and risk mitigation. 3. Access to Funding: Registered companies have better access to funding opportunities from banks, financial institutions, venture capitalists, and angel investors, enabling them to raise capital for business expansion and growth. 4. Credibility and Trust: A registered company instills confidence and trust among customers, suppliers, investors, and stakeholders, enhancing the credibility and reputation of the business in the market. 5. Brand Protection: Registering the company name and logo as trademarks safeguards intellectual property rights, preventing unauthorized use or infringement by competitors, protecting the brand identity and goodwill. 6. Perpetual Succession: Companies enjoy perpetual succession, meaning the existence of the business is not affected by changes in ownership, management, or death of shareholders, ensuring continuity and stability. 7. Tax Benefits: Registered companies are eligible for various tax benefits, incentives, and exemptions provided by the government, reducing the tax burden and optimizing tax planning strategies. 8. Growth Opportunities: Company Registration opens doors to business expansion opportunities such as entering new markets, launching new products or services, and forming strategic partnerships or joint ventures. 9. Compliance and Governance: Registered companies are required to comply with statutory regulations, including filing annual returns, maintaining proper accounting records, conducting board meetings, and adhering to corporate governance standards, ensuring transparency and accountability. Experience the seamless process of Company Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in establishing your business entity while you focus on realizing your entrepreneurial vision. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

GST Address Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your GST Address Change process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Address Change Services in GST: GST (Goods and Services Tax) Address Change in India is a critical requirement for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) looking to update their business address with the GST authorities. This process involves submitting the necessary documentation and making the required changes to ensure accurate tax compliance, offering numerous advantages to businesses and facilitating seamless operations. Advantages for Address Change Services in GST for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Updating the GST address ensures compliance with GST regulations, avoiding potential penalties or legal consequences associated with outdated or incorrect business information. 2. Accurate Tax Reporting: A correct GST address ensures accurate tax reporting and invoicing, reducing the risk of errors and discrepancies in GST filings and facilitating smooth interactions with customers and vendors. 3. Seamless Business Operations: A current GST address eliminates disruptions in business operations, ensuring that important communications, notices, and correspondences from the GST authorities reach the company promptly without delays or complications. 4. Improved Credibility: Maintaining up-to-date business information, including the GST address, enhances the company’s credibility and trustworthiness among customers, suppliers, and other stakeholders, fostering stronger business relationships. 5. Avoidance of Communication Errors: Updating the GST address prevents communication errors and misunderstandings, ensuring that the company receives important notifications, alerts, and updates from the GST authorities without any issues. 6. Efficient Logistics and Deliveries: A correct GST address facilitates efficient logistics and deliveries, ensuring that goods and services are shipped to the correct location without delays or misplacements, thereby enhancing customer satisfaction. 7. Enhanced Visibility: A current GST address enhances the company’s visibility in the GST ecosystem, making it easier for customers, suppliers, and regulatory authorities to locate and engage with the business, thereby boosting its market presence. 8. Seamless Expansion: Updating the GST address streamlines the process of expanding or relocating business operations to new locations, ensuring that the company’s tax registrations and compliance obligations are updated accordingly. 9. Proactive Compliance Management: Regularly updating the GST address demonstrates proactive compliance management and a commitment to maintaining accurate business records, reducing the risk of non-compliance and associated penalties. Experience the seamless process of GST Address Change with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with GST regulations while you focus on growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

GST Name Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your GST Name Change process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Name Change in GST: GST Name Change in India is a significant procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) looking to update their GST registration details due to a change in the business name. This process involves submitting the necessary documentation to the GST authorities, offering numerous advantages to businesses and ensuring seamless compliance with tax regulations. Advantages for Name Change in GST for Private Limited Companies, OPCs, LLPs: 1. Compliance with Legal Requirements: Changing the GST registration name ensures compliance with GST regulations, avoiding potential penalties or legal consequences associated with outdated or incorrect registration information. 2. Reflects Updated Business Identity: Updating the GST registration name reflects the updated business identity, ensuring that the company’s tax records accurately represent its current legal entity and branding. 3. Enhanced Brand Recognition: A changed GST registration name enhances brand recognition and visibility in the market, aligning the company’s tax registration with its brand identity and facilitating stronger market presence. 4. Streamlined Business Operations: A current GST registration name streamlines business operations, ensuring that invoices, documents, and communications accurately reflect the company’s legal name, thereby reducing confusion and errors. 5. Improved Customer Trust: A changed GST registration name instills trust and confidence in customers, suppliers, and other stakeholders, as it demonstrates the company’s commitment to transparency and professionalism. 6. Clear Communication Channels: Updating the GST registration name clarifies communication channels with the GST authorities and other government agencies, ensuring that notifications, alerts, and updates are received promptly and accurately. 7. Facilitates Contractual Agreements: A changed GST registration name facilitates the execution of contractual agreements and legal documents, ensuring that the company’s tax registration aligns with its contractual obligations and commitments. 8. Enables Seamless Transition: Changing the GST registration name enables a seamless transition for the company, allowing it to adapt its tax registration to reflect changes in its business structure or branding without disruptions. 9. Demonstrates Adaptability: Updating GST registration with a name change demonstrates the company’s adaptability and responsiveness to market dynamics, showcasing its ability to evolve and grow in line with changing business requirements. Experience the seamless process of GST Name Change with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with GST regulations while you focus on driving your business forward. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Address Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your IE Code Address Change process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for IE Code Address Change: IE Code Address Change in India is a crucial procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) engaged in import-export activities. This process involves updating the registered address of the Importer-Exporter (IE) Code with the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuity of their international trade operations. Advantages for IE Code Address Change for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Updating the IE Code address ensures compliance with DGFT regulations, avoiding penalties or legal consequences associated with outdated or incorrect address information. 2. Uninterrupted Trade Operations: IE Code Address Change ensures uninterrupted trade operations, allowing businesses to continue importing and exporting goods and services without disruptions or delays. 3. Legal Compliance with Banks: Banks and financial institutions require accurate IE Code address information for processing international transactions and providing trade finance facilities, making IE Code Address Change essential for maintaining banking relationships. 4. Facilitates Smooth Customs Clearance: Updating the IE Code address expedites customs clearance processes, reducing the time and effort required for importing and exporting goods, thereby enhancing operational efficiency and reducing costs. 5. Enhanced Credibility: A current and accurate IE Code address enhances the credibility and trustworthiness of the business in the eyes of international suppliers, buyers, and regulatory authorities, fostering stronger relationships and partnerships. 6. Ensures Proper Documentation: Updating the IE Code address ensures that all trade-related documents, including invoices, shipping documents, and contracts, reflect the correct address information, minimizing errors and discrepancies in documentation. 7. Compliance with Export Control Laws: IE Code Address Change ensures compliance with export control laws, regulations, and government policies, mitigating the risk of legal liabilities and penalties associated with non-compliance. 8. Facilitates Government Benefits: Businesses with updated IE Code address details may be eligible for various government incentives, benefits, and schemes aimed at promoting exports and boosting foreign trade. 9. Enables Growth Opportunities: A current IE Code address facilitates business growth and expansion into new international markets, enabling businesses to capitalize on emerging opportunities and diversify their revenue streams. Experience the seamless process of IE Code Address Change with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on expanding your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Director Addition

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your IE Code Director Addition process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Director Addition in IE Code: IE Code Director Addition in India is a significant procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) involved in import-export activities. This process involves adding directors to the Importer-Exporter (IE) Code with the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuity of their international trade operations. Advantages for Director Addition in IE Code for Private Limited Companies, OPCs, LLPs: 1. Enhanced Governance Structure: Adding directors to the IE Code ensures an enhanced governance structure, reflecting the accurate representation of the company’s management team in its import-export operations. 2. Compliance with Regulatory Requirements: IE Code Director Addition ensures compliance with DGFT regulations, as all directors involved in import-export activities must be listed in the IE Code to legally represent the company. 3. Expanded Decision-Making Authority: Including additional directors in the IE Code broadens the decision-making authority within the company, enabling a more collaborative approach to import-export strategies and operations. 4. Improved Operational Efficiency: With more directors listed in the IE Code, tasks related to import-export activities can be delegated more effectively, leading to improved operational efficiency and streamlined processes. 5. Redundancy Planning: Adding directors to the IE Code provides redundancy planning, ensuring continuity of import-export operations even in the absence or unavailability of key personnel. 6. Enhanced Credibility: A comprehensive list of directors in the IE Code enhances the credibility of the company in the eyes of international partners, suppliers, and regulatory authorities, fostering trust and confidence. 7. Facilitates Business Expansion: IE Code Director Addition facilitates business expansion initiatives by providing the necessary legal framework to support growth into new international markets and territories. 8. Strengthened Legal Representation: With multiple directors listed in the IE Code, the company benefits from strengthened legal representation in import-export transactions and dealings with international entities. 9. Enables Strategic Partnerships: Having a robust IE Code with all relevant directors listed enables the company to enter into strategic partnerships and collaborations with international counterparts, leveraging collective expertise and resources for mutual benefit. Experience the seamless process of IE Code Director Addition with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on expanding your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Director Removal

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, guarantees timely completion of your IE Code Director Removal process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Director Removal in IE Code: IE Code Director Removal in India is a crucial procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) involved in import-export activities. This process involves removing directors from the Importer-Exporter (IE) Code with the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuity of their international trade operations. Advantages for Director Removal in IE Code for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Removing directors from the IE Code ensures compliance with DGFT regulations, as only active directors involved in import-export activities should be listed in the IE Code. 2. Streamlined Governance Structure: IE Code Director Removal streamlines the governance structure of the company, ensuring that only relevant and authorized personnel are associated with import-export operations. 3. Legal Clarity: Removing inactive or unauthorized directors from the IE Code provides legal clarity and transparency, mitigating the risk of misunderstandings or disputes regarding the representation of the company in import-export transactions. 4. Operational Efficiency: With unnecessary directors removed from the IE Code, import-export operations can be managed more efficiently, leading to improved productivity and streamlined processes. 5. Reduces Administrative Burden: IE Code Director Removal reduces the administrative burden on the company by eliminating the need to involve inactive or unauthorized directors in import-export-related tasks and decision-making processes. 6. Enhanced Security: Removing unauthorized directors from the IE Code enhances the security and integrity of import-export operations, reducing the risk of unauthorized access or misuse of IE Code-related information. 7. Facilitates Succession Planning: IE Code Director Removal enables effective succession planning by ensuring that only designated and authorized individuals are listed in the IE Code to represent the company in import-export activities. 8. Maintains Compliance with Banking Requirements: Banks and financial institutions require accurate IE Code information for processing international transactions and providing trade finance facilities. IE Code Director Removal ensures compliance with banking requirements by updating the IE Code with only active and authorized directors. 9. Supports Strategic Decision-Making: With unnecessary directors removed from the IE Code, the company’s leadership can focus on strategic decision-making and planning for the future of import-export operations without distractions or complications. Experience the seamless process of IE Code Director Removal with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on optimizing your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely IE Code Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for IE Code Registration Services: IE Code Registration in India is a crucial requirement for businesses engaged in the import and export of goods and services. Issued by the Directorate General of Foreign Trade (DGFT), Importer Exporter Code (IE Code) is a unique 10-digit identification number that facilitates international trade transactions. Obtaining an IE Code offers several advantages to private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs), enabling them to engage in global trade activities seamlessly. Advantages for IE Code Registration Services for Private Limited Companies, OPCs, LLPs: 1. Facilitates International Trade: IE Code Registration facilitates international trade by providing businesses with a unique identification number recognized by customs authorities for importing and exporting goods and services. 2. Requirement for Customs Clearance: IE Code is mandatory for customs clearance of goods at Indian ports and airports, ensuring smooth and hassle-free clearance of imported and exported shipments. 3. Enables Access to Export Incentives: Registered exporters with IE Code are eligible to avail various export incentives and benefits offered by the government, such as duty drawback, export subsidies, and export finance schemes. 4. Establishes Credibility: Having an IE Code enhances the credibility and reliability of businesses in the eyes of overseas suppliers, buyers, banks, and financial institutions, facilitating trust and confidence in trade transactions. 5. Expands Market Reach: IE Code enables businesses to explore new markets and expand their customer base globally by engaging in cross-border trade activities without any restrictions. 6. Compliance with Legal Requirements: IE Code Registration ensures compliance with the Foreign Trade Policy (FTP) of India and other relevant regulations governing import and export activities, avoiding penalties or legal consequences for non-compliance. 7. Enables Direct Exporting: IE Code empowers businesses to engage in direct exporting, allowing them to negotiate better terms with overseas buyers, establish direct business relationships, and maximize profits. 8. Access to Government Schemes: Registered exporters with IE Code can participate in various government schemes and initiatives aimed at promoting exports, such as trade fairs, exhibitions, and international buyer-seller meets. 9. Simplifies Banking Transactions: IE Code facilitates smooth banking transactions for international trade, including receiving payments in foreign currency, opening and maintaining foreign currency accounts, and availing export finance facilities. Experience the seamless process of IE Code Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in obtaining your IE Code efficiently while you focus on expanding your global trade opportunities. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Renewal

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your IE Code Renewal process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for IE Code Renewal: IE Code Renewal in India is an essential requirement for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) engaged in import-export activities. This process involves renewing the Importer-Exporter (IE) Code issued by the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuation of their international trade operations. Advantages for IE Code Renewal for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Renewing the IE Code ensures compliance with the regulatory requirements of the DGFT, avoiding penalties or legal consequences associated with expired or invalid IE Codes. 2. Uninterrupted Trade Operations: IE Code Renewal ensures uninterrupted trade operations, allowing businesses to continue importing and exporting goods and services without disruptions or delays. 3. Access to International Markets: A valid IE Code enables businesses to access international markets, facilitating cross-border trade and expanding business opportunities beyond domestic boundaries. 4. Credibility and Trust: Renewing the IE Code enhances the credibility and trustworthiness of the business in the eyes of international suppliers, buyers, and regulatory authorities, fostering stronger relationships and partnerships. 5. Compliance with Banking Requirements: Banks and financial institutions often require a valid IE Code for processing international transactions and providing trade finance facilities, making IE Code Renewal essential for maintaining banking relationships. 6. Seamless Customs Clearance: A valid IE Code expedites customs clearance processes, reducing the time and effort required for importing and exporting goods, thereby enhancing operational efficiency and reducing costs. 7. Legal Protection: Renewing the IE Code provides legal protection to businesses engaged in international trade, ensuring compliance with export control laws, regulations, and government policies. 8. Facilitates Government Benefits: Businesses with a valid IE Code may be eligible for various government incentives, benefits, and schemes aimed at promoting exports and boosting foreign trade. 9. Enables Growth and Expansion: A renewed IE Code facilitates business growth and expansion into new international markets, enabling businesses to capitalize on emerging opportunities and diversify their revenue streams. Experience the seamless process of IE Code Renewal with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on expanding your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

LLP Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely LLP Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for LLP Registration Services: LLP Registration in India is a popular choice for entrepreneurs and businesses looking for a flexible and less burdensome form of business structure. A Limited Liability Partnership (LLP) combines the benefits of a partnership with limited liability protection, making it an attractive option for various industries. Registering an LLP offers several advantages to private limited companies, One Person Companies (OPCs), and other entities, providing a legal framework for collaboration and growth. Advantages for LLP Registration Services for Private Limited Companies, OPCs, LLPs: 1. Limited Liability Protection: LLP Registration provides limited liability protection to its partners, ensuring that their personal assets are safeguarded from business liabilities and debts, offering financial security. 2. Separate Legal Entity: An LLP is considered a separate legal entity distinct from its partners, allowing it to enter into contracts, own assets, sue or be sued in its own name, enhancing credibility and legal recognition. 3. Flexibility in Management: LLPs offer flexibility in management and operations, allowing partners to define their roles, responsibilities, profit-sharing arrangements, and decision-making processes as per the LLP Agreement. 4. Minimal Compliance Requirements: LLPs have fewer compliance requirements compared to private limited companies, such as no requirement for mandatory audits for smaller LLPs, reducing administrative burden and costs. 5. Tax Benefits: LLPs are taxed as partnerships, with profits taxed at the partner level, offering tax benefits such as pass-through taxation, avoiding double taxation on profits distributed to partners. 6. Easy Transferability of Ownership: LLPs allow for easy transferability of ownership interests, enabling partners to transfer their ownership stake to other individuals or entities as per the terms of the LLP Agreement. 7. No Minimum Capital Requirement: LLPs do not have any minimum capital requirement, allowing partners to contribute capital as per their agreement, making it accessible to startups and small businesses. 8. Continuity of Existence: LLPs enjoy perpetual succession, meaning the LLP continues to exist irrespective of changes in partners or management, providing continuity and stability to the business. 9. Enhanced Credibility: Registering as an LLP enhances the credibility and trustworthiness of the business in the eyes of customers, suppliers, lenders, and stakeholders, facilitating smoother business transactions. Experience the seamless process of LLP Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in establishing your LLP efficiently while you focus on building and growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

MSME Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely MSME Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for MSME Registration Services: MSME Registration in India holds significant importance for businesses aiming to avail of various benefits and incentives provided by the government for Micro, Small, and Medium Enterprises (MSMEs). This registration acknowledges the contribution of small businesses to the country’s economy and provides them with exclusive benefits and support. Whether you operate as a private limited company, One Person Company (OPC), or Limited Liability Partnership (LLP), obtaining MSME Registration offers numerous advantages, fostering growth and development. Advantages for MSME Registration Services for Private Limited Companies, OPCs, LLPs: 1. Access to Subsidized Loans: MSME-registered entities are eligible for collateral-free loans and subsidies under various government schemes, facilitating access to finance for business expansion and development. 2. Priority Lending by Banks: Banks often prioritize lending to MSMEs, offering lower interest rates and favorable terms on loans, fostering financial stability and growth for registered businesses. 3. Credit Guarantee Fund Scheme: MSME Registration enables businesses to avail of the Credit Guarantee Fund Scheme, providing collateral-free credit facilities and reducing the risk for lenders. 4. Preference in Government Tenders: MSME-registered companies receive preference in government procurement contracts and tenders, promoting their participation in public sector projects and initiatives. 5. Concessions on Electricity Bills: Registered MSMEs enjoy concessions and rebates on electricity bills, reducing operational costs and improving competitiveness in the market. 6. Subsidies for Technology Upgradation: MSMEs can benefit from subsidies and incentives for adopting modern technology, enhancing productivity, efficiency, and competitiveness in the industry. 7. Protection Against Delayed Payments: MSME Registration enables businesses to seek redressal for delayed payments from buyers or clients under the Micro, Small, and Medium Enterprises Development (MSMED) Act, ensuring timely receivables. 8. Skill Development and Training Programs: MSME-registered entities have access to skill development and training programs organized by the government to enhance the capabilities and competencies of the workforce. 9. Marketing Assistance and Support: The government provides marketing assistance and support to MSMEs through various schemes, helping them promote their products and services domestically and internationally. Experience the seamless process of MSME Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in obtaining your MSME Registration efficiently while you focus on growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

Name Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely and accurate completion of your company’s name change process. Trust us to handle your documentation needs efficiently. Call us today at +91 72999 72500 or visit https://filingpoint.com. Introduction for ROC Company Name Change Filing Services: Name change in India is a significant decision for private limited companies, one person companies (OPCs), and limited liability partnerships (LLPs). It involves altering the company’s name to better reflect its evolving business objectives, market positioning, or ownership structure. This process requires compliance with legal formalities and regulatory approvals. Let’s explore the advantages of opting for a name change for businesses in India. Advantages of Name Change in India for Private Limited Companies, OPCs, and LLPs: 1. Brand Reinvention: Changing the company’s name allows for a fresh start and enables brand reinvention, helping to attract new customers, investors, and business partners. 2. Market Differentiation: A new name can differentiate the company from competitors, helping it stand out in the market and gain a competitive edge. 3. Reflecting Company Evolution: As companies evolve and expand their offerings or change their strategic direction, a name change can better reflect these changes and align with the company’s current identity. 4. Correcting Misconceptions: In cases where the existing name causes confusion or misconceptions about the company’s products, services, or values, a name change can help clarify the company’s identity and positioning. 5. Ownership Transition: In the event of ownership changes or mergers, a name change can signal the transition to new management or ownership, providing clarity to stakeholders and customers. 6. Legal Compliance: A name change ensures compliance with legal requirements and regulations governing company names, avoiding any legal challenges or complications in the future. 7. Enhancing Brand Image: A well-chosen new name can enhance the company’s brand image and reputation, positioning it as innovative, forward-thinking, and responsive to market trends. 8. Rebranding Opportunities: A name change provides an opportunity for comprehensive rebranding, including updates to the company’s logo, website, marketing materials, and messaging, to create a cohesive brand identity. 9. Attracting Investment: A new name can generate renewed interest from investors and stakeholders, signaling the company’s commitment to growth and adaptation to market dynamics. In conclusion, opting for a name change in India offers numerous advantages for private limited companies, OPCs, and LLPs, including brand reinvention, market differentiation, and legal compliance. Trust FilingPoint.Com to deliver expert name change services tailored to your company’s specific needs. Contact us today at +91 72999 72500 or visit https://filingpoint.com for reliable and efficient assistance.
Call Us Now +91 72999 72500

Name Ideas

OPC Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely OPC Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for OPC Registration Services: OPC Registration in India offers a unique opportunity for entrepreneurs and small businesses to establish a separate legal entity with limited liability while retaining the benefits of sole proprietorship. One Person Company (OPC) is an ideal choice for single entrepreneurs looking to start their venture with limited liability protection. Whether you operate as a private limited company, OPC, or Limited Liability Partnership (LLP), registering as an OPC comes with several advantages, providing a conducive environment for business growth and success. Advantages for OPC Registration Services for Private Limited Companies, OPCs, LLPs: 1. Limited Liability Protection: OPC Registration provides limited liability protection to its sole owner, safeguarding personal assets from business debts and liabilities, ensuring financial security. 2. Separate Legal Entity: An OPC is considered a separate legal entity distinct from its owner, enabling it to enter into contracts, own assets, sue or be sued in its own name, enhancing credibility and legal recognition. 3. Minimal Compliance Requirements: OPCs have fewer compliance requirements compared to private limited companies, such as no requirement for mandatory annual general meetings (AGMs) or rotation of auditors, reducing administrative burden and costs. 4. Single Ownership: OPC allows a single individual to own and manage the entire business, providing full control and autonomy over decision-making and operations, eliminating the need for external shareholders. 5. Easy Transferability of Ownership: OPC allows for easy transferability of ownership through transfer of shares, enabling the owner to sell or transfer the business to another individual or entity as per the provisions of the Companies Act, 2013. 6. Continuity of Existence: OPC enjoys perpetual succession, meaning the OPC continues to exist irrespective of changes in ownership or management, providing continuity and stability to the business. 7. Tax Benefits: OPCs enjoy tax benefits similar to private limited companies, including lower corporate tax rates and eligibility for deductions and exemptions under the Income Tax Act, 1961. 8. Enhanced Credibility: Registering as an OPC enhances the credibility and trustworthiness of the business in the eyes of customers, suppliers, lenders, and stakeholders, fostering confidence and facilitating smoother business transactions. 9. Ease of Conversion: OPCs have the flexibility to convert into private limited companies or LLPs as the business grows and expands, providing scalability and adaptability to changing business needs. Experience the seamless process of OPC Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in establishing your OPC efficiently while you focus on building and growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

Registration Services

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, your trusted partner for seamless business registration solutions. Count on us to handle all your registration needs promptly and efficiently. Call us at +91 72999 72500 or visit https://filingpoint.com for expert assistance today. Introduction for Registration Services: Registration services play a pivotal role in establishing the legal identity and framework of private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) in India. From company incorporation to obtaining necessary licenses and permits, efficient registration services are crucial for ensuring compliance and initiating business operations. FilingPoint.Com offers comprehensive registration services tailored to meet the specific needs of businesses, empowering them to thrive in the competitive Indian market. Advantages of Registration Services for Private Limited Companies, OPCs, and LLPs: 1. Legal Compliance: Ensure adherence to regulatory requirements and legal compliance by obtaining all necessary registrations, licenses, and permits for your business, avoiding potential penalties or legal complications. 2. Established Legal Identity: Secure the legal identity of your business through proper registration, enhancing credibility and trustworthiness among clients, investors, and stakeholders. 3. Access to Government Schemes: Facilitate access to government schemes, subsidies, and incentives available exclusively for registered businesses, boosting growth and profitability. 4. Enhanced Marketability: Gain a competitive edge in the market by showcasing your registered status, demonstrating reliability and commitment to professionalism. 5. Facilitated Banking and Financing: Open business bank accounts, avail loans, and attract investments more easily with proper registration, facilitating financial transactions and business expansion. 6. Limited Liability Protection: Shield personal assets from business liabilities by opting for registration as a private limited company or LLP, offering limited liability protection to shareholders and partners. 7. Operational Continuity: Ensure uninterrupted business operations by securing necessary registrations and licenses, mitigating the risk of operational disruptions or closures due to non-compliance. 8. Tax Benefits: Avail tax benefits and incentives available to registered businesses, optimizing tax planning strategies and maximizing profitability. 9. Expert Guidance: Benefit from the expertise of professionals at FilingPoint.Com who possess in-depth knowledge of registration procedures and regulatory requirements, ensuring smooth and hassle-free registration process. Partner with FilingPoint.Com today to leverage the advantages of expert registration services tailored to your business needs. Call us at +91 72999 72500 or visit https://filingpoint.com for reliable assistance and support. Let us be your partner in achieving business success and growth.
Call Us Now +91 72999 72500

Trademark Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely Trademark Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Trademark Registration Services: Trademark Registration in India plays a pivotal role in protecting the brand identity and intellectual property of businesses, including private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs). It provides legal recognition and exclusive rights to use a trademark for goods or services, distinguishing them from competitors in the market. Registering a trademark is essential for building brand reputation, preventing infringement, and enhancing market visibility. Advantages for Trademark Registration Services for Private Limited Companies, OPCs, LLPs: 1. Legal Protection: Trademark Registration provides legal protection against unauthorized use or infringement of the trademark, enabling businesses to take legal action against infringers and counterfeiters. 2. Exclusive Rights: Registered trademark owners enjoy exclusive rights to use the trademark for their goods or services, preventing others from using similar marks that may cause confusion among consumers. 3. Brand Recognition: Trademark Registration enhances brand recognition and reputation, making it easier for customers to identify and choose products or services offered by the business. 4. Market Expansion: A registered trademark facilitates market expansion by providing a unique identity and distinguishing the business from competitors, attracting new customers and expanding market reach. 5. Asset Value: A registered trademark is an intangible asset that adds value to the business, enhancing its marketability, attracting investors, and increasing the overall valuation of the company. 6. Licensing Opportunities: Trademark Registration opens up opportunities for licensing and franchising arrangements, allowing businesses to generate additional revenue by granting others the right to use the trademark. 7. Global Protection: Trademark Registration in India provides protection within the country and can also serve as a basis for seeking trademark protection in other countries, facilitating international expansion. 8. Prevention of Domain Name Misuse: Registered trademarks help prevent domain name misuse and cyber-squatting, ensuring that the business’s online presence remains secure and consistent with its brand identity. 9. Competitive Advantage: A registered trademark provides a competitive advantage in the market by creating barriers to entry for competitors, establishing brand loyalty among customers, and strengthening market position. Experience the seamless process of Trademark Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in protecting your brand identity and intellectual property efficiently while you focus on growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

START WITH CONFIDENCE

Company Registration

Get your Private Limited company registered with expert guidance, from the first name check to incorporation.