GSTR-1 - 11-Oct-2026
GSTR-3B - 20-Oct-2026

Trending Articles

If your business details have changed, you may need to update your GST registration. This could include a change in your business’s legal name, constitution, principal place of business or additional place of business.

The process for making these changes has become more straightforward for certain categories of amendments. Guidance published by the Press Information Bureau (PIB) on 9 October 2026 explains that specified changes previously treated as core amendments can now be processed automatically by the GST system.

However, not every GST registration amendment is automatically approved. The processing route depends on the type of change and, for changes to the principal place of business, whether the registration was obtained under Rule 14A of the Central Goods and Services Tax (CGST) Rules, 2017.

This guide explains the changes, how to apply through Form GST REG-14, which documents you may need and what to check before submitting your application.

What changed in GST registration amendments in October 2026?

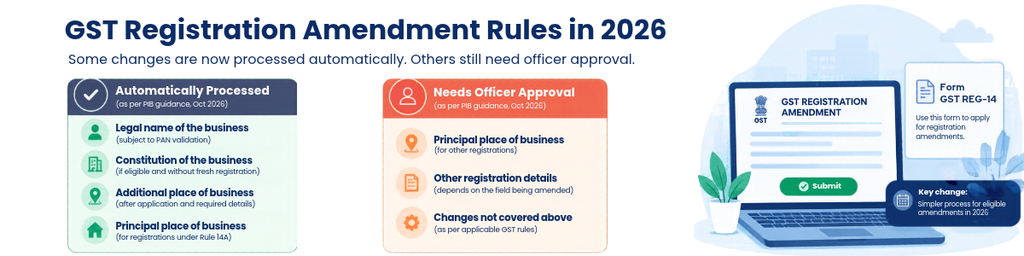
The PIB guidance published on 9 October 2026 explains the processing route for several GST registration amendments. The key distinction is whether the change is eligible for automatic system processing or requires approval from a tax officer.  

The changes described in the publication include:

  • Legal name of the business: eligible amendments can be processed automatically following submission and successful PAN validation.
  • Constitution of the business: eligible amendments can be processed automatically, provided the change does not require cancellation of the existing registration and a fresh registration under a different PAN.
  • Additional place of business: eligible amendments can be processed automatically after the application and required details are submitted.
  • Principal place of business: automatic processing applies to registrations covered by Rule 14A. For other registrations, officer approval continues to be required.

These changes can reduce manual intervention for eligible applications. They do not remove the need to submit accurate information or the supporting documents required for the amendment.

GST registration amendment: automatic processing vs officer approval

The following table summarises the processing routes described in the PIB’s October 2026 guidance.

Type of amendmentProcessing route described in the guidance
Legal name of the businessAutomatic processing, subject to successful PAN validation
Constitution of the businessAutomatic processing where the change is eligible and does not require fresh registration
Additional place of businessAutomatic processing
Principal place of business under Rule 14AAutomatic processing
Principal place of business for other registrationsTax officer approval continues to be required
Other registration detailsDepends on the field being amended and the applicable GST procedure

Important: The table summarises the published guidance. For a particular application, verify the current GST portal process and applicable legal provisions before filing.
A business may need to update its GST registration when its legal name changes. The name recorded in the GST registration should reflect the business’s valid legal particulars.

According to the PIB’s October 2026 guidance, the legal-name amendment can be processed automatically after an application is submitted through the GST portal and the PAN details are successfully validated.

How to apply

  1. Visit the official GST portal and log in.
  2. Navigate to the registration amendment service.
  3. Select the relevant business details and enter the revised legal name.
  4. Complete the required information and submit Form GST REG-14, where applicable.
  5. Complete the verification and submission steps shown on the portal.
  6. Retain the acknowledgement and check the updated registration details.

What should you check before filing?

Make sure the revised name is supported by the relevant legal records. A name change should not be treated as merely a spelling correction if it reflects a change in the legal identity of the business.

The portal’s validation process and the documents required may depend on the nature of the change. Review the current instructions before submitting the application.

How to add an additional place of business

A business may need to add another location to its GST registration when it opens a warehouse, branch, office, shop or another eligible business premises in the relevant state.

The PIB guidance states that an amendment to add an additional place of business can be processed automatically through the system after the application and required premises documents are submitted.

Steps to follow

  1. Log in to the GST portal.
  2. Open the registration amendment service.
  3. Select the section for additional places of business.
  4. Enter the new premises details accurately.
  5. Upload the required supporting documents.
  6. Submit the amendment application and save the acknowledgement.
  7. Check the registration details to confirm that the additional premises have been recorded.

Which documents may be required?

Depending on the premises and the portal’s current requirements, you may need documents such as:

  • Proof of ownership, where the premises are owned.
  • A rent or lease agreement, where applicable.
  • A consent letter or other acceptable evidence when the premises are used with another person’s permission.
  • Supporting address documents specified by the GST portal.

Do not assume that the same document will be accepted for every property arrangement. Check the applicable document requirements before filing.

Can you add multiple business locations?

The PIB guidance states that there is no need to wait for an earlier additional-place amendment to be approved before submitting another such application where the amendment is eligible for automatic processing. Ensure that every location is entered correctly and supported by the required evidence.

How to change the principal place of business

The principal place of business is the primary business location recorded in the GST registration. A business may need to update it when it relocates its main office, shop, factory or other principal premises.

The processing route depends on the type of GST registration.

For registrations under Rule 14A

The PIB guidance explains that an amendment to the principal place of business for a registration obtained under Rule 14A of the CGST Rules, 2017, can be processed automatically through the system.

The applicant must submit the amendment application and the required proof of the new premises through the GST portal.

For other GST registrations

For registrations other than those obtained under Rule 14A, the principal-place-of-business amendment continues to require approval from the proper officer, according to the published guidance.

The guidance describes the following process for a normal taxpayer registered under Rule 9:

  • If no discrepancy is found, the officer is to approve the application within 15 days of the application.
  • If a discrepancy is identified, the officer may issue a show-cause notice within the specified period.
  • The taxpayer must respond within the prescribed period, and the officer then takes further action according to the applicable procedure.

These are procedural timelines described in the published guidance. Follow the dates and instructions shown in any notice or communication issued for your own application.

What should you prepare?

Before submitting the amendment, check the new address, premises evidence, effective date and consistency of the information entered in the application. Incomplete or inconsistent information may lead to a request for clarification or further action.

Change in business constitution: will you need a new GST registration?

A change in business constitution may arise when the ownership or legal structure of a business changes. The GST implications depend on the nature of the change and whether the business continues under the same PAN.

The October 2026 PIB guidance identifies eligible constitution-related amendments as changes that can be processed automatically. This should not be interpreted to mean that every change in constitution can be handled by amending the existing GST registration.

If the change results in a different PAN, a fresh GST registration may be required rather than an amendment to the existing registration. The existing registration may also need to be cancelled, depending on the circumstances.

Before filing, establish whether the change is a modification within the existing legal identity or the creation of a different taxable person. This distinction is particularly important when moving between business structures.

For example, a change that preserves the same PAN may be treated differently from a restructuring that creates a new legal entity with a different PAN. Obtain appropriate professional advice if the legal effect of the restructuring is unclear.

Which form is used for GST registration amendments?

The form identified in the PIB guidance for applying to amend registration particulars is Form GST REG-14.

The form is used to submit the proposed changes and the supporting information through the GST common portal. The documents and details required depend on the amendment being requested.

A typical application may involve:

  1. Identifying the GSTIN and the details to be changed.
  2. Selecting the appropriate amendment fields.
  3. Entering the revised information.
  4. Uploading the required supporting documents.
  5. Completing verification and submitting the application.
  6. Saving the acknowledgement or application reference number.
  7. Checking the status and updated registration particulars.

Use the instructions available on the live GST portal because the available fields and supporting-document requirements can vary according to the amendment type.
GST Registration Chennai

Documents required for GST registration amendment

There is no single document list that applies to every GST amendment. The evidence required depends on the information being changed.

Amendment typeDocuments or information to check
Legal nameLegal records supporting the revised name and matching PAN information
Additional place of businessAcceptable proof of the premises, such as ownership, lease, rent or consent documentation where applicable
Principal place of businessProof of the new principal premises and other information required by the portal
Constitution of businessRelevant legal records showing the change and confirmation of whether the PAN remains the same
Other registration detailsSupporting evidence specified for the particular field

This table is a practical preparation guide, not a substitute for the official document checklist. Check the requirements shown in the GST portal and the applicable instructions before uploading documents.

Common reasons an amendment may need further attention

Problems can arise when:

  • The address entered does not match the supporting evidence.
  • The document is incomplete or unclear.
  • The revised legal name does not match the information available for PAN validation.
  • The amendment selected does not accurately describe the change.
  • A change in constitution has been treated as an ordinary amendment even though a different PAN is involved.
  • The taxpayer has not responded to a notice within the prescribed period.

Review the application carefully before submission. Automatic processing does not mean that incorrect or unsupported information can be accepted without validation.

How to check the status of a GST amendment

After submitting Form GST REG-14, retain the acknowledgement or application reference number and monitor the application through the GST portal.

A practical follow-up process is:

  1. Log in to the GST portal.
  2. Open the relevant registration or application-status service.
  3. Enter the details requested by the portal.
  4. Review the current status and any communication issued.
  5. If the amendment has been processed, verify the updated registration particulars.
  6. If a notice or clarification request is issued, read it carefully and respond within the applicable deadline.

The exact status labels and steps displayed may depend on the application and portal interface. Use the live portal as the source of your application’s current status.

What should you do if a GST amendment notice is issued?

An amendment application may require further attention if the officer identifies a discrepancy or the supporting documents are insufficient. This is particularly relevant to amendments for which officer approval continues to apply.

If you receive a notice:

  • Read the reason stated in the notice.
  • Identify the specific information or evidence requested.
  • Check whether the original application contains an error.
  • Prepare a clear response supported by relevant documents.
  • Submit the response through the prescribed portal process within the deadline.
  • Save the acknowledgement and monitor the subsequent status.

Do not ignore a notice simply because some categories of amendments are now processed automatically. The applicable process depends on the type of amendment and the circumstances of the application.

What should you do after the amendment is processed?

Once the amendment has been processed, review the GST registration details to make sure the change has been recorded correctly.

Depending on the amendment, you should check:

  • The legal name and other business particulars.
  • The principal and additional places of business.
  • The GST registration certificate and related records.
  • Whether invoices, accounting systems and internal business records need to be updated.
  • Whether any other registrations, licences or business records also need to be amended.

For an address change, make sure your business records and operational documents reflect the correct premises. For a legal-name change, review the relevant records used for invoicing, banking and commercial transactions.

Updating GST registration does not automatically update every other government registration or private business record. Review each relevant requirement separately.

Practical checklist before filing Form GST REG-14

Use this checklist before submitting an amendment application.

  • Identify exactly which GST registration detail has changed.
  • Confirm whether the change can be made through an amendment or requires fresh registration.
  • Check whether the principal-place-of-business change falls under Rule 14A.
  • Gather the documents required for the selected amendment.
  • Check that names, addresses and other details are consistent across the application and supporting evidence.
  • Enter the correct effective date and reasons, where requested.
  • Complete the portal’s verification and submission process.
  • Save the acknowledgement or application reference number.
  • Monitor the application and respond promptly if further information is requested.
  • Verify the updated registration details after processing.
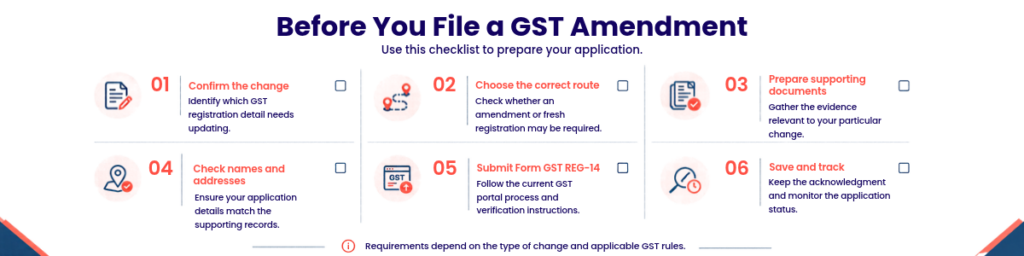
Before You file a GST Amendment

Common Questions About GST Registration Amendments

1. Which GST registration amendments can be processed automatically in 2026?

The PIB guidance published on 9 October 2026 identifies eligible amendments involving the legal name, constitution of the business and additional place of business as changes that can be processed automatically. Principal-place-of-business amendments are also covered by the automatic route for registrations under Rule 14A.

2. Does every principal-place-of-business amendment receive automatic approval?

No. The published guidance distinguishes registrations under Rule 14A from other registrations. For registrations outside Rule 14A, approval by the proper officer continues to be required.

3. Which form is used to amend GST registration details?

The form identified in the PIB guidance is Form GST REG-14. Check the GST portal for the current application process and the documents required for your particular amendment.

4. Can I add another business location without waiting for an earlier amendment?

The PIB guidance states that where an additional-place amendment is eligible for automatic processing, the taxpayer does not need to wait for an earlier such application to be approved before filing another one.

5. Is a new GST registration needed after a change in business constitution?

It depends on the legal effect of the change. If it results in a different PAN, a fresh GST registration may be required. Confirm the applicable treatment before attempting to amend the existing registration.

6. What should I do if my amendment application requires clarification?

Read the notice, identify the discrepancy, prepare the requested supporting evidence and submit your response through the prescribed process within the applicable deadline.

7. Should I check my GST registration after an amendment is processed?

Yes. Verify that the revised details are correct and update relevant business records separately wherever necessary.

Final Takeaway

The October 2026 guidance makes the processing route clearer for several GST registration amendments. Eligible changes involving the legal name, constitution of the business and additional place of business can be processed automatically. Principal-place-of-business amendments follow the automatic route for registrations under Rule 14A, while other registrations continue to require officer approval.

Before filing, confirm the type of amendment, check whether a fresh registration is necessary, prepare the required evidence and verify the outcome on the GST portal.

Need help with GST registration or compliance? FilingPoint can help you understand the amendment process, prepare the relevant information and identify the next steps based on your business circumstances.

Disclaimer: This article provides general information and is not legal or tax advice. GST procedures and requirements may change. Verify the current rules, notifications and portal instructions before filing.
Freelancing has become a serious business model in India. Software developers, designers, consultants, digital marketers, video editors, writers and other professionals increasingly work with clients across India and overseas.

But as freelance income grows, questions about GST become harder to ignore.

A designer may receive payments from clients in India and the United States. A developer may earn through a foreign freelancing platform. A consultant may receive payments in US dollars but maintain a bank account in India. Another freelancer may earn less than the usual registration threshold and wonder whether GST registration is necessary at all.

These situations are not identical.

The answer depends on several factors: the freelancer’s aggregate turnover, the type of service supplied, the location of the customer, the place of supply, the payment arrangement and whether any special registration provision applies.

This guide explains how to approach GST as a freelancer in India, including registration, foreign clients, export of services, Letter of Undertaking (LUT), invoices, records and ongoing compliance.

Important: This article provides general information, not a personalised tax opinion. GST provisions and administrative procedures can change. Check the current official GST and CBIC guidance before acting, especially where foreign-client contracts, intermediary services or cross-border payment arrangements are involved.

What does GST mean for a freelancer?

Goods and Services Tax is an indirect tax framework that applies to specified supplies of goods and services. A freelancer who supplies services independently may be treated as a supplier for GST purposes, depending on the facts and applicable law.

The word “freelancer” does not create a separate blanket exemption from GST.

For example, consider three professionals:

  • A graphic designer serving Indian businesses.
  • A software developer supplying services directly to a company in the United States.
  • A consultant who works through an agency and receives payment from an Indian business.

Their GST treatment may differ because their customers, contracts, service arrangements and places of supply may differ.

GST is also separate from income tax. A freelancer may need to consider income-tax reporting even when no GST is charged on a particular supply. Likewise, an income-tax presumptive scheme does not, by itself, decide whether GST registration is required.

The correct starting point is to identify what service is being supplied, who receives it, how much aggregate turnover the freelancer has and whether a registration provision applies.

What is the GST registration threshold for freelancers?

Section 22 of the Central Goods and Services Tax Act, 2017 establishes a general registration threshold, subject to the Act, notifications and other applicable conditions. The commonly applicable threshold for service suppliers in many states is ₹20 lakh of aggregate turnover in a financial year, with a lower threshold applying in certain specified states.

However, freelancers should not use one number without checking their circumstances.

The relevant questions include:

  1. In which state or union territory is the freelancer located?
  2. What supplies form part of aggregate turnover?
  3. Does the freelancer provide only services, or also goods?
  4. Are any compulsory-registration provisions applicable?
  5. Is the person relying on a specific exemption or notification?

Aggregate turnover is a legal concept. It is not always identical to the cash deposited into a bank account, the profit shown in an income-tax return or the amount left after deducting business expenses.

Under the CGST Act, aggregate turnover is calculated on an all-India basis for supplies of persons having the same PAN, subject to the statutory definition and exclusions. It generally includes taxable supplies, exempt supplies and exports, while specified taxes and certain inward supplies are excluded.

Does income from foreign clients count towards the threshold?

Do not automatically exclude foreign-client income merely because the payment arrives in a foreign currency or the customer is outside India.

Export supplies are part of the GST framework, and the statutory definition of aggregate turnover includes exports. Whether a particular transaction qualifies as an export of services is a separate legal test.

For example, if a freelancer supplies services to Indian clients and overseas clients, the relevant turnover assessment may need to consider both. A professional should not calculate the threshold using only domestic receipts without checking the legal definition.

Does working with clients in another Indian state automatically require registration?

The answer depends on the applicable provisions and the nature of the supply. The general registration threshold and the rules for inter-State supplies must be read together with relevant exemptions and notifications.

Freelancers should not rely solely on a social-media comment saying that every inter-State service requires registration, or that every freelancer below a particular amount is exempt. The applicable notification and facts matter.

For a registration decision, check the current CGST Act and relevant notifications or obtain advice from a qualified GST practitioner.

Is GST registration compulsory for every freelancer?

No. Being a freelancer does not, by itself, mean that registration is immediately compulsory in every case.

A freelancer must assess the general threshold as well as the categories of persons who may be required to register under Section 24 and any relevant notifications or exemptions.

Registration can also be a business decision in some circumstances, but voluntary registration has consequences. Once registered, a person generally has ongoing compliance responsibilities, including applicable returns and record-keeping, even if the business has a low level of activity.

Before choosing voluntary registration, consider:

  • Whether registration is legally required.
  • Whether clients need a GST registration number or tax invoice.
  • Whether input tax credit is relevant to the business.
  • The cost and time of maintaining compliance.
  • Whether the freelancer’s supplies are domestic, exported or a mixture.
  • Whether registration could create obligations that outweigh the immediate benefit.

Do not register simply because another freelancer has done so. Equally, do not delay registration when the law requires it.

GST for freelances with US clients

Do freelancers have to charge GST to foreign clients?

This is one of the most misunderstood areas of freelance taxation.

A payment from a foreign client is not automatically an export of services for GST purposes. To qualify, the supply must satisfy the conditions in Section 2(6) of the Integrated Goods and Services Tax Act, 2017.

Broadly, the conditions require that:

  1. The supplier is located in India.
  2. The recipient is located outside India.
  3. The place of supply is outside India.
  4. Payment is received in convertible foreign exchange or Indian rupees wherever permitted by the Reserve Bank of India.
  5. The supplier and recipient are not merely establishments of a distinct person in the circumstances covered by the provision.

The exact statutory wording and applicable exceptions should be checked before relying on export treatment.  

If all the relevant conditions are satisfied, the service may qualify as an export of services. Exports are treated as zero-rated supplies under the IGST framework, subject to the applicable rules.

Zero-rated does not mean “ignore GST.” Registration, documentation, invoicing and return requirements may still apply.

Example: an Indian software developer serving a US company

Suppose an Indian software developer supplies development services directly to a US company. The developer should review the contract, identify the actual recipient, establish the place of supply, check the payment terms and determine whether the statutory export conditions are satisfied.

If the conditions are met, the transaction may qualify as an export of services. The developer can then consider the applicable zero-rated supply route, including an LUT where eligible and appropriate.

If the developer is actually acting as an intermediary, or the arrangement involves another party receiving the service, the analysis may be different. The customer’s overseas address alone does not settle the question.

What is an LUT, and why might a freelancer need one?

A Letter of Undertaking, commonly called an LUT, is a declaration filed through the GST system that allows an eligible registered person to make qualifying exports without payment of integrated GST, subject to the applicable requirements.

The relevant form is GST RFD-11.

The official GST Portal guidance explains the online process through Services → User Services → Furnish Letter of Undertaking (LUT). The portal generates an acknowledgement reference after successful filing. 

An LUT is not a substitute for registration where registration is required. Nor does it turn an ordinary domestic supply into an export.

A freelancer should first determine whether the supply qualifies as an export and whether the person is eligible to use the LUT route. The LUT should be filed for the relevant financial year in accordance with the applicable requirements.

What if the freelancer does not file an LUT?

The consequences depend on the transaction, timing and applicable provisions. Do not assume that filing an LUT later automatically cures every earlier invoice or tax issue.

If export invoices have already been issued, review the dates, return treatment, payment status and applicable rules with a GST professional before attempting corrections.

How should a freelancer invoice a foreign client?

An invoice should accurately describe the services supplied and reflect the transaction’s actual tax treatment.

For an export of services made under an LUT without payment of integrated GST, the applicable invoice endorsement and prescribed details must be followed. The GST invoice rules contain specific export-invoice requirements; the exact wording and fields should be checked against the current rules.

A freelancer’s invoice process should normally include:

  • Correct legal name and address of the supplier.
  • GSTIN, where applicable.
  • Invoice number and date.
  • Customer’s legal name and address.
  • Clear description of the service.
  • Currency and agreed consideration.
  • Applicable tax treatment and required export endorsement.
  • Contract or project reference where useful.
  • Payment terms and due date.
  • Relevant banking or payment instructions.

Do not add GST merely because a software template automatically inserts a tax rate. Equally, do not label every foreign-client invoice “zero-rated export” without checking the legal conditions.

A freelancer should retain the invoice alongside the contract, statements of work, evidence of delivery, payment records and supporting remittance documentation.

What if a foreign client pays in Indian rupees?

Payment currency is an important part of the export-of-services analysis, but it is not the only condition.

The statutory definition recognises receipt in convertible foreign exchange or in Indian rupees wherever permitted by the Reserve Bank of India. That means a payment in INR is not automatically disqualifying in every circumstance, but the relevant permitted payment route and supporting evidence need to be established.

For example, payment through an authorised arrangement may have a different evidentiary position from a domestic transfer where the relationship between the payer and overseas customer is unclear.

Freelancers should keep the contract, invoice, payment advice and bank or payment-platform records. If a platform deducts fees before settlement, preserve the gross transaction information and the fee breakdown as well.

Do not rely on a general online answer that says all INR receipts qualify—or that none can qualify. Check the applicable RBI-permitted route and the GST export conditions for the actual transaction.

What records should freelancers keep?

Good records make GST compliance easier and help explain transactions if a question arises.

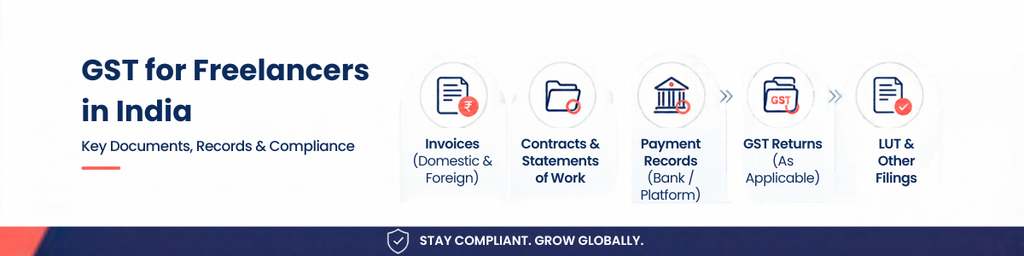
Depending on the business, maintain:

  • Client contracts and statements of work.
  • Invoices and credit notes.
  • Bank statements and payment-platform reports.
  • Foreign remittance or payment advice available from the bank or authorised provider.
  • LUT filing acknowledgement, where applicable.
  • GST registration and return acknowledgements.
  • Purchase invoices for business expenses.
  • Input-tax-credit records, where applicable.
  • Correspondence explaining changes to the scope or recipient of the service.
  • A reconciliation between invoices, amounts received and GST returns.

Do not assume that one specific document, such as a FIRC or FIRA, is universally required in exactly the same form for every payment route. What is available and what is legally relevant may depend on the banking or payment arrangement. Ask the authorised bank or payment provider what documentation it can issue and confirm the GST evidence requirements for your transaction.

GST Registration Chennai

Do freelancers need to file GST returns if they charge no GST?

Potentially, yes.

A registered freelancer may still have return-filing obligations even when eligible exports are made without payment of IGST under an LUT. Zero-rated supplies are not automatically omitted from GST reporting.

The precise returns and frequency depend on the taxpayer’s registration, filing scheme and applicable requirements. A freelancer should confirm the current return obligations on the GST Portal and ensure that invoices, export values, tax liability and input tax credit reconcile.

A “zero GST invoice” and a “no compliance obligation” are not the same thing.

Missing a required return can create late fees, notices and other consequences, depending on the circumstances. A freelancer should set reminders and retain acknowledgements after filing.

Can a freelancer claim input tax credit or a refund?

The answer depends on eligibility, the nature of the expense, the credit conditions and the refund provisions.

An eligible registered exporter may be able to claim a refund of accumulated eligible input tax credit on qualifying zero-rated supplies made without payment of tax under a bond or LUT, subject to the law and prescribed procedure.

However, not every purchase automatically qualifies for credit. The expense must satisfy the relevant conditions, and blocked credits and other restrictions may apply. Personal purchases should not be treated as business input tax credit merely because the freelancer has a GSTIN.

A freelancer who exports all services and has little or no domestic output tax may have a different credit position from someone who supplies both domestic and overseas customers. Refund eligibility and the amount recoverable should be assessed from the records, not assumed.

What about freelancers working through platforms or agencies?

A platform payment does not, by itself, tell you who the recipient of the service is for GST purposes.

A freelancer may be supplying a service directly to an overseas customer, providing a service to an Indian agency, or working under a platform arrangement with separate contractual roles. The platform may collect money, deduct fees or facilitate delivery without necessarily being the recipient of the underlying service.

Review the contract and terms of service. Identify:

  • Who hired the freelancer?
  • Who is legally receiving the service?
  • Who is responsible for paying the freelancer?
  • Is the platform an agent, intermediary or contracting party?
  • Where is the recipient located?
  • What service is actually supplied?

The answers may affect the place-of-supply and export analysis. Where an intermediary arrangement is possible, seek professional review before applying export treatment.

Common GST mistakes freelancers should avoid

Mistake 1: Assuming overseas income never counts towards turnover.
Aggregate turnover must be calculated under the statutory definition, which includes exports.

Mistake 2: Treating every foreign client as an export.
The statutory export conditions must be satisfied.

Mistake 3: Confusing zero-rated with exempt.
Zero-rated exports remain within the GST framework and may involve reporting and input-tax-credit provisions.

Mistake 4: Using an LUT as a replacement for registration.
An LUT is a route for eligible registered persons; it does not remove a registration requirement.

Mistake 5: Forgetting returns because no GST was charged.
Registered taxpayers may still have filing obligations.

Mistake 6: Treating income-tax rules as GST rules.
A presumptive income-tax provision and GST registration are separate legal questions.

Mistake 7: Relying on payment currency alone.
The recipient, place of supply, contract and permitted payment route all matter.

Mistake 8: Ignoring platform fees and reconciliation.
Keep gross transaction values, deductions and net receipts clear in your records.

A practical GST checklist for freelancers

Before deciding how to invoice, work through this checklist:

  1. List your services and customer types.
  2. Calculate aggregate turnover under the GST definition.
  3. Check the registration threshold applicable to your circumstances.
  4. Review compulsory-registration provisions and relevant notifications.
  5. For each foreign-client service, check all export-of-services conditions.
  6. Review the contract to determine who receives the service.
  7. Confirm the permitted payment route and retain evidence.
  8. If registered and eligible, assess whether an LUT is appropriate.
  9. Use invoices that match the actual transaction and prescribed rules.
  10. File the applicable returns and reconcile them with invoices and payments.
  11. Review input tax credit and refund eligibility before claiming.
  12. Get professional advice for intermediary services, mixed supplies or unclear cross-border arrangements.

Frequently asked questions

1. Is GST registration mandatory for every freelancer in India?

No. Registration depends on aggregate turnover, the nature of supplies, the applicable threshold and any compulsory-registration provision or exemption. Freelancers should assess their actual circumstances rather than assume all freelancers must register immediately.

2. Does foreign-client income count towards the GST threshold?

Exports form part of the statutory aggregate-turnover definition. A freelancer should not automatically exclude overseas receipts when calculating turnover.

3. Do freelancers need to charge 18% GST to US clients?

Not automatically. If the supply qualifies as an export of services, it may be zero-rated subject to the applicable conditions and procedures. The service arrangement and place of supply must be checked first.

4. What is an LUT for a freelancer?

An LUT is a Letter of Undertaking filed through Form GST RFD-11. An eligible registered exporter can use it to make qualifying exports without payment of integrated GST, subject to applicable rules.

5. Can I file an LUT without GST registration?

An LUT does not replace GST registration. The freelancer must first establish the applicable registration position and eligibility to use the LUT route.

6. Do I need GST returns if all my income comes from foreign clients?

If you are registered, you may still need to file the applicable returns and report qualifying exports. The exact filing obligations depend on your registration and the applicable rules.

7. Can a freelancer claim a refund of GST paid on a laptop or software?

Possibly, if the freelancer is registered and the expense and credit satisfy the relevant conditions. Blocked-credit rules and refund eligibility must be considered; not every purchase automatically qualifies.

8. Does receiving money through a payment platform make a transaction an export?

Not by itself. The recipient, contractual arrangement, place of supply, payment route and other export conditions must be assessed.

9. Is GST the same as income tax for freelancers?

No. GST and income tax are separate tax systems. An income-tax treatment does not, by itself, settle GST registration or export eligibility.

10. What should I do if I have already issued foreign invoices without an LUT?

Review the invoice dates, registration status, payment records and applicable rules with a qualified GST professional. Do not assume a later filing automatically resolves every earlier transaction.

How FilingPoint can help

Freelancers often begin with simple client invoices, then gradually take on larger projects, foreign contracts and recurring payments. As the business grows, GST decisions can become more complex.

FilingPoint supports businesses with GST registration and related compliance services. If you are unsure whether registration is required, whether your overseas services qualify as exports, or what filing steps apply after registration, review your facts before choosing a compliance route.

Need help understanding your GST registration and compliance requirements?

Phone: +91 72999 72500
Email: enquiry@filingpoint.com

Choosing a legal structure is an important decision when starting a business. A sole proprietor may begin with a small consultancy, a partnership may start with two founders, or a startup may register as a Limited Liability Partnership (LLP) because it suits the initial business model.

But a business does not remain the same forever.

A small enterprise may start hiring employees, take on larger clients, seek outside investment or expand into new locations. The founders may then discover that their existing structure no longer suits their plans. A private limited company may also decide that an LLP better fits its ownership and operating model, subject to the applicable legal and tax conditions.

This leads to a common question: Can you change your business structure after registration, or must you start again?

The answer depends on the legal form you currently have, the form you want to adopt and the route permitted by law. It is not safe to assume that every business can simply “convert” by filing one form with the Ministry of Corporate Affairs (MCA).

This guide explains the main routes available in India, the checks to complete before conversion, and the registrations and records that may need attention afterwards.

What does changing a business structure mean?

Changing a business structure means moving from one legal form of business to another. Examples include:

  • A sole proprietorship moving its business into a private limited company.
  • A partnership firm converting into an LLP.
  • An LLP registering as a company under the applicable legal route.
  • A One Person Company (OPC) becoming a private limited company.
  • A private limited company converting into an LLP, where eligible.
  • A private limited company converting into a public company.

These changes are different from changing a company’s name, registered office, directors, shareholders or business activities. Those actions may require their own approvals and filings, but they do not necessarily change the legal form of the entity.

For example, a private limited company can update its permitted business activities where legally appropriate without becoming an LLP. Likewise, changing a proprietorship’s trade name does not create a separate incorporated entity.

The first step is therefore to identify the change you actually need.

Why might a business want to change its structure?

There is no single reason for restructuring. Common triggers include the following.

Bringing in investors

A startup may want to issue shares, create an employee stock option plan or prepare for an equity investment. A private limited company is often considered for these goals, although the correct structure depends on the investor, business model and applicable rules.

Managing liability

A proprietor and the business are not separate legal persons in the same way as a company. An LLP or company may offer a separate legal identity and limited liability, subject to statutory exceptions and the facts of the case.

Reducing or changing compliance responsibilities

A founder may find that a company’s governance and filing obligations no longer match the scale or operating needs of the business. An LLP may be worth evaluating, but it is not automatically cheaper or simpler in every situation. Conversion itself may involve professional fees, filings, tax analysis and changes to registrations.

Adding co-founders or changing ownership

A sole proprietor may wish to formalise ownership with another founder. A partnership may want to introduce more structured governance, while an established company may consider a different ownership or capital arrangement.

Preparing for expansion

Larger customers, lenders, tenders, licences or business partners may have preferences or eligibility requirements relating to the supplier’s legal form. Confirm the actual requirement rather than restructuring based on assumptions.

Practical point: Changing a structure should solve a defined business problem. Do not convert only because another structure is popular or because someone claims it guarantees lower tax or fewer compliance obligations.

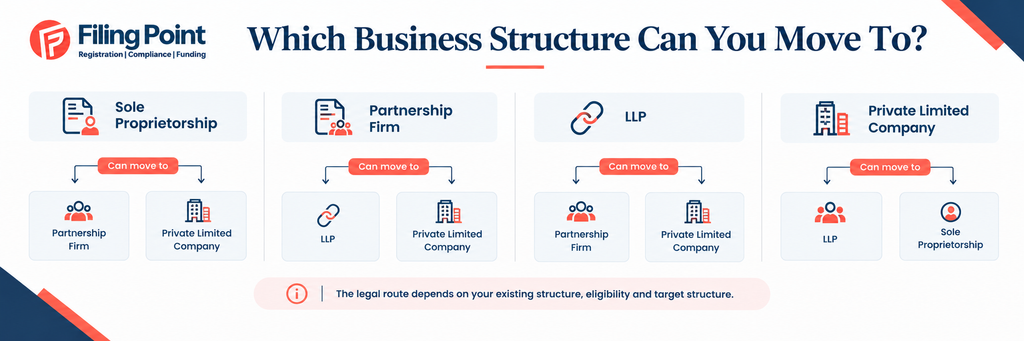
Which business structures can be changed?

The table below is a starting guide, not a determination that every business is eligible.

Existing structurePossible target structureGeneral route
Sole proprietorshipPrivate limited companyUsually incorporate a new company and transfer the business
Sole proprietorshipLLPUsually form an LLP and transfer the business
Partnership firmLLPStatutory conversion route may be available if conditions are met
Partnership firmCompanyRegistration under the applicable Companies Act route may be available
LLPPrivate limited companyRegistration under the Companies Act route may be available, subject to requirements
OPCPrivate limited companyCompany conversion process under applicable company law
Private limited companyPublic limited companyCompany-class conversion under the Companies Act
Private limited companyLLPStatutory conversion route may be available if the conditions are met
Private limited companyOPCPossible only if current legal requirements and eligibility conditions are satisfied

The legal route, approvals, forms and consequences differ. Confirm the latest MCA requirements before starting the transaction.

Business Structure Conversion

Conversion is not always the same as creating a new business

This is one of the most important distinctions in business restructuring.

When a statutory conversion route exists

Certain types of firms and entities can register or convert into another form under a specific legal provision. For example, the Companies Act, 2013 provides for conversion of companies already registered under the Act into another class of company, subject to the applicable requirements. Section 366 and the Companies (Authorised to Register) Rules, 2014 provide a route for specified entities, including LLPs and partnership firms, to register as companies. The LLP Act also provides conversion routes for specified entities.

The correct route depends on the existing entity and target structure. Relevant provisions include Section 18 and Section 366 of the Companies Act, 2013, and the applicable schedules of the Limited Liability Partnership Act, 2008.  

When a new entity must be formed

A sole proprietorship is not a company registered under the Companies Act. It generally cannot be transformed into a private limited company by simply changing its registration type. Instead, the proprietor incorporates a company and transfers the business or relevant assets, contracts and operations to it under an appropriately structured transaction.

That transfer needs careful planning. It may involve agreements, consent from counterparties, asset-transfer documentation, employee arrangements, tax analysis and fresh or amended registrations.

Why the distinction matters

The two approaches can have different effects on:

  • The identity of the legal entity.
  • Existing debts and obligations.
  • Ownership of assets and intellectual property.
  • Customer and supplier contracts.
  • Bank accounts and borrowing arrangements.
  • Tax treatment and potential tax costs.
  • Licences, permits and registrations.
  • Business continuity and documentary evidence.

Do not assume that every licence, tax registration, contract or bank account automatically continues unchanged. Check each one separately.

How to choose the right conversion route

Before selecting forms or preparing documents, answer these questions.

Check the actual registration documents. A business using a trade name may still be a proprietorship. An LLP has an LLP identification number (LLPIN), while a company has a Corporate Identity Number (CIN). A partnership firm may have a partnership deed and, where applicable, registration with the relevant state authority.

Do not base the decision solely on the business name, GST certificate or Udyam registration.

Step 2: Define the target structure

Decide whether the goal is to become a private limited company, LLP, public company or another permitted form. The reason matters. A funding requirement, liability concern and desire to reduce administrative work may lead to different conclusions.

Step 3: Check statutory eligibility

Review the conditions applying to the specific conversion. Depending on the route, these may concern ownership, consent of partners or shareholders, creditors, security interests, company filings, capital, constitutional documents or other statutory conditions.

For example, an LLP-to-company registration route under Section 366 is not the same as a private-company-to-LLP conversion under the LLP Act. Do not use a generic “conversion checklist” for both.

Step 4: Review pending compliance

Before proceeding, check whether returns, financial statements, annual filings, tax returns, statutory registers or other obligations are outstanding. A conversion plan should include a method for addressing defaults and determining which obligations remain due.

The exact requirements depend on the entity and transaction. Review the MCA record and relevant tax records instead of assuming that conversion automatically resolves past non-compliance.

Step 5: Review tax implications before transferring assets

Identify the business assets, stock, receivables, liabilities, goodwill, intellectual property and capital balances. Ask a tax professional to assess the proposed transfer and the applicable conditions.

Some transactions may qualify for specific tax treatment if statutory conditions are met. That treatment should never be assumed merely because the parties call the transaction a “conversion”. The Income Tax Department’s guidance on Section 47 describes conditions for certain forms of business succession and company-to-LLP conversion. https://www.incometaxindia.gov.in/w/capital-gain

Step 6: Map contracts and registrations

Prepare a list of every registration, licence, contract, bank facility and online account linked to the existing entity. Identify whether it must be transferred, amended, surrendered or obtained afresh.

Step 7: Prepare a written implementation plan

Set out the approvals, filings, transaction documents, responsible people and dependencies. A conversion should not be treated as complete merely because a new certificate has been issued.

GST Registration Chennai

What happens to GST, PAN, bank accounts and other registrations?

This is a major area of risk because business owners sometimes focus on the MCA filing and overlook operational continuity.

PAN and income-tax records

A new legal entity may require its own PAN and tax registrations. Whether a PAN changes or a new one is required depends on the legal route and whether the same legal person continues. A proprietorship-to-company transfer, for example, should not be treated as though the proprietor and company were the same taxpayer.

Review income-tax filings, tax credits, advance tax, TDS/TCS obligations, books of account and any tax attributes before the transition.

GST registration

GST treatment depends on the legal structure, the transaction and applicable GST rules. A transfer of a business as a going concern, a transfer of assets, or a change in the person carrying on the business can have different implications. The old registration should not simply be reused for a different legal person without checking the applicable requirements.

Plan for outstanding returns, input tax credit, stock, invoices, customer advances, tax liabilities and the effective date of the transition. Confirm whether a new registration, amendment, transfer of eligible credit or cancellation process applies in the specific case.

 Bank accounts and loans

Banks may require updated incorporation documents, KYC, board or partner resolutions, fresh mandates and changes to account ownership. Existing loans, guarantees, security interests and working-capital facilities may require lender consent or revised documentation.

Never assume that a bank account or loan automatically moves to the new structure.

UDYAM Registration

Udyam/MSME registration

Review the Udyam registration details after restructuring. The correct action depends on the nature of the change and the portal’s current requirements. Do not assume that the old registration automatically reflects a new legal entity or ownership structure.

Licences, contracts and intellectual property

Review trade licences, professional or sector-specific approvals, lease agreements, vendor contracts, customer contracts, trademarks, domain names, software licences and insurance policies. Some may need amendments, assignments, new applications or counterparty consent.

The list should be prepared before the effective date, not after the business has already moved.

Can you change a company’s business activities without changing its structure?

Yes, changing business activities is different from changing the legal structure.

A private limited company may be able to expand into a new line of business without becoming an LLP or another type of entity. However, the proposed activity must be permitted by the company’s constitutional documents and comply with applicable law. The company may need to alter its memorandum, pass the required resolutions or obtain sector-specific approvals, depending on the circumstances.

For instance, a company incorporated for software services may want to add product sales. The founders should review the objects and applicable regulatory requirements rather than assume that a full legal-structure conversion is needed.

FilingPoint lists a separate Business Nature Change service in its service menu. Use the correct process for the change you actually need. 

Tax implications: what should founders review?

Tax consequences depend on the route, assets transferred, consideration, ownership and statutory conditions. There is no universal “tax-free conversion” rule covering every structure change.

Before proceeding, review:

  • Whether assets are transferred to a new entity or vest under a statutory conversion.
  • Whether the transaction involves a sale, slump sale, contribution or another transfer mechanism.
  • Whether the relevant conditions for any claimed tax relief are satisfied.
  • The treatment of inventory, receivables, fixed assets, goodwill and intellectual property.
  • GST consequences of the business or asset transfer.
  • Existing tax liabilities, tax credits and pending assessments.
  • Whether accumulated losses or other tax attributes can continue to be used.
  • Stamp duty and state-specific costs, where applicable.

The Income Tax Department’s published material on Section 47 identifies conditions relevant to certain successions of proprietary concerns and firms, as well as certain conversions of unlisted companies into LLPs. The conditions are specific and may include requirements relating to assets, liabilities, ownership, consideration, turnover or continuing ownership. 

Do not make a tax decision from a blog checklist alone. Ask a qualified tax professional to assess the exact transaction and applicable law as of the proposed effective date.

Documents to prepare before restructuring

The final document list will depend on the legal route, but the initial review often includes:

  • Certificate of incorporation, partnership deed or existing registration records.
  • Memorandum and Articles of Association, LLP agreement or other constitutional documents.
  • PAN, GST registration and Udyam details.
  • Latest financial statements and relevant tax returns.
  • List of assets, liabilities, receivables and stock.
  • Details of loans, charges, guarantees and security interests.
  • Partner or shareholder details and ownership percentages.
  • Board, shareholder or partner approvals, as applicable.
  • Major customer, supplier, employment and lease agreements.
  • Intellectual-property records and licences.
  • Details of pending litigation, notices, assessments or statutory defaults.
  • Proposed transfer or conversion documents and a transition plan.

These are review categories, not a universal mandatory list. Use the applicable MCA form instructions and professional advice to confirm what must be filed.

Common mistakes to avoid

Assuming all structures can be converted directly

They cannot. A sole proprietorship, partnership firm, LLP and company have different legal characteristics. First confirm whether a statutory route exists.

Treating incorporation as the end of the process

A new certificate does not resolve every contract, tax registration, bank mandate or licence. The transition must be managed across the business.

Ignoring tax until after the transfer

A transaction that appears simple from a registration perspective may have significant tax or stamp-duty consequences. Assess these before signing documents or transferring assets.

Overlooking creditor and lender rights

Loans, charges, guarantees and contractual restrictions can affect the available route. Obtain appropriate advice and consent where required.

Forgetting pending compliance

Outstanding filings and defaults may affect eligibility, timing or risk. Identify them early.

Assuming GST or Udyam details automatically update

Confirm the applicable steps for each registration. Keep the effective date, invoices, records and entity details consistent.

Choosing a structure only to reduce compliance

An LLP may be suitable for one business and unsuitable for another. Consider funding, ownership, liability, tax, contracts and long-term plans together.

Example: a growing consultancy considers incorporation

Suppose two founders operate a consultancy as a partnership. They begin working with larger corporate clients and plan to introduce an investor. They are considering a private limited company.

The right first step is not to submit a conversion form immediately. They should confirm how the partnership is registered, whether the proposed company route is available, what happens to the existing partnership’s assets and contracts, and whether all partners agree to the proposed arrangement.

They should also review the tax treatment of transferring the business, decide how ownership will be reflected in the new company, and identify which customer contracts, bank facilities, registrations and licences require action.

If the partnership cannot or should not use the intended statutory route, a new company and a documented business transfer may be considered. The precise approach must be selected after legal and tax review.

This example illustrates the central principle: the business goal determines the target structure, but the existing entity and applicable law determine the route.

A practical checklist before changing your business structure

Before proceeding, make sure you can answer the following:

  • What is the existing legal structure?
  • What target structure do we need, and why?
  • Is a statutory conversion route available?
  • What eligibility conditions and approvals apply?
  • Are statutory and tax filings up to date?
  • Have we reviewed assets, liabilities, contracts and creditor rights?
  • Have we obtained a tax assessment of the proposed transaction?
  • What will happen to PAN, GST, TDS, Udyam and other registrations?
  • Have we checked bank accounts, loans, licences and intellectual property?
  • Who will manage the transition and verify completion?

Frequently asked questions

1. Can I change my business structure after registration in India?

Often, yes. The available route depends on the existing structure and the target structure. Some changes have a statutory conversion route; others require forming a new entity and transferring the business.

2. Can a sole proprietorship be converted into a private limited company?

A proprietorship generally does not become a company through a direct change of registration type. The usual approach is to incorporate a new company and transfer the business through an appropriately documented arrangement.

3. Can an LLP become a private limited company?

A route may be available under Section 366 of the Companies Act, 2013 and the applicable rules. Eligibility, documents and the current MCA process should be verified before filing.

4. Can a private limited company become an LLP?

A statutory route exists under the LLP Act, subject to applicable eligibility and procedural requirements. Tax treatment must be assessed separately; not every transaction automatically qualifies for tax relief.

5. Can a partnership firm become an LLP?

A partnership firm may be eligible for conversion under the LLP Act if the prescribed conditions are met. The partners should verify the statutory requirements and the current filing process.

6. Will the business keep the same PAN after conversion?

Do not assume that it will. The answer depends on whether the legal person continues or a new entity is formed. Review the tax and registration consequences for the specific route.

7. What happens to GST registration when the structure changes?

The GST action depends on the transaction and the legal identity of the business after the change. Review registration, returns, tax liabilities, eligible credit and invoices before implementation.

8. Does conversion automatically transfer contracts and licences?

Not necessarily. Check each contract, licence and approval. Assignment, amendment, consent or a fresh application may be required.

9. Is changing business structure always tax-free?

No. Any relief depends on the specific legal provision and whether all applicable conditions are met. Obtain a transaction-specific tax assessment.

10. Should I change my business structure just to reduce compliance?

Not without comparing the full implications. Consider liability, ownership, fundraising, tax, contracts, administrative costs and the future direction of the business.

Conclusion

Changing your business structure after registration can be a sensible step when your business goals evolve. But it is not a one-size-fits-all process. A direct statutory conversion, registration as a company, or a new entity with a business transfer may be appropriate in different circumstances.

The safest approach is to identify your current legal structure, confirm the available legal route, assess tax and contractual implications, and prepare a coordinated plan for statutory filings and operational registrations.

Need help with company registration or compliance? FilingPoint can help you understand the applicable process for your business.

  • Phone: +91 72999 72500
  • Email: info@filingpoint.com

A business may obtain GST registration, start issuing invoices and build its customer base, only to discover that its registration has been suspended or cancelled by the tax department.

This can be worrying, especially when customers expect GST invoices, payments are pending, or the business needs to continue trading.

The first thing to understand is that GST registration cancellation is not the same as rejection of a new GST registration application. Rejection occurs when an application for registration is not approved. Cancellation affects a registration that already exists.

The solution is not always to submit another registration application. Depending on the reason, you may need to respond to a notice, correct a compliance issue, apply for revocation, or consider another legally appropriate route.

This guide explains how to assess a cancelled GST registration in India, what to check before taking action, and how to avoid repeating the same problem.

What does GST registration cancellation mean?

GST registration cancellation means that the existing registration has been cancelled under the applicable GST provisions. Cancellation may occur following an application by the taxpayer or action initiated by the proper officer.

The reasons and procedures differ according to the circumstances. For example, a business may apply for cancellation because it has discontinued operations or is no longer liable to be registered. The department may initiate cancellation proceedings where it believes a legal or compliance condition has been breached.

Section 29 of the Central Goods and Services Tax Act, 2017, addresses cancellation of registration. It also makes clear that cancellation does not automatically remove tax liabilities or other obligations relating to the period before cancellation. The applicable provisions and state GST law should be checked for the particular case.

Important: Do not assume that a cancelled GSTIN has erased past tax liabilities, pending returns or earlier non-compliance.

Why might the GST department cancel a registration?

The exact reason should be stated or explained in the relevant notice or order. Common issues that can lead to cancellation proceedings include:

  • Failure to file required GST returns for the applicable period.
  • The business not operating from its declared place of business.
  • Registration obtained through fraud, wilful misstatement or suppression of facts.
  • Certain invoicing or input tax credit violations.
  • Other breaches covered by the applicable GST Act and Rules.

These are examples, not a complete list of every possible ground. The legal basis and facts in the department’s order matter.

Why the reason matters

Two businesses may both see “cancelled” in their GST portal status but require different next steps.

A taxpayer whose registration was cancelled because returns were not filed may need to address outstanding returns and liabilities. A taxpayer whose case concerns the declared business premises may need to examine the premises records, actual business operations and the department’s findings.

The correct response should address the actual reason rather than simply submitting a generic explanation.

Suspension vs cancellation: check the exact status

Suspension and cancellation are not interchangeable terms.

A GST registration may be suspended while cancellation proceedings are pending or in circumstances provided by the rules. Cancellation is a formal outcome that changes the registration status.

Before taking action, check:

  • The status shown on the GST portal.
  • Whether a notice has been issued.
  • Whether a cancellation order has been passed.
  • The date the order was served.
  • The effective date of cancellation, if applicable.
  • Whether any reply or application is pending.

Do not rely only on an email notification, an old screenshot or what a third party has told you. Review the actual portal record and order.

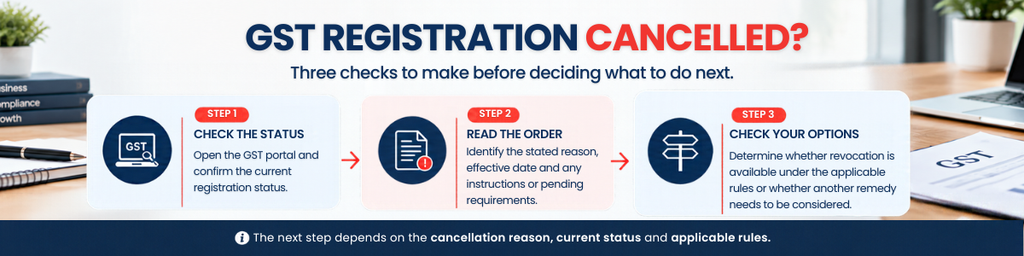
What should you do immediately after receiving a cancellation order?

Use this sequence to organise the case before filing anything.

Step 1: Download the notice and order

Keep copies of the show-cause notice, your reply, the cancellation order and related correspondence. Record the dates on which the documents were issued and served.

Read the reasons carefully. Note the rule or provision cited, the facts alleged and whether the order discusses unanswered notices, missing returns, address verification or another issue.

Step 3: Check your return-filing position

Review the returns due before cancellation, including any periods for which the portal shows outstanding filings. Compare portal information with your accounting records.

Step 4: Review tax and other dues

Check whether tax, interest, late fees or penalties are outstanding. Do not assume that filing a missing return alone resolves every liability.

Step 5: Check whether revocation is available

Revocation is generally relevant when the proper officer has cancelled registration on their own motion. It is not the same as requesting cancellation voluntarily.

If your case does not qualify for revocation, the next step may be different. Verify the legal route before submitting a form.

Step 6: Prepare an evidence-based response

Collect documents that directly address the reason for cancellation. For example, a premises-related case may need relevant address and business-operation evidence. A return-default case needs a return and payment review.

Step 7: Track the next deadline

Record the relevant date and any deadline in the notice, order or applicable rule. If the time limit is close or has passed, obtain advice promptly rather than waiting for another reminder.

What is revocation of GST registration cancellation?

Revocation means reversing a cancellation made by the proper officer, subject to the applicable law and procedure.

Section 30 of the CGST Act and Rule 23 of the CGST Rules deal with revocation of cancellation. The process is not available in every situation: the cancellation must be of the kind for which revocation is permitted.

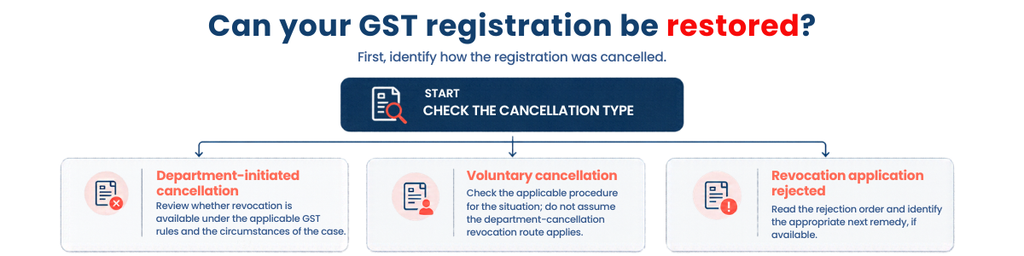
A taxpayer who voluntarily applied to cancel their GST registration should not assume that the same revocation procedure automatically applies. First establish how the cancellation occurred and what order was passed.

Is revocation automatic?

No. An application must meet the applicable conditions and be considered by the proper officer. Filing an application does not itself prove that the registration has been restored.

The taxpayer should monitor the application and any notice or clarification request issued during the process.

What is Form GST REG-21 used for?

Form GST REG-21 is used for an application to revoke cancellation of GST registration where the applicable rules permit it.

Before filing, verify that:

  • The cancellation was initiated by the proper officer.
  • The case qualifies for revocation.
  • Any required returns have been filed.
  • Tax and related amounts required under the rules have been paid.
  • The explanation and supporting evidence address the cancellation grounds.
  • The application is within the applicable time limit, or a permitted extension route is available.

The current rule text and the portal’s live workflow should be checked before submission because procedures and time limits may change.

GST Registration Chennai

What if GST registration was cancelled because returns were not filed?

Non-filing requires careful attention because an application for revocation may not be considered until the relevant return defaults and associated dues have been addressed as required by the rules.

Start by preparing a period-wise list of returns that remain pending. Check the return type, tax period, filing status and any tax, interest, penalty or late fee applicable to the case.

Then reconcile the return information with sales, purchase, bank and accounting records. Filing returns without checking the underlying data can create additional inconsistencies.

A practical checklist

  • Identify all pending returns and periods.
  • Reconcile outward supplies and tax reported.
  • Check eligible input tax credit against supporting records and applicable conditions.
  • Calculate outstanding liabilities using current information.
  • File the returns required for the case.
  • Pay the amounts legally due.
  • Keep acknowledgements and payment records.
  • Review the cancellation order and the current revocation requirements before applying.

Do not assume that clearing one return will automatically restore registration. Follow the required procedure and wait for the relevant order or status update.

What if the deadline for revocation has passed?

Do not assume that the only option is to apply for a new GST registration.

The applicable time limit and any permitted extension must be checked against the current version of Rule 23, relevant notifications and the dates in your case. The current rule text provides for an initial period and a possible extension in qualifying circumstances, subject to the conditions and authority specified in the rule.

This is an area where old online articles can be misleading: earlier versions of the rules used different time limits.

If the deadline appears to have passed:

  1. Confirm the date on which the cancellation order was served.
  2. Check the rule and amendments applicable to your case.
  3. Determine whether a permitted extension or other remedy remains available.
  4. Prepare evidence explaining the delay, where relevant.
  5. Obtain professional advice if the registration is essential to ongoing operations.

Never rely on a generic statement such as “you always have 30 days” or “you can apply at any time.” The applicable law and case facts control.

What if the revocation application is rejected?

A rejected revocation application should be reviewed carefully before taking another step.

Read the rejection order and identify whether the issue relates to eligibility, outstanding returns, payment, missing evidence, an unanswered notice or the time limit.

Do not repeatedly submit the same application without addressing the reason for rejection.

Depending on the facts and applicable law, the next step may involve responding to a notice, reviewing whether an appeal or other remedy is available, or correcting a procedural issue where permitted. The right route depends on the order and the statutory framework.

Keep copies of the application, acknowledgement, notices, replies and rejection order. These documents are important for understanding the decision and assessing available options.

Can Your GST Registration be Restored

Can you continue business after GST registration is cancelled?

A business should not assume it can continue treating itself as a registered taxpayer after cancellation.

The consequences depend on the effective date, the nature of supplies, the applicable provisions and whether a later order restores the registration. A cancelled registration can affect invoicing, tax collection, input tax credit and dealings with customers.

At the same time, cancellation does not necessarily mean that every business activity must cease permanently. The business should obtain advice on what activities may lawfully continue, what tax obligations remain and whether registration is required for future supplies.

Do not issue invoices that represent the business as currently GST-registered if that status is no longer valid. Check the law and the actual registration status before making tax representations to customers.

What happens to earlier tax liabilities and records?

Cancellation does not automatically wipe out obligations relating to earlier periods. Section 29(3) addresses the continuation of liability for tax and other dues and obligations for the period before cancellation.

A business should retain its invoices, books, return records, payment receipts, bank records, purchase documents and correspondence with the department.

If registration is restored, reconcile the period covered by the cancellation and the restoration order. Check which returns or other actions remain necessary and confirm how the portal reflects the status.

A business should not assume that restoration alone fixes every historical issue.

Common mistakes to avoid

Mistake 1: Confusing cancellation with application rejection

They are different procedures. A business that already had a GSTIN should begin with its cancellation order and status.

Mistake 2: Filing without checking the order

The response should address the actual cancellation grounds.

Mistake 3: Ignoring pending returns

Where return defaults are involved, required returns and dues can be central to the revocation process.

Mistake 4: Relying on outdated time limits

Check the current rule and applicable amendments, not an old blog post.

Mistake 5: Assuming revocation is available after every cancellation

The route depends on how cancellation occurred and the applicable provisions.

Mistake 6: Ignoring earlier tax obligations

Cancellation does not erase every liability relating to the pre-cancellation period.

Mistake 7: Treating a submitted application as approval

Track the application and obtain confirmation of the actual outcome.

A practical decision guide

Your situationWhat to review first
You received a cancellation notice but no final orderNotice, reply deadline and evidence
Your GST registration is suspendedPortal status and pending proceedings
The officer has cancelled registrationOrder, effective date and revocation eligibility
Cancellation relates to missing returnsPending returns, tax and related dues
You applied for cancellation voluntarilyCorrect route for your circumstances; do not assume REG-21 applies
Your revocation application was rejectedRejection order and any available remedy
The revocation deadline may have passedCurrent Rule 23 and possible extension provisions
Registration has been restoredOrder, portal status, returns and remaining obligations

This is a starting guide, not a substitute for reviewing the actual order.

How to reduce the risk of future cancellation

A business can reduce avoidable compliance problems by establishing a reliable routine.

  • Maintain a calendar for applicable GST return due dates.
  • Reconcile books and GST returns regularly.
  • Keep the declared principal place of business and supporting records accurate.
  • Respond promptly to notices and verification requests.
  • Monitor GST portal messages and application status.
  • Retain acknowledgements, invoices and payment records.
  • Review changes in the business, ownership, premises or registration details.
  • Seek help when a notice is unclear or a deadline is approaching.

The objective is not just to restore a GSTIN after cancellation. It is to address the underlying issue so the business can manage its tax obligations more consistently.

Frequently asked questions

1. Can I restore a GST registration cancelled by the department?

Possibly. Revocation may be available when the proper officer cancelled the registration on their own motion and the taxpayer satisfies the applicable conditions. Check the cancellation order and current rules.

2. Which form is used to apply for revocation?

Form GST REG-21 is used for an application for revocation of cancellation where the applicable rules permit it.

3. Can I apply for revocation if I have not filed GST returns?

If cancellation occurred because of return non-filing, the relevant returns and amounts due generally need to be addressed as required by the rules before an application can be filed.

4. Is a cancelled GST registration the same as a rejected GST application?

No. Rejection concerns an application for new registration. Cancellation affects an existing registration.

5. Can I apply for revocation after the deadline?

Possibly, depending on the current rules, any permitted extension and the circumstances. Check the current law and the order’s service date promptly.

6. What if the officer rejects my revocation application?

Review the rejection order and identify the reason. Depending on the facts, an appropriate response or other remedy may be available under the applicable law.

7. Does GST cancellation remove earlier tax liabilities?

No. Cancellation does not automatically remove liabilities or obligations relating to the pre-cancellation period.

8. Should I apply for a new GST registration instead?

Do not assume that a fresh application is the right solution. First determine whether revocation or another route is available and whether a new application would be legally appropriate.

Conclusion

A cancelled GST registration needs a prompt, evidence-based response. Start with the cancellation order, confirm the portal status, identify the reason, review pending returns and liabilities, and determine whether revocation is available.

The correct route depends on the way the registration was cancelled, the applicable deadlines and the taxpayer’s compliance position. Avoid relying on outdated online guidance or submitting forms without understanding the order.

Need help understanding your GST registration status or compliance requirements? Filing Point can help you review the issue and identify the appropriate next steps.

📞 +91 72999 72500
📧 enquiry@filingpoint.com

Explore by Category

Auditor Resignation

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online Call FilingPoint.Com Experts Now. Seeking professional assistance for Filing of auditor resignation in India? Trust FilingPoint.Com, India’s Largest Registration and Filing Services Provider, to handle the process seamlessly and ensure timely completion. Call us at +91 72999 72500 or visit https://filingpoint.com to avail of our services and experience a hassle-free auditor resignation process. Introduction to Auditor Resignation Auditor resignation is a significant event in the lifecycle of a private limited company, one person company (OPC), or limited liability partnership (LLP) in India. It occurs when the appointed auditor decides to step down from their position due to various reasons such as conflicts of interest, non-compliance issues, or personal circumstances. Managing the Auditor Resignation Filing Services process effectively is crucial to maintain compliance with regulatory requirements and ensure transparency and accountability in financial reporting. Advantages of Auditor Resignation Filing Services in India for Private Limited Companies, OPCs, and LLPs 1. Compliance Assurance: We ensure compliance with all relevant provisions of the Companies Act, 2013, and other applicable laws and regulations governing auditor resignations in India, minimizing the risk of non-compliance. 2. Timely Completion: Our expert team prioritizes timely completion of the auditor resignation process, ensuring minimal disruption to the company’s operations and financial reporting. 3. Efficient Communication: We handle all communication and correspondence with regulatory authorities, including the Ministry of Corporate Affairs (MCA) and Registrar of Companies (ROC), to notify them of the auditor’s resignation promptly. 4. Smooth Transition: We facilitate a smooth transition between the outgoing auditor and the newly appointed auditor, ensuring continuity in the audit process and adherence to statutory timelines. 5. Documentation Support: We assist businesses in preparing and filing the necessary documentation and forms required for notifying the authorities of the auditor’s resignation, ensuring accuracy and completeness. 6. Independent Assessment: Our team conducts an independent assessment of the reasons for the auditor’s resignation, providing valuable insights and recommendations to address any underlying issues or concerns. 7. Stakeholder Confidence: Effective management of the auditor resignation process enhances stakeholder confidence in the company’s governance practices and financial reporting, maintaining trust and credibility. 8. Risk Mitigation: By managing the auditor resignation process professionally, we help mitigate the risk of reputational damage or regulatory sanctions associated with improper handling of auditor resignations. 9. Expert Guidance: Our experienced professionals provide expert guidance and support throughout the auditor resignation process, addressing any queries or concerns and ensuring compliance with regulatory requirements and best practices. Contact Us for Efficient Auditor Resignation Services in India FilingPoint.Com is your trusted partner for seamless and efficient auditor resignation services tailored to the needs of private limited companies, OPCs, and LLPs in India. With our expertise and commitment to excellence, we ensure compliance with regulatory requirements and facilitate a smooth transition during auditor resignations. Call us at +91 72999 72500 or visit https://filingpoint.com to avail of our services and manage auditor resignations with confidence today.
Call Us Now +91 72999 72500

Business Registration

Company Name Reservation

Company Registration

FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your company registration process. Let us handle your registration needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Company Registration Services: Company Registration in India is a pivotal step for entrepreneurs and business owners looking to establish a legal entity for their ventures. Whether it’s a private limited company, One Person Company (OPC), or Limited Liability Partnership (LLP), registering a company offers numerous advantages, providing a solid foundation for growth, compliance, and credibility in the market. Advantages for Company Registration Services for Private Limited Companies, OPCs, LLPs: 1. Legal Recognition: Company Registration grants legal recognition to the business entity, establishing its separate legal identity distinct from its owners or shareholders, ensuring protection of personal assets and liabilities. 2. Limited Liability Protection: Private limited companies and LLPs offer limited liability protection to their owners, shielding personal assets from business debts and legal obligations, providing financial security and risk mitigation. 3. Access to Funding: Registered companies have better access to funding opportunities from banks, financial institutions, venture capitalists, and angel investors, enabling them to raise capital for business expansion and growth. 4. Credibility and Trust: A registered company instills confidence and trust among customers, suppliers, investors, and stakeholders, enhancing the credibility and reputation of the business in the market. 5. Brand Protection: Registering the company name and logo as trademarks safeguards intellectual property rights, preventing unauthorized use or infringement by competitors, protecting the brand identity and goodwill. 6. Perpetual Succession: Companies enjoy perpetual succession, meaning the existence of the business is not affected by changes in ownership, management, or death of shareholders, ensuring continuity and stability. 7. Tax Benefits: Registered companies are eligible for various tax benefits, incentives, and exemptions provided by the government, reducing the tax burden and optimizing tax planning strategies. 8. Growth Opportunities: Company Registration opens doors to business expansion opportunities such as entering new markets, launching new products or services, and forming strategic partnerships or joint ventures. 9. Compliance and Governance: Registered companies are required to comply with statutory regulations, including filing annual returns, maintaining proper accounting records, conducting board meetings, and adhering to corporate governance standards, ensuring transparency and accountability. Experience the seamless process of Company Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in establishing your business entity while you focus on realizing your entrepreneurial vision. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

GST Address Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your GST Address Change process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Address Change Services in GST: GST (Goods and Services Tax) Address Change in India is a critical requirement for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) looking to update their business address with the GST authorities. This process involves submitting the necessary documentation and making the required changes to ensure accurate tax compliance, offering numerous advantages to businesses and facilitating seamless operations. Advantages for Address Change Services in GST for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Updating the GST address ensures compliance with GST regulations, avoiding potential penalties or legal consequences associated with outdated or incorrect business information. 2. Accurate Tax Reporting: A correct GST address ensures accurate tax reporting and invoicing, reducing the risk of errors and discrepancies in GST filings and facilitating smooth interactions with customers and vendors. 3. Seamless Business Operations: A current GST address eliminates disruptions in business operations, ensuring that important communications, notices, and correspondences from the GST authorities reach the company promptly without delays or complications. 4. Improved Credibility: Maintaining up-to-date business information, including the GST address, enhances the company’s credibility and trustworthiness among customers, suppliers, and other stakeholders, fostering stronger business relationships. 5. Avoidance of Communication Errors: Updating the GST address prevents communication errors and misunderstandings, ensuring that the company receives important notifications, alerts, and updates from the GST authorities without any issues. 6. Efficient Logistics and Deliveries: A correct GST address facilitates efficient logistics and deliveries, ensuring that goods and services are shipped to the correct location without delays or misplacements, thereby enhancing customer satisfaction. 7. Enhanced Visibility: A current GST address enhances the company’s visibility in the GST ecosystem, making it easier for customers, suppliers, and regulatory authorities to locate and engage with the business, thereby boosting its market presence. 8. Seamless Expansion: Updating the GST address streamlines the process of expanding or relocating business operations to new locations, ensuring that the company’s tax registrations and compliance obligations are updated accordingly. 9. Proactive Compliance Management: Regularly updating the GST address demonstrates proactive compliance management and a commitment to maintaining accurate business records, reducing the risk of non-compliance and associated penalties. Experience the seamless process of GST Address Change with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with GST regulations while you focus on growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

GST Name Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your GST Name Change process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Name Change in GST: GST Name Change in India is a significant procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) looking to update their GST registration details due to a change in the business name. This process involves submitting the necessary documentation to the GST authorities, offering numerous advantages to businesses and ensuring seamless compliance with tax regulations. Advantages for Name Change in GST for Private Limited Companies, OPCs, LLPs: 1. Compliance with Legal Requirements: Changing the GST registration name ensures compliance with GST regulations, avoiding potential penalties or legal consequences associated with outdated or incorrect registration information. 2. Reflects Updated Business Identity: Updating the GST registration name reflects the updated business identity, ensuring that the company’s tax records accurately represent its current legal entity and branding. 3. Enhanced Brand Recognition: A changed GST registration name enhances brand recognition and visibility in the market, aligning the company’s tax registration with its brand identity and facilitating stronger market presence. 4. Streamlined Business Operations: A current GST registration name streamlines business operations, ensuring that invoices, documents, and communications accurately reflect the company’s legal name, thereby reducing confusion and errors. 5. Improved Customer Trust: A changed GST registration name instills trust and confidence in customers, suppliers, and other stakeholders, as it demonstrates the company’s commitment to transparency and professionalism. 6. Clear Communication Channels: Updating the GST registration name clarifies communication channels with the GST authorities and other government agencies, ensuring that notifications, alerts, and updates are received promptly and accurately. 7. Facilitates Contractual Agreements: A changed GST registration name facilitates the execution of contractual agreements and legal documents, ensuring that the company’s tax registration aligns with its contractual obligations and commitments. 8. Enables Seamless Transition: Changing the GST registration name enables a seamless transition for the company, allowing it to adapt its tax registration to reflect changes in its business structure or branding without disruptions. 9. Demonstrates Adaptability: Updating GST registration with a name change demonstrates the company’s adaptability and responsiveness to market dynamics, showcasing its ability to evolve and grow in line with changing business requirements. Experience the seamless process of GST Name Change with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with GST regulations while you focus on driving your business forward. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Address Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your IE Code Address Change process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for IE Code Address Change: IE Code Address Change in India is a crucial procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) engaged in import-export activities. This process involves updating the registered address of the Importer-Exporter (IE) Code with the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuity of their international trade operations. Advantages for IE Code Address Change for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Updating the IE Code address ensures compliance with DGFT regulations, avoiding penalties or legal consequences associated with outdated or incorrect address information. 2. Uninterrupted Trade Operations: IE Code Address Change ensures uninterrupted trade operations, allowing businesses to continue importing and exporting goods and services without disruptions or delays. 3. Legal Compliance with Banks: Banks and financial institutions require accurate IE Code address information for processing international transactions and providing trade finance facilities, making IE Code Address Change essential for maintaining banking relationships. 4. Facilitates Smooth Customs Clearance: Updating the IE Code address expedites customs clearance processes, reducing the time and effort required for importing and exporting goods, thereby enhancing operational efficiency and reducing costs. 5. Enhanced Credibility: A current and accurate IE Code address enhances the credibility and trustworthiness of the business in the eyes of international suppliers, buyers, and regulatory authorities, fostering stronger relationships and partnerships. 6. Ensures Proper Documentation: Updating the IE Code address ensures that all trade-related documents, including invoices, shipping documents, and contracts, reflect the correct address information, minimizing errors and discrepancies in documentation. 7. Compliance with Export Control Laws: IE Code Address Change ensures compliance with export control laws, regulations, and government policies, mitigating the risk of legal liabilities and penalties associated with non-compliance. 8. Facilitates Government Benefits: Businesses with updated IE Code address details may be eligible for various government incentives, benefits, and schemes aimed at promoting exports and boosting foreign trade. 9. Enables Growth Opportunities: A current IE Code address facilitates business growth and expansion into new international markets, enabling businesses to capitalize on emerging opportunities and diversify their revenue streams. Experience the seamless process of IE Code Address Change with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on expanding your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Director Addition

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your IE Code Director Addition process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Director Addition in IE Code: IE Code Director Addition in India is a significant procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) involved in import-export activities. This process involves adding directors to the Importer-Exporter (IE) Code with the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuity of their international trade operations. Advantages for Director Addition in IE Code for Private Limited Companies, OPCs, LLPs: 1. Enhanced Governance Structure: Adding directors to the IE Code ensures an enhanced governance structure, reflecting the accurate representation of the company’s management team in its import-export operations. 2. Compliance with Regulatory Requirements: IE Code Director Addition ensures compliance with DGFT regulations, as all directors involved in import-export activities must be listed in the IE Code to legally represent the company. 3. Expanded Decision-Making Authority: Including additional directors in the IE Code broadens the decision-making authority within the company, enabling a more collaborative approach to import-export strategies and operations. 4. Improved Operational Efficiency: With more directors listed in the IE Code, tasks related to import-export activities can be delegated more effectively, leading to improved operational efficiency and streamlined processes. 5. Redundancy Planning: Adding directors to the IE Code provides redundancy planning, ensuring continuity of import-export operations even in the absence or unavailability of key personnel. 6. Enhanced Credibility: A comprehensive list of directors in the IE Code enhances the credibility of the company in the eyes of international partners, suppliers, and regulatory authorities, fostering trust and confidence. 7. Facilitates Business Expansion: IE Code Director Addition facilitates business expansion initiatives by providing the necessary legal framework to support growth into new international markets and territories. 8. Strengthened Legal Representation: With multiple directors listed in the IE Code, the company benefits from strengthened legal representation in import-export transactions and dealings with international entities. 9. Enables Strategic Partnerships: Having a robust IE Code with all relevant directors listed enables the company to enter into strategic partnerships and collaborations with international counterparts, leveraging collective expertise and resources for mutual benefit. Experience the seamless process of IE Code Director Addition with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on expanding your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Director Removal

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, guarantees timely completion of your IE Code Director Removal process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Director Removal in IE Code: IE Code Director Removal in India is a crucial procedure for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) involved in import-export activities. This process involves removing directors from the Importer-Exporter (IE) Code with the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuity of their international trade operations. Advantages for Director Removal in IE Code for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Removing directors from the IE Code ensures compliance with DGFT regulations, as only active directors involved in import-export activities should be listed in the IE Code. 2. Streamlined Governance Structure: IE Code Director Removal streamlines the governance structure of the company, ensuring that only relevant and authorized personnel are associated with import-export operations. 3. Legal Clarity: Removing inactive or unauthorized directors from the IE Code provides legal clarity and transparency, mitigating the risk of misunderstandings or disputes regarding the representation of the company in import-export transactions. 4. Operational Efficiency: With unnecessary directors removed from the IE Code, import-export operations can be managed more efficiently, leading to improved productivity and streamlined processes. 5. Reduces Administrative Burden: IE Code Director Removal reduces the administrative burden on the company by eliminating the need to involve inactive or unauthorized directors in import-export-related tasks and decision-making processes. 6. Enhanced Security: Removing unauthorized directors from the IE Code enhances the security and integrity of import-export operations, reducing the risk of unauthorized access or misuse of IE Code-related information. 7. Facilitates Succession Planning: IE Code Director Removal enables effective succession planning by ensuring that only designated and authorized individuals are listed in the IE Code to represent the company in import-export activities. 8. Maintains Compliance with Banking Requirements: Banks and financial institutions require accurate IE Code information for processing international transactions and providing trade finance facilities. IE Code Director Removal ensures compliance with banking requirements by updating the IE Code with only active and authorized directors. 9. Supports Strategic Decision-Making: With unnecessary directors removed from the IE Code, the company’s leadership can focus on strategic decision-making and planning for the future of import-export operations without distractions or complications. Experience the seamless process of IE Code Director Removal with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on optimizing your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely IE Code Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for IE Code Registration Services: IE Code Registration in India is a crucial requirement for businesses engaged in the import and export of goods and services. Issued by the Directorate General of Foreign Trade (DGFT), Importer Exporter Code (IE Code) is a unique 10-digit identification number that facilitates international trade transactions. Obtaining an IE Code offers several advantages to private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs), enabling them to engage in global trade activities seamlessly. Advantages for IE Code Registration Services for Private Limited Companies, OPCs, LLPs: 1. Facilitates International Trade: IE Code Registration facilitates international trade by providing businesses with a unique identification number recognized by customs authorities for importing and exporting goods and services. 2. Requirement for Customs Clearance: IE Code is mandatory for customs clearance of goods at Indian ports and airports, ensuring smooth and hassle-free clearance of imported and exported shipments. 3. Enables Access to Export Incentives: Registered exporters with IE Code are eligible to avail various export incentives and benefits offered by the government, such as duty drawback, export subsidies, and export finance schemes. 4. Establishes Credibility: Having an IE Code enhances the credibility and reliability of businesses in the eyes of overseas suppliers, buyers, banks, and financial institutions, facilitating trust and confidence in trade transactions. 5. Expands Market Reach: IE Code enables businesses to explore new markets and expand their customer base globally by engaging in cross-border trade activities without any restrictions. 6. Compliance with Legal Requirements: IE Code Registration ensures compliance with the Foreign Trade Policy (FTP) of India and other relevant regulations governing import and export activities, avoiding penalties or legal consequences for non-compliance. 7. Enables Direct Exporting: IE Code empowers businesses to engage in direct exporting, allowing them to negotiate better terms with overseas buyers, establish direct business relationships, and maximize profits. 8. Access to Government Schemes: Registered exporters with IE Code can participate in various government schemes and initiatives aimed at promoting exports, such as trade fairs, exhibitions, and international buyer-seller meets. 9. Simplifies Banking Transactions: IE Code facilitates smooth banking transactions for international trade, including receiving payments in foreign currency, opening and maintaining foreign currency accounts, and availing export finance facilities. Experience the seamless process of IE Code Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in obtaining your IE Code efficiently while you focus on expanding your global trade opportunities. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

IE Code Renewal

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely completion of your IE Code Renewal process. Let us handle your compliance needs efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for IE Code Renewal: IE Code Renewal in India is an essential requirement for private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) engaged in import-export activities. This process involves renewing the Importer-Exporter (IE) Code issued by the Directorate General of Foreign Trade (DGFT), offering numerous advantages to businesses and ensuring seamless continuation of their international trade operations. Advantages for IE Code Renewal for Private Limited Companies, OPCs, LLPs: 1. Compliance with Regulatory Requirements: Renewing the IE Code ensures compliance with the regulatory requirements of the DGFT, avoiding penalties or legal consequences associated with expired or invalid IE Codes. 2. Uninterrupted Trade Operations: IE Code Renewal ensures uninterrupted trade operations, allowing businesses to continue importing and exporting goods and services without disruptions or delays. 3. Access to International Markets: A valid IE Code enables businesses to access international markets, facilitating cross-border trade and expanding business opportunities beyond domestic boundaries. 4. Credibility and Trust: Renewing the IE Code enhances the credibility and trustworthiness of the business in the eyes of international suppliers, buyers, and regulatory authorities, fostering stronger relationships and partnerships. 5. Compliance with Banking Requirements: Banks and financial institutions often require a valid IE Code for processing international transactions and providing trade finance facilities, making IE Code Renewal essential for maintaining banking relationships. 6. Seamless Customs Clearance: A valid IE Code expedites customs clearance processes, reducing the time and effort required for importing and exporting goods, thereby enhancing operational efficiency and reducing costs. 7. Legal Protection: Renewing the IE Code provides legal protection to businesses engaged in international trade, ensuring compliance with export control laws, regulations, and government policies. 8. Facilitates Government Benefits: Businesses with a valid IE Code may be eligible for various government incentives, benefits, and schemes aimed at promoting exports and boosting foreign trade. 9. Enables Growth and Expansion: A renewed IE Code facilitates business growth and expansion into new international markets, enabling businesses to capitalize on emerging opportunities and diversify their revenue streams. Experience the seamless process of IE Code Renewal with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us ensure your compliance with DGFT regulations while you focus on expanding your international trade operations. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

LLP Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely LLP Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for LLP Registration Services: LLP Registration in India is a popular choice for entrepreneurs and businesses looking for a flexible and less burdensome form of business structure. A Limited Liability Partnership (LLP) combines the benefits of a partnership with limited liability protection, making it an attractive option for various industries. Registering an LLP offers several advantages to private limited companies, One Person Companies (OPCs), and other entities, providing a legal framework for collaboration and growth. Advantages for LLP Registration Services for Private Limited Companies, OPCs, LLPs: 1. Limited Liability Protection: LLP Registration provides limited liability protection to its partners, ensuring that their personal assets are safeguarded from business liabilities and debts, offering financial security. 2. Separate Legal Entity: An LLP is considered a separate legal entity distinct from its partners, allowing it to enter into contracts, own assets, sue or be sued in its own name, enhancing credibility and legal recognition. 3. Flexibility in Management: LLPs offer flexibility in management and operations, allowing partners to define their roles, responsibilities, profit-sharing arrangements, and decision-making processes as per the LLP Agreement. 4. Minimal Compliance Requirements: LLPs have fewer compliance requirements compared to private limited companies, such as no requirement for mandatory audits for smaller LLPs, reducing administrative burden and costs. 5. Tax Benefits: LLPs are taxed as partnerships, with profits taxed at the partner level, offering tax benefits such as pass-through taxation, avoiding double taxation on profits distributed to partners. 6. Easy Transferability of Ownership: LLPs allow for easy transferability of ownership interests, enabling partners to transfer their ownership stake to other individuals or entities as per the terms of the LLP Agreement. 7. No Minimum Capital Requirement: LLPs do not have any minimum capital requirement, allowing partners to contribute capital as per their agreement, making it accessible to startups and small businesses. 8. Continuity of Existence: LLPs enjoy perpetual succession, meaning the LLP continues to exist irrespective of changes in partners or management, providing continuity and stability to the business. 9. Enhanced Credibility: Registering as an LLP enhances the credibility and trustworthiness of the business in the eyes of customers, suppliers, lenders, and stakeholders, facilitating smoother business transactions. Experience the seamless process of LLP Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in establishing your LLP efficiently while you focus on building and growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

MSME Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely MSME Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for MSME Registration Services: MSME Registration in India holds significant importance for businesses aiming to avail of various benefits and incentives provided by the government for Micro, Small, and Medium Enterprises (MSMEs). This registration acknowledges the contribution of small businesses to the country’s economy and provides them with exclusive benefits and support. Whether you operate as a private limited company, One Person Company (OPC), or Limited Liability Partnership (LLP), obtaining MSME Registration offers numerous advantages, fostering growth and development. Advantages for MSME Registration Services for Private Limited Companies, OPCs, LLPs: 1. Access to Subsidized Loans: MSME-registered entities are eligible for collateral-free loans and subsidies under various government schemes, facilitating access to finance for business expansion and development. 2. Priority Lending by Banks: Banks often prioritize lending to MSMEs, offering lower interest rates and favorable terms on loans, fostering financial stability and growth for registered businesses. 3. Credit Guarantee Fund Scheme: MSME Registration enables businesses to avail of the Credit Guarantee Fund Scheme, providing collateral-free credit facilities and reducing the risk for lenders. 4. Preference in Government Tenders: MSME-registered companies receive preference in government procurement contracts and tenders, promoting their participation in public sector projects and initiatives. 5. Concessions on Electricity Bills: Registered MSMEs enjoy concessions and rebates on electricity bills, reducing operational costs and improving competitiveness in the market. 6. Subsidies for Technology Upgradation: MSMEs can benefit from subsidies and incentives for adopting modern technology, enhancing productivity, efficiency, and competitiveness in the industry. 7. Protection Against Delayed Payments: MSME Registration enables businesses to seek redressal for delayed payments from buyers or clients under the Micro, Small, and Medium Enterprises Development (MSMED) Act, ensuring timely receivables. 8. Skill Development and Training Programs: MSME-registered entities have access to skill development and training programs organized by the government to enhance the capabilities and competencies of the workforce. 9. Marketing Assistance and Support: The government provides marketing assistance and support to MSMEs through various schemes, helping them promote their products and services domestically and internationally. Experience the seamless process of MSME Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in obtaining your MSME Registration efficiently while you focus on growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

Name Change

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely and accurate completion of your company’s name change process. Trust us to handle your documentation needs efficiently. Call us today at +91 72999 72500 or visit https://filingpoint.com. Introduction for ROC Company Name Change Filing Services: Name change in India is a significant decision for private limited companies, one person companies (OPCs), and limited liability partnerships (LLPs). It involves altering the company’s name to better reflect its evolving business objectives, market positioning, or ownership structure. This process requires compliance with legal formalities and regulatory approvals. Let’s explore the advantages of opting for a name change for businesses in India. Advantages of Name Change in India for Private Limited Companies, OPCs, and LLPs: 1. Brand Reinvention: Changing the company’s name allows for a fresh start and enables brand reinvention, helping to attract new customers, investors, and business partners. 2. Market Differentiation: A new name can differentiate the company from competitors, helping it stand out in the market and gain a competitive edge. 3. Reflecting Company Evolution: As companies evolve and expand their offerings or change their strategic direction, a name change can better reflect these changes and align with the company’s current identity. 4. Correcting Misconceptions: In cases where the existing name causes confusion or misconceptions about the company’s products, services, or values, a name change can help clarify the company’s identity and positioning. 5. Ownership Transition: In the event of ownership changes or mergers, a name change can signal the transition to new management or ownership, providing clarity to stakeholders and customers. 6. Legal Compliance: A name change ensures compliance with legal requirements and regulations governing company names, avoiding any legal challenges or complications in the future. 7. Enhancing Brand Image: A well-chosen new name can enhance the company’s brand image and reputation, positioning it as innovative, forward-thinking, and responsive to market trends. 8. Rebranding Opportunities: A name change provides an opportunity for comprehensive rebranding, including updates to the company’s logo, website, marketing materials, and messaging, to create a cohesive brand identity. 9. Attracting Investment: A new name can generate renewed interest from investors and stakeholders, signaling the company’s commitment to growth and adaptation to market dynamics. In conclusion, opting for a name change in India offers numerous advantages for private limited companies, OPCs, and LLPs, including brand reinvention, market differentiation, and legal compliance. Trust FilingPoint.Com to deliver expert name change services tailored to your company’s specific needs. Contact us today at +91 72999 72500 or visit https://filingpoint.com for reliable and efficient assistance.
Call Us Now +91 72999 72500

Name Ideas

OPC Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely OPC Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for OPC Registration Services: OPC Registration in India offers a unique opportunity for entrepreneurs and small businesses to establish a separate legal entity with limited liability while retaining the benefits of sole proprietorship. One Person Company (OPC) is an ideal choice for single entrepreneurs looking to start their venture with limited liability protection. Whether you operate as a private limited company, OPC, or Limited Liability Partnership (LLP), registering as an OPC comes with several advantages, providing a conducive environment for business growth and success. Advantages for OPC Registration Services for Private Limited Companies, OPCs, LLPs: 1. Limited Liability Protection: OPC Registration provides limited liability protection to its sole owner, safeguarding personal assets from business debts and liabilities, ensuring financial security. 2. Separate Legal Entity: An OPC is considered a separate legal entity distinct from its owner, enabling it to enter into contracts, own assets, sue or be sued in its own name, enhancing credibility and legal recognition. 3. Minimal Compliance Requirements: OPCs have fewer compliance requirements compared to private limited companies, such as no requirement for mandatory annual general meetings (AGMs) or rotation of auditors, reducing administrative burden and costs. 4. Single Ownership: OPC allows a single individual to own and manage the entire business, providing full control and autonomy over decision-making and operations, eliminating the need for external shareholders. 5. Easy Transferability of Ownership: OPC allows for easy transferability of ownership through transfer of shares, enabling the owner to sell or transfer the business to another individual or entity as per the provisions of the Companies Act, 2013. 6. Continuity of Existence: OPC enjoys perpetual succession, meaning the OPC continues to exist irrespective of changes in ownership or management, providing continuity and stability to the business. 7. Tax Benefits: OPCs enjoy tax benefits similar to private limited companies, including lower corporate tax rates and eligibility for deductions and exemptions under the Income Tax Act, 1961. 8. Enhanced Credibility: Registering as an OPC enhances the credibility and trustworthiness of the business in the eyes of customers, suppliers, lenders, and stakeholders, fostering confidence and facilitating smoother business transactions. 9. Ease of Conversion: OPCs have the flexibility to convert into private limited companies or LLPs as the business grows and expands, providing scalability and adaptability to changing business needs. Experience the seamless process of OPC Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in establishing your OPC efficiently while you focus on building and growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

Registration Services

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, your trusted partner for seamless business registration solutions. Count on us to handle all your registration needs promptly and efficiently. Call us at +91 72999 72500 or visit https://filingpoint.com for expert assistance today. Introduction for Registration Services: Registration services play a pivotal role in establishing the legal identity and framework of private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs) in India. From company incorporation to obtaining necessary licenses and permits, efficient registration services are crucial for ensuring compliance and initiating business operations. FilingPoint.Com offers comprehensive registration services tailored to meet the specific needs of businesses, empowering them to thrive in the competitive Indian market. Advantages of Registration Services for Private Limited Companies, OPCs, and LLPs: 1. Legal Compliance: Ensure adherence to regulatory requirements and legal compliance by obtaining all necessary registrations, licenses, and permits for your business, avoiding potential penalties or legal complications. 2. Established Legal Identity: Secure the legal identity of your business through proper registration, enhancing credibility and trustworthiness among clients, investors, and stakeholders. 3. Access to Government Schemes: Facilitate access to government schemes, subsidies, and incentives available exclusively for registered businesses, boosting growth and profitability. 4. Enhanced Marketability: Gain a competitive edge in the market by showcasing your registered status, demonstrating reliability and commitment to professionalism. 5. Facilitated Banking and Financing: Open business bank accounts, avail loans, and attract investments more easily with proper registration, facilitating financial transactions and business expansion. 6. Limited Liability Protection: Shield personal assets from business liabilities by opting for registration as a private limited company or LLP, offering limited liability protection to shareholders and partners. 7. Operational Continuity: Ensure uninterrupted business operations by securing necessary registrations and licenses, mitigating the risk of operational disruptions or closures due to non-compliance. 8. Tax Benefits: Avail tax benefits and incentives available to registered businesses, optimizing tax planning strategies and maximizing profitability. 9. Expert Guidance: Benefit from the expertise of professionals at FilingPoint.Com who possess in-depth knowledge of registration procedures and regulatory requirements, ensuring smooth and hassle-free registration process. Partner with FilingPoint.Com today to leverage the advantages of expert registration services tailored to your business needs. Call us at +91 72999 72500 or visit https://filingpoint.com for reliable assistance and support. Let us be your partner in achieving business success and growth.
Call Us Now +91 72999 72500

Trademark Registration

Filing Point - India's Best Business Consultant Who Provides All Kinds of Registrations and Filing Services Online FilingPoint.Com, India’s Largest Registration and Filing Services Provider, ensures timely Trademark Registration for your private limited company, OPC, or LLP. Let us simplify your registration process efficiently! Call us at +91 72999 72500 or Visit https://filingpoint.com. Introduction for Trademark Registration Services: Trademark Registration in India plays a pivotal role in protecting the brand identity and intellectual property of businesses, including private limited companies, One Person Companies (OPCs), and Limited Liability Partnerships (LLPs). It provides legal recognition and exclusive rights to use a trademark for goods or services, distinguishing them from competitors in the market. Registering a trademark is essential for building brand reputation, preventing infringement, and enhancing market visibility. Advantages for Trademark Registration Services for Private Limited Companies, OPCs, LLPs: 1. Legal Protection: Trademark Registration provides legal protection against unauthorized use or infringement of the trademark, enabling businesses to take legal action against infringers and counterfeiters. 2. Exclusive Rights: Registered trademark owners enjoy exclusive rights to use the trademark for their goods or services, preventing others from using similar marks that may cause confusion among consumers. 3. Brand Recognition: Trademark Registration enhances brand recognition and reputation, making it easier for customers to identify and choose products or services offered by the business. 4. Market Expansion: A registered trademark facilitates market expansion by providing a unique identity and distinguishing the business from competitors, attracting new customers and expanding market reach. 5. Asset Value: A registered trademark is an intangible asset that adds value to the business, enhancing its marketability, attracting investors, and increasing the overall valuation of the company. 6. Licensing Opportunities: Trademark Registration opens up opportunities for licensing and franchising arrangements, allowing businesses to generate additional revenue by granting others the right to use the trademark. 7. Global Protection: Trademark Registration in India provides protection within the country and can also serve as a basis for seeking trademark protection in other countries, facilitating international expansion. 8. Prevention of Domain Name Misuse: Registered trademarks help prevent domain name misuse and cyber-squatting, ensuring that the business’s online presence remains secure and consistent with its brand identity. 9. Competitive Advantage: A registered trademark provides a competitive advantage in the market by creating barriers to entry for competitors, establishing brand loyalty among customers, and strengthening market position. Experience the seamless process of Trademark Registration with FilingPoint.Com, your trusted partner for registration and filing services in India. Let us assist you in protecting your brand identity and intellectual property efficiently while you focus on growing your business. Call us at +91 72999 72500 or Visit https://filingpoint.com for expert assistance today!
Call Us Now +91 72999 72500

START WITH CONFIDENCE

Company Registration

Get your Private Limited company registered with expert guidance, from the first name check to incorporation.